
True fee-only fiduciary RIAs keep their clients more loyal than any other advice model, yet they are steadily losing ground to hybrid and insurance-licensed rivals, according to new research from Cerulli Associates.
The report commissioned by Credent Wealth Management, an Indiana-based fee-only RIA with $5 billion in assets under management, found that among RIAs with at least that much in assets, true fee-only independent firms – those with no affiliated broker-dealer and no insurance licenses – held 34% of assets at year-end 2025, down from 42% in 2020. Hybrid RIAs with brokerage businesses held steady at 51%, while independent RIAs with insurance licenses doubled their share to 14%.
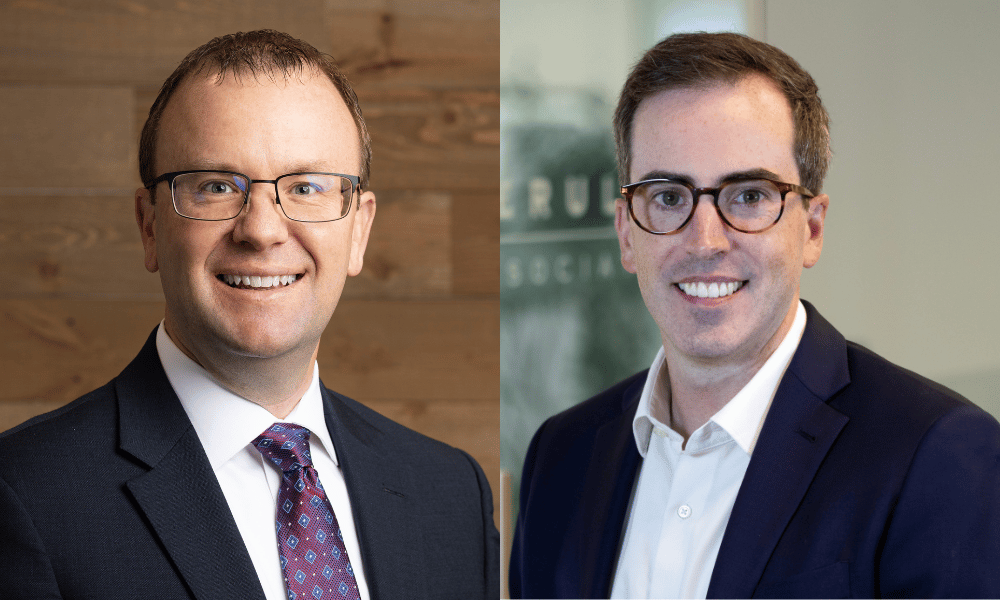
Despite the five-year trend, David Hefty, co-founder and CEO of Credent, remains optimistic that the fee-only fiduciary model has more growth ahead of it, as long as enough firms hold the line.
"You have to choose to put clients first," Hefty said. "No one's going to make you do it. No regulatory body, no government, nothing. ... It's a choice."
The fee-only segment is still expanding, just more slowly. Based on a first-of-its-kind market sizing analysis, Cerulli determined that the number of $5 billion-plus true fee-only firms rose from 83 to 121 between 2020 and 2025, a 7.8% compound annual growth rate. By contrast, hybrid RIAs grew 12.4% a year, from 104 to 186 firms, and insurance-licensed RIAs grew 37.3% a year, from seven to 36.
Hefty said he's gotten a sense of that shift firsthand as a bidder on succession deals, noting that some buyers price in revenue from moving acquired clients into commission products when putting together their offers.
"Sometimes these buyers are factoring in the percentage of assets that they're going to move out of a 75-basis point recurring revenue situation, maybe put into a 5-7% equity index commission up front, or a life insurance commission, which is 50% to 100% year-one premium," Hefty said. "Sometimes the advisors on the selling end don't really know [or] understand this."
Read more: To be a fiduciary, or not to be a fiduciary?
For Brendan Powers, a senior director at Cerulli who managed the project, the report also opens up an opportunity to better define a market that's grown more complex as it matured.
"You've got these three subsegments of RIAs that exist now when, historically, folks had considered fiduciary and RIA to be interchangeable," he said.
While the fiduciary fee-only RIA has lagged other models in growth over the past decade, Power said the trend doesn't reflect any weakness in the firms or the models they operate with.
"That's not because they're any worse than these other firms from a service point of view," he said. "It's very simply that they're getting acquired … or they're acquiring an affiliated broker-dealer or insurance capabilities, thus moving them from one segment to another.
"We do definitely see some of the advisors who break away from a captive environment kind of coming full circle back into a captive environment as they're acquired by one of these hybrid RIAs," he added.
At this point, the most prolific deal machines show few signs of stalling. Even as third-quarter volume fell 17%, consolidators handled 53% of RIA deals through September, according to DeVoe & Company.
At Credent, Hefty says the ownership structure includes only 11% outside capital, and it aims to keep more than 60% of ownership internal.
Among investors who say their advisor must always act in their best interest, Cerulli found nearly three-quarters (73%) are satisfied and not looking for a new provider. That falls to 48% among those investors who say their advisor may put their own interests first, and to 42% when they say their advisor acts in their best interest only some of the time.
Hefty argued those descriptions map directly to the three models in Cerulli's research going from fee-only firms to hybrid RIAs.
"I find that ironic that ... the fee-only model, which has the 73% [satisfaction rate], is losing market share, and the models that represent a combination in this kind of like this cloudy water of 'I don't know if you're a fiduciary or a broker, I have no idea what's going on' has the least satisfaction. And those are the market shares that are just growing wildly," he said.
Perhaps not surprisingly, affluent Americans' appetite for advice is rising across the board. The share of affluent investors who consider themselves advised rose from 35% in 2009 to 50% in 2025, and 69% now say they are willing to pay for advice, Cerulli found.
Cerulli estimates the average $1.5 million RIA client pays about 147 basis points a year – 92 bps in advisory fees and 55 bps in investment product costs – before commissions and other charges. Still, a sizeable 15% minority of affluent investors are unsure how their provider is paid.
From his veteran vantage point, Hefty said technology has removed most of the practical barriers for advisors who want to become or stay fee-only.
"It's never been easier as an advisor to be full-service, comprehensive, and fee-only," he said.
Clients looking for an exclusively fiduciary relationhip, he said, should ask three probing questions:
He said the first may draw only half an answer, and he clarified that costs often climb at firms that both manufacture products and advise on them, particularly as portfolios add illiquid alternatives.
"The total cost of investing actually goes up with wealth, not down," he said.
While he doesn't claim to have a perfect view of the future, Hefty expects private equity capital will keep lifting succession valuations, which in turn will keep the current shift going.
Some private equity-backed firms count conversions of existing fee-based assets into commission products toward their organic growth targets, he added.
"You can just shuffle the shell game and move things out of a fee-based relationship with an existing client, move it into commission-based, and it's actually been counted as organic growth on a growth hurdle in these contracts," Hefty said. "I don't see that trend reversing or slowing down."
Latest DeVoe reports highlights IBDs buying practices and building W-2 RIAs, while an RIA dealmaker say buyers now pay more in equity, not cash.
Self-employed clients can now make after-tax contributions and Roth conversions on the platform as the custodian deepens its RIA retirement push.
Jim Atwood and Phil Scott self-fund their wirehouse breakaway as rival firms sweeten pay to retain top producers.
About 50% of Mercer’s net new assets in the first half of 2026 came through custodian referral programs, as CEO Dave Welling says the RIA is “adding over a billion dollars every month of new clients hiring Mercer as their advisor.”
Advisor Services drew $120 billion in new assets as Schwab plugged into Claude and applied safeguards blocking unauthorized AI agents.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

