
The registered investment advisor M&A boom shows no sign of slowing, but the deals dominating headlines mask a quieter problem: most independent advisors are not selling to a consolidator at all. They are running solo or small-team shops with no next-generation partner, no internal buyer, and no timeline for what happens next. When a founder retires, becomes ill, or dies without a plan, clients and staff are often the last to know — a pattern that has made succession planning the industry's biggest blind spot even as firm valuations climb.
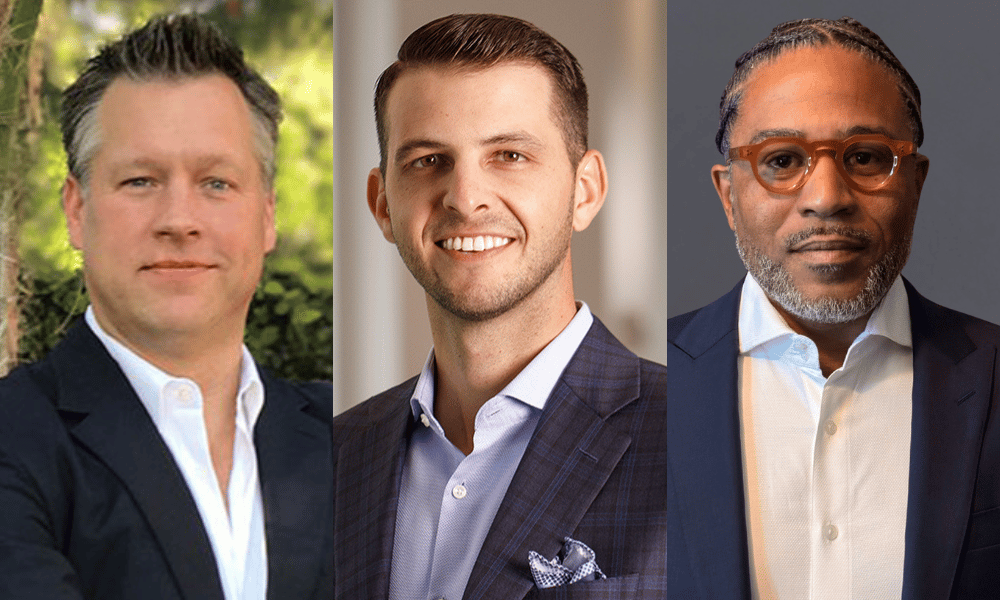
According to Mike Papedis, founder and CEO of Fusion Financial Partners, the clearest warning sign that an advisor is heading toward an unplanned exit is when the entire firm revolves around one person.
"If one person owns the client relationships, manages the firm, makes all key decisions, owns all firm institutional knowledge, and is the single person clients trust, that is the definition of key-person dependency," Papedis said.
Other red flags build over time, Papedis said: no identified successor, no buy-sell agreement, and no succession arrangement with another advisor in the founder's network. As a founder nears the end of a career, he added, a firm often quietly stops reinvesting in technology, people, or growth.
Papedis poses a simple test to any small RIA owner: "If you couldn't come into the office tomorrow, who would run the firm?" If the answer isn't immediate and specific, that's where the work needs to start.
When a solo advisor exits suddenly without a buyer lined up, Papedis said, an orderly transition becomes an emergency. Clients are left wondering who their advisor is now. Employees don't know if they still have jobs. A founder's spouse, family, or estate may suddenly be managing or winding down a business they never expected to inherit. Meanwhile, prospective buyers negotiate against a fast-depreciating asset, and enterprise value can evaporate quickly.
"Many small RIAs have clients who have been with the founder 20, 30 or more years," Papedis said. "Those clients entrusted the advisor during their earning years, and now with retirement, their estate, family and some of the most consequential decisions in their lives. We hear this one all the time, clients start asking their advisor, 'who is going to take care of me when you retire?' The clients deserve more than being introduced to an ill-planned succession plan during a crisis."
Papedis said the first practical step is building a continuity plan today: identify an external advisor or firm that could step in during an emergency, document processes and vendor relationships so nothing lives only in the founder's head, and establish a reasonable valuation before working backward from a likely retirement horizon.
Duke Schillaci, founding partner of corporate development at Elevation Point, said the clearest warning sign isn't found on the P&L — it's in the client list. His read on the data tracks with recent survey findings showing a growing share of RIA leaders now call succession a critical risk to their firms' long-term stability.
"When the client base is aging in lockstep with the advisor, with no meaningful new households under 50 in five years, it's pretty evident the founder has stopped building a business and started running out the clock," Schillaci said. "That's usually visible years before anyone says the word retirement."
A simple test, Schillaci said, is asking a client who they'd call if their advisor didn't pick up. "If the honest answer is, 'I don't know,' you've found the problem," he said, pointing to other signs that often travel together: no next-generation advisor under 40 with a real path to equity, no continuity agreement, and every dollar above overhead paid out as distributions rather than left for a successor to borrow against.
Clients absorb the consequences first because they have the least control, Schillaci said. If an advisor dies or becomes incapacitated with no plan in place, no one may be positioned to take responsibility for client relationships, trading, custodial matters, or the firm's regulatory obligations. It's a gap the SEC itself flagged nearly a decade ago when it proposed — but never finalized — a rule that would have required RIAs to adopt formal, written business continuity and transition plans; today, firms are held to that standard only indirectly, through the SEC's existing compliance-policy rule. "Clients have to rebuild a relationship that took years to establish, usually with someone they didn't choose, and the clients who've been there longest have the most history to re-explain," Schillaci said. "Some go find a new advisor. Others simply drift."
Schillaci said the first practical step isn't a valuation — it's signing a continuity agreement naming a specific firm, partner, or next-generation advisor who can step in if something happens, then telling clients the plan exists. A minority partner can also help fund an internal successor and stage a founder's liquidity over time, he said, letting the founder retain control while clients keep working with people they already know.
Kevin Thompson, founder and CEO of 9i Capital Group, said a lack of repeatable processes is often the earliest sign of trouble. "Recruiting, or the lack thereof, is another sign," Thompson said. "Many older advisors are happy to stay in the seat as long as they can, operating with a handful of clients. At that point, it has become more of a lifestyle business."
Without a plan, Thompson said, clients of an exiting solo advisor can become "chum in the ocean" — divided among other advisors at a broker-dealer or, if they don't generate enough revenue, pushed to a service hotline instead of a dedicated relationship. Staff face similar uncertainty over jobs and compensation.
Thompson's advice to advisors who haven't started: build processes that don't run through one person, invest in real technology instead of personal spreadsheets, and move away from commission-based revenue toward a recurring model that commands a higher multiple. Some firms are already responding to that gap — AssetMark, for one, recently rolled out a multi-stage training program built specifically for succession-minded advisors at every career stage. "Succession planning is not just about finding someone to buy the business," Thompson said. "It is about building a business that someone would actually want to buy."
About 50% of Mercer’s net new assets in the first half of 2026 came through custodian referral programs, as CEO Dave Welling says the RIA is “adding over a billion dollars every month of new clients hiring Mercer as their advisor.”
Advisor Services drew $120 billion in new assets as Schwab plugged into Claude and applied safeguards blocking unauthorized AI agents.
Headed by former InvestCloud, Envestnet and Microsoft executives, Singularity takes ownership positions in established advisory firms as growth strains in-house operations.
Somerville-based firm departs LPL to gain planning resources and technology it says would have taken years to build independently.
The fee promotion runs through 2028 as hundreds of RIAs custody with Fidelity below its new $100 million asset minimum
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

