
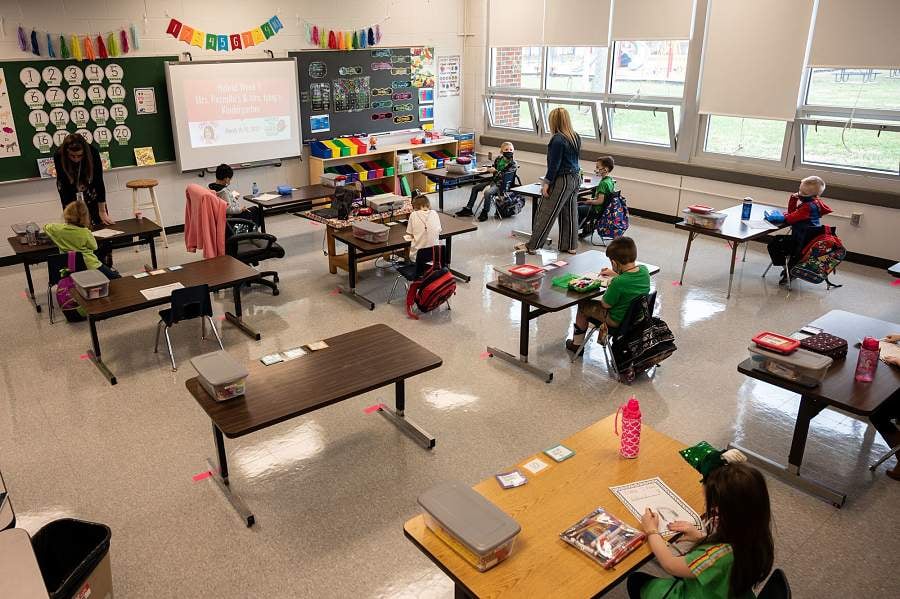
Dan Otter was wrapping up a day of teaching elementary school students more than 20 years ago when a sales rep walked into his classroom.
He didn’t buy what the rep was selling, but that conversation led him on a path to 403(b) education evangelism, and ultimately a major career change.
“I politely listened but didn’t sign up,” Otter said. “She was selling high-cost annuity products, and this was rampant in the K-12 world, nationwide.”
He read up on investing and retirement saving, providing in-house amateur counsel for fellow teachers who were similarly approached by sales agents. In 2000, he started a site, 403bwise, extending his reach to anyone who would listen.
But when it comes to non-ERISA 403(b) plans, that was a drop in the bucket. Public information about those plans is severely lacking, and most of them have unwieldy vendor lists and a glut of costly, ill-fitting investment options for educators. Compared with 401(k)s and their 403(b) cousins that must comply with the Employee Retirement Income Security Act, non-ERISA plans are still the Wild West of retirement saving.
In 2019, Otter left his teaching job and went full-time with 403bwise when the site became a nonprofit and a single donor, Next Gen Personal Finance founder Tim Ranzetta, provided funding. Previously, the site had been funded through advertising from companies like T. Rowe, Fidelity and TIAA.
Late last year, Otter and his part-time 403bwise partner Scott Dauenhauer, owner of Meridian Wealth Management, added a new feature to the site: a database and grading system for those plans.
“It’s a tall task,” Otter said. “There are 14,500 school districts.”
So far, they’ve compiled data for about 4,500 districts and have doled out grades for about 500, adding roughly 25 new districts a day. Nearly all of them have a grade of C or lower — there are just 13 A’s and three B’s, Otter said.
403bwise also uses a traffic-light rating system for plans. For example, a plan that includes commission-based products or uses sales agents automatically gets a red light. One having products without surrender charges but still somewhat high fees might get a yellow light. And a plan with a good list of diversified and low-cost investment options is likely to get a green light.
If a school district only has red-light plans, that district would get an F, Dauenhauer said.
“You get an A if you’ve done a thoughtful process of bidding your plan and you have a good cost structure,” he said. “We want our grades to be aspirational. We want school districts to have an A. We want them to go through the process of going single-vendor in a thoughtful way.”
They point to Maryland’s Montgomery County Public Schools system as a shining example. That district has just one vendor for its 403(b) and 457 plans — Fidelity Investments. The district hired a consultant to select the investment lineup, and products have no surrender charges.
“If every district was single-vendor, it would really make this easier,” Otter said. “We’re in a messy environment. It’s different across the country — California and Texas tend to have the biggest vendor lists.”
They have been scraping data from third-party administrators for the massive undertaking. They’re also been asking teachers who don’t see their district’s data on the site to add vendor lists and request 403bwise to rate it.
“I’ll admit this — we want to shame some of these school districts,” encouraging them to improve, Otter said.
403bwise has information and videos for teachers, and they can request free online presentations.
“Teachers are not taught about the 403(b) before they go into the classroom. Typically, the way you hear about it is through a sales pitch,” Otter said. “The problem is that they are not getting unbiased education.”
Dauenhauer, who runs his advisory practice full-time, had a similar introduction to the murky world of non-ERISA 403(b)s.
“My wife started teaching 24 years ago, and right at the beginning, somebody walked into her classroom and said, ‘I was sent by the California State retirement system,’” he said. However, that person was actually a sales rep, who was promising 8% to 12% annual returns on indexed annuities with 18-year surrender periods and early surrender charges of about 20%, Dauenhauer said. “He was just there to sell my wife an indexed annuity.”
The $100B-plus mega-RIA is folding custom portfolios, daily tax-loss harvesting and unified managed accounts into its Aspen advisor tech platform
From using projects as strategic thinking exercises to real-world challenges as problem-solving exercises, indie firms can make for more powerful talent incubators.

New BCG research names financial services among the world's most AI-exposed industries and the US as a top-tier AI economy.
Rockefeller Capital Management's Mallory Findley on how avoiding conversations risks derailing even the best-laid estate plans.

New Empower research reveals a "retirement drift" problem that hands financial advisors a direct opening to add client value.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

