
Heading into 2026, the so-called “Magnificent Seven” stocks still make up around a third of the S&P 500’s market capitalization, despite an uneven performance in 2025.
That concentration risk is starting to unnerve some advisors, who are adjusting their portfolios to protect against it.
In 2025, the average return for members of the "Magnificent Seven," an informal term for the septet of mega-cap tech stocks that dominate the S&P 500, was around 27.5%, well ahead of the S&P 500's return of approximately 16%. In terms of individual performers, Alphabet led the pack, returning around 66%, while Amazon was the lowest at approximately 6%.
* Alphabet (TICKER: GOOG, GOOGL), up 66% in 2025, 5.6% of S&P 500.
* Amazon (TICKER: AMZN), up 6% in 2025, 3.8% of S&P 500.
* Apple (TICKER: AAPL), up 9% in 2025, 6.8% of S&P 500.
* Meta Platforms (TICKER: META), up 13% in 2025, 2.4% of S&P 500.
* Microsoft (TICKER: MSFT), up 15% in 2025, 6.1% of S&P 500.
* Nvidia (TICKER: NVDA), up 40% in 2025, 7.7% of S&P 500.
* Tesla (TICKER: TSLA), up 20% in 2025, 2.6% of S&P 500.
Read next: 12 most profitable businesses for long-term investors
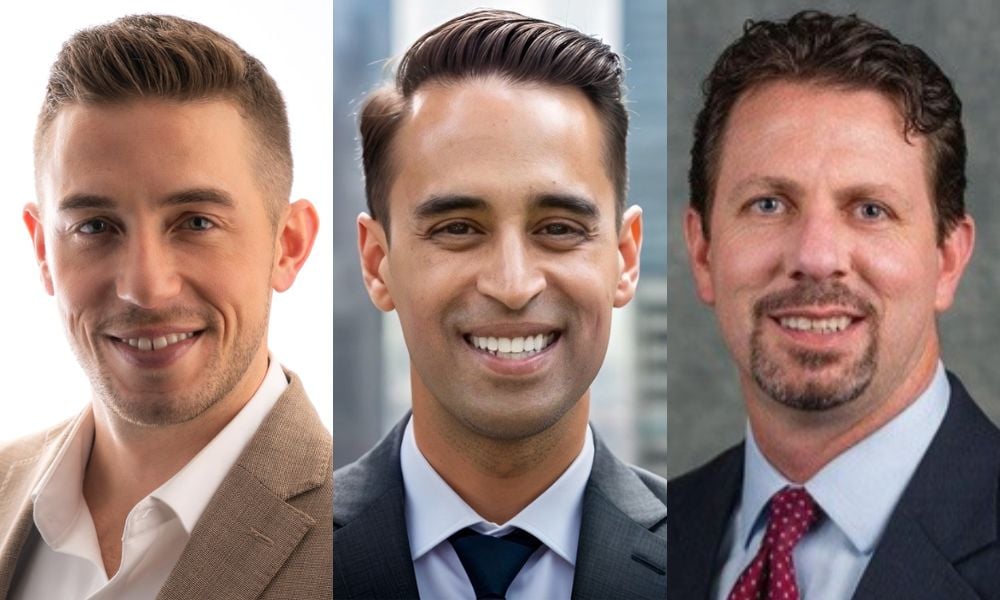
Anshul Sharma, chief investment officer at Savvy Wealth, says he is “mindful of concentration risk” as the Magnificent Seven continue to dominate index-level returns. His approach is not to avoid the group, but to “right-size exposure” deliberately so participation in secular growth doesn’t come with unintended portfolio risk. In addition to diversifying across styles, regions, and return drivers, he also uses options-based overlays selectively to help manage downside risk in portfolios.
“We’re underwriting more moderate returns and higher volatility for the Mag 7 in 2026 compared to the past few years. While these remain high-quality companies, valuation starting points suggest returns are less likely to be linear. That expectation reinforces the need to broaden equity exposure beyond a narrow group of mega-cap names,” Sharma said.
Likewise, Brian Storey, senior vice president for multi-asset strategies at Brinker Capital Investments, says he is becoming more concerned about concentration risk within the US equity market as a result of the growing exposure in cap-weighted indices to the Magnificent 7. He says his concern, however, is mitigated to some extent by the strong relative earnings contribution of the Mag 7 and the increasing heterogeneity in performance among the Mag 7 stocks.
“We believe the Mag 7 can continue to deliver solid returns in 2026, but we think they will be relatively in line with the returns of broader US large-cap stocks. Because of the greater concentration of US large-cap stocks in the Mag 7—and our diminished relative return expectations for this mega-cap growth cohort—we expect to modestly decrease our allocation to Mag 7 stocks in 2026 while increasing our allocation to US small-cap stocks, international equities, and real assets,” Storey said.
Along similar lines, Matthew Smart, director of financial planning and portfolio analysis at WWM Investments, believes concentration risk in the U.S. equity market is a “legitimate concern” heading into 2026, even though he has a high level of conviction in many of the Magnificent 7 companies as individual businesses.
“In 2025, roughly 42 percent of the S&P 500’s total return came from the Magnificent Seven, with the group delivering returns in the high-20 percent range versus a high-teens return for the broader index. That kind of concentration can mask what’s happening underneath the surface, and it can amplify drawdowns if leadership narrows further or sentiment shifts. Given that backdrop, we are being a bit more active and selective in 2026,” Smart said.
As a result, Smart said he is taking some profits in names that have already had exceptional runs, like Alphabet and Nvidia, and reallocating toward areas where he sees more attractive pricing and better forward-looking risk-reward, including outside of the largest mega caps.
Stressed Smart: “We do not build portfolios on the assumption that the Magnificent Seven will simply repeat the outsized returns of the last cycle.”
SAFEST WAYS TO OWN MAG 7
For clients seeking Mag 7 exposure in 2026, Savvy Wealth’s Sharma says he prefers a strategy of structured diversification rather than holding concentrated single-stock positions.
“For clients seeking exposure to the AI buildout, we favor diversified thematic or infrastructure-oriented strategies that capture adoption across the ecosystem rather than relying on a handful of mega-cap names. The mix ultimately varies by risk profile and time horizon, but diversification remains the anchor,” Sharma said.
Brinker’s Storey, meanwhile, says the current concentrated environment for large-cap growth stocks and the diverging business models and returns he is seeing among the Mag 7 companies is making active management among large-cap growth stocks even more critical to delivering attractive risk-adjusted returns and minimizing the potential for outsized surprises in client portfolios.
Finally, WWM’s Smart says he typically uses the power of different indexing approaches to gain exposure to the broad market in a tax-efficient and risk-aware way. That allows him to own the index while being thoughtful about tax management, concentration, and how each sleeve fits into a client’s broader investment plan.
“The tradeoff with pure index exposure is that you also inherit the index’s concentration, which is exactly why we often pair a core index allocation with additional sleeves that diversify style, sector, and factor exposure. That structure allows clients to participate in market growth without letting a single group of stocks dominate portfolio behavior,” Smart said.
Texas securities regulators initially accused Lasater RE Fund of fraud in June but later dropped those claims.
Cornerstone Advisors and Clear Pointe Wealth Management mark an unusual double-team addition for LPL as recruiting run extends in Utah.
Investors were promised guaranteed returns from mobile homes that never existed
The Osaic-acquired broker-dealer failed to catch reps steering 295 clients into costly early UIT sales, regulator finds.
Rick Hu of Midas Wealth breaks down the fee-based planning shift that transformed his advisory practice and reshaped client relationships
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor
Northern Trust’s Ken Lassner shows advisors how to convert volatility into after-tax portfolio gains

