
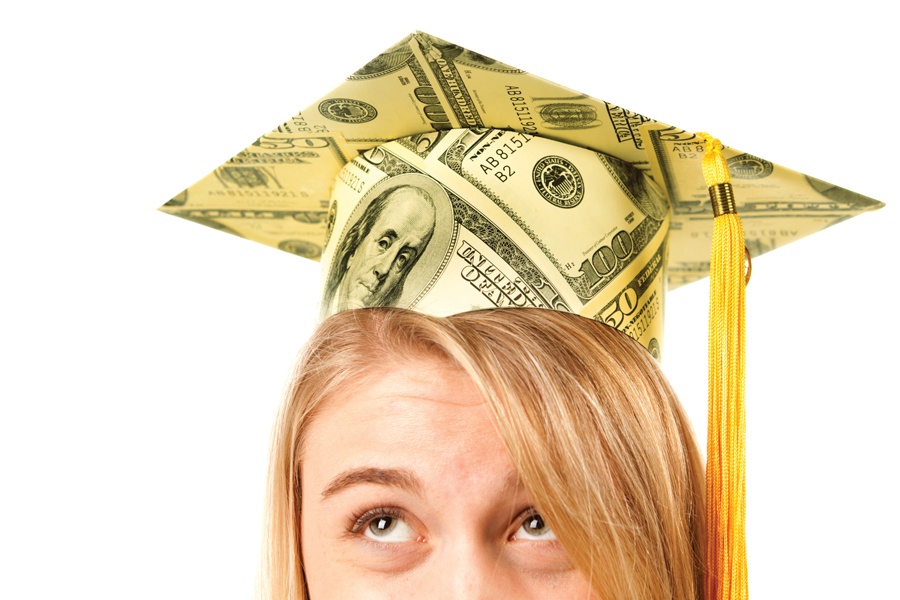
Grandparents who want to help pay for grandchildren's college costs are getting more bang for their buck.
Recent changes to financial aid rules mean they’ll soon be able to contribute to 529 college savings plans that they own without penalizing their grandchild’s eligibility for federal money, a limitation that’s made some grandparents think twice before opening new accounts or adding to existing ones.
“The fear that a grandparent helping their grandchild by using their own 529 plan would interfere with them getting financial aid, that worry is gone now with the new rules,” said Stuart Siegel, president of college financial aid service FAFSAssist.
The change is part of an overhaul of the Free Application for Federal Student Aid, or FAFSA, that students and their families fill out when applying for financial assistance. Its length and complexity have been blamed for deterring people from even seeking aid, spurring Congress to streamline the process through the FAFSA Simplification Act.
Currently, money distributed to students from grandparent-owned 529 accounts effectively reduces the recipient’s eligibility for federal financial aid by 50% of the amount withdrawn for the student. That’s because the current FAFSA asks students to report how much they receive from nonparent sources, and then adds half that gift to what’s known as the Expected Family Contribution. That amount is then deducted from a student’s overall federal aid eligibility.
That’s changing under the new rules, which take effect in the 2024-25 school year. Among the questions being removed from the simplified FAFSA is one about outside contributions. Grandparents, as well as godparents, aunts, uncles and other nonparent family members, will be able to contribute as much as they want into their own 529 accounts without the student being required to report any funds that are later withdrawn.
State-run 529 plans are a popular way to pay for college because of their tax benefits: Participants don’t have to pay taxes on gains or withdrawals as long as the money is used for college or certain other education expenses. They can also be used to defray K-12 costs or, since 2019, student loan repayments.
The total value of 529 plans reached a record $480 billion in the fourth quarter of 2021, up from $165 billion a decade ago, according to Federal Reserve data. Some 37% of families with kids in college used 529 plans in 2020, with the average account holding $25,664.
Parents are the biggest contributors to 529 plans, but grandparents are often the second-largest. In North Carolina, 16% of accounts overseen by the state’s NC 529 Plan are owned by grandparents.
“This is a big deal,” said Laura Morgan, a vice president at the College Foundation of North Carolina, a nonprofit that administers the state’s 529 plan accounts. “The rising cost of education has made paying for college a family effort, and this opens the door for more grandparents and other nonparents to own and manage 529 accounts.”
While many wealthy families either don’t apply or aren’t eligible for financial aid, the simplified FAFSA could be a boon to low- and middle-income students. The current form is so dense with questions about assets and income that many families never even bother to fill it out. More than $3.7 billion of free money was left on the table last year by families eligible for aid, according to a recent study.
Richard Thigpen, who has two grandchildren in the sixth grade, is already preparing to help with their college. He’s saved about $10,000 for each in a 529 plan and looks forward to the change involving outside contributions taking effect.
“It’s been great,” he said. “This is something meaningful we can do.”
The $100B-plus mega-RIA is folding custom portfolios, daily tax-loss harvesting and unified managed accounts into its Aspen advisor tech platform
From using projects as strategic thinking exercises to real-world challenges as problem-solving exercises, indie firms can make for more powerful talent incubators.

New BCG research names financial services among the world's most AI-exposed industries and the US as a top-tier AI economy.
Rockefeller Capital Management's Mallory Findley on how avoiding conversations risks derailing even the best-laid estate plans.

New Empower research reveals a "retirement drift" problem that hands financial advisors a direct opening to add client value.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

