There were two recurring themes at the annual
InvestmentNews Retirement Income Summit in Chicago earlier this month: the economic impact of increased longevity and the need for guaranteed income in retirement.
Retirement has traditionally been described as a long-term investment goal. That's true for the accumulation phase. But as clients near the retirement-distribution phase,
financial planning needs to shift to risk management and capital preservation.
Retiring during the longest-running bull market in history can be scary for new retirees and soon-to-be retirees, who wonder when the good times will end and how they can protect their retirement savings if they do.
The stakes are especially high with the senior population growing larger by the day. One American turns 73 every seven seconds, and that startling statistic will forever change retirement planning, said Joseph Coughlin, founder and director of the Massachusetts Institute of Technology AgeLab.
Correction overdue?
The last
bear market ended more than 10 years ago, in March 2009. Some warn that a correction is overdue. Drawing down assets in a down market during the early years of retirement is one of the biggest risks to portfolio longevity, known as the sequence-of-returns risk. When the market recovers, the portfolio may not have as much room to run because it's been depleted by ongoing withdrawals.
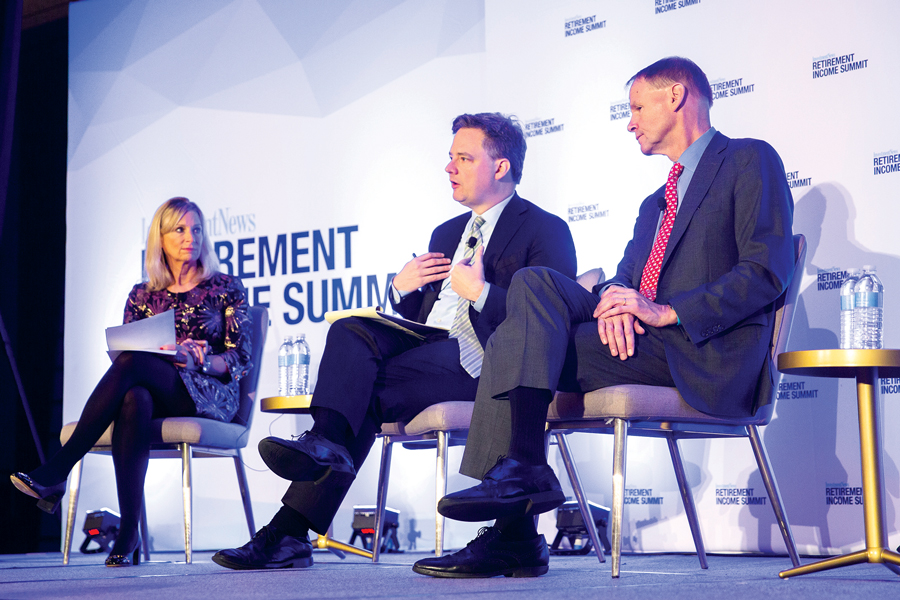
During the kickoff session May 14, Mark Wiedman, senior managing director of
BlackRock Inc., and William "Ted" Truscott, CEO of Columbia Threadneedle Investments, discussed how continued low interest rates and low inflation, coupled with high stock valuations, are creating investing challenges for both advisers and their retired clients.
"Savers are being punished for being savers," Mr. Weidman said.
"Generating money in retirement is going to be even more challenging if the market drops, and advisers will need an adaptive withdrawal strategy," Mr. Truscott said.
(More: Dealing with widows requires empathy and patience)
Given that Mr. Weidman speaks on behalf of a global investment firm with more than $6.5 trillion in assets under management, it was a bit surprising to hear him ask rhetorically, "Why isn't there a bigger annuity market in the U.S.? It is the missing piece of the retirement income puzzle."
And one that only insurance companies, with their ability to pool risk and boost payouts through mortality credits, are equipped to solve.
The theme of "the need for guaranteed income in retirement" continued throughout the two-day annual conference in Chicago, as experts discussed the potential peril for retirees and those approaching retirement if the stock market drops at the beginning of their retirement.
"What is your strategy to defend against sequence-of-return risk?" said Michael Kitces, partner and director of planning research at Pinnacle Advisory Group. "From a financial planning perspective, these are the times that actually matter."
Wade Pfau, professor at The American College of Financial Services and director of retirement research for McLean Asset Management and inStream, agreed. He noted that the traditional 4% withdrawal rule may not be an appropriate way to manage the dual challenges of longevity and market risk.
"We've never had the high valuations and the low interest rates at the same time," he said. "We are in uncharted waters."
Four options
There are four ways to manage sequence-of-return risk, Mr. Pfau said. Advisers could recommend a more conservative drawdown strategy than the traditional 4% rule of thumb. Or they could adapt a more dynamic strategy by increasing or reducing spending to reflect markets' ups and downs.
(Podcast: Will gray divorce ruin my retirement?)
Another option is to create buffer assets through a reverse mortgage line of credit or cash value life insurance. Finally, advisers can attempt to control volatility in a retirement income plan by using some assets to purchase either an immediate or deferred annuity.
In recent research conducted for the Alliance for Lifetime Income, Mr. Pfau found that adding an income annuity to a retirement portfolio allows a retiree to get the same or higher income with lower risk of outliving savings than an investments-only approach.
Confidence boost
And in related research conducted on behalf of
Principal Financial Group, Mr. Pfau and Michael Finke, chief academic officer at The American College, found that using guaranteed income annuities cannot only improve financial outcomes but increases confidence and reduces stress in retirement.
Knowing that they have guaranteed income for life gives retirees permission to spend their savings and enjoy their retirement — in contrast to trends showing that many retirees are underspending — and increases their ability to leave a legacy to their family or favorite charities.