
A 60/40 portfolio — one that buffers the volatility of equities with the stability of bonds — hasn’t done too well lately, so we're hearing about “the death of 60/40." No, what’s going on is more like, “Now you know what 60/40 really looks like.”
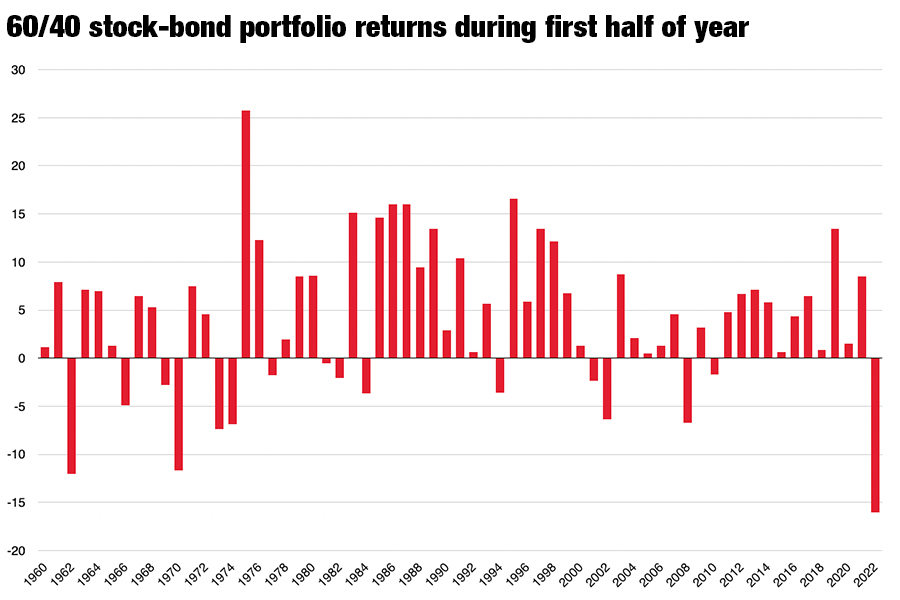
As the figure shows, year to date the 60/40 portfolio has posted its worst performance in over 60 years. The S&P 500 is down 20% so far this year, the worst since the 1970s, and the Barclays Aggregate Bond Index is down 16%, the worst first-half performance since the index started in the early 1980s. Put the two together, and this is what you get.
To make matters worse, the historically bad results are broad-based; it’s not just equities and bonds, but both high-cap and low-cap equities, Treasuries and corporates. (Actually, value hasn’t fared that badly, at least when compared to growth. That’s no surprise, given the notably bad performance of the Nasdaq.)
Equities, of course, are risky. Their risk is mostly tied to the discounting of future earnings. Bonds are also risky. Their risk is tied to rates and credit. There’s no law that prohibits earnings to be revalued and rates to rise at the same time. There are reasonable scenarios in which corporate bonds can drop over 20% — as can "riskless" Treasuries. There are reasonable scenarios where credit spreads can go up 400 basis points — even 700 or 800 basis points.
I’ve written recently about the risk entailed in holding bonds in 60/40. There might be consternation, but there should be no surprise that when we put a very bad run of equities with a very bad run of bonds, we see the sort of performance we’ve had over the past six months.
So is this “the death of 60/40"? No, 60/40 does what it is supposed to do. It just isn’t doing what we want it to do.
What we want it to do is not only dampen risk, but give us some sort of buffer that’s focused on the downside, to be sure to keep some powder dry.
To do that, you can:
1. Put some of your portfolio into cash, not into bonds.
2. Use a structured product to create an income stream that is not rate-sensitive. Or
3. Peg bonds to cash flow needs, for example, by creating a duration-matching portfolio. Then the mark-to-market swings won’t matter relative to liabilities.
What do you get with 60/40? You generally dial down your portfolio’s volatility, because bonds almost always are less volatile than stocks. All you're getting is some diversification when you move out of equities into rates and credit.
Note that I'm saying some — of course they are correlated, but to make matters a bit more difficult, the correlation between rates and stocks is sometimes negative, sometimes positive, and sometimes hardly there at all.
Rick Bookstaber is co-founder and head of risk at Fabric. He previously held chief risk officer roles at Morgan Stanley, Salomon Brothers, Bridgewater Associates and the University of California Regents, and served at the Treasury in the aftermath of the 2008 financial crisis. He’s the author of “The End of Theory” (Princeton, 2017) and “A Demon of Our Own Design.”

Meanwhile, DPL Financial Partners adds two annuity executives and Prime Capital Financial hires a Mid-Atlantic retirement plan consultant

Andrew Komarow pleaded guilty Thursday in federal court in Hartford to defrauding three financial services companies of close to $3.3 million.

Elsewhere, Cetera picks up a $210 million Connecticut team from MML, while Wells Fargo FiNet adds a San Diego family practice from LPL

Celebrity endorsements, $500M in claimed assets, and a state regulator stepping in.

“We needed to become a more agile and efficient organization,” said American Express CEO Stephen Squeri.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

