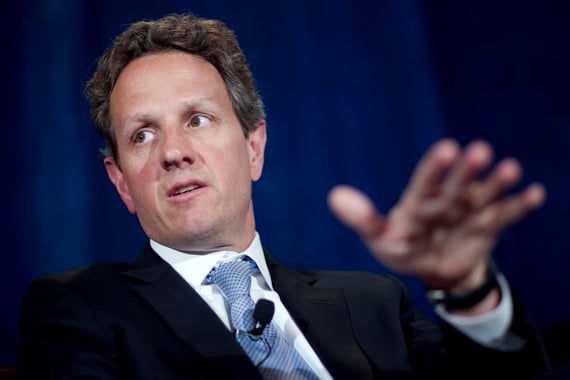
Treasury Secretary addresses issue of whether funds are too big too fail; well, are they or aren't they?
Based on what Treasury Secretary Timothy Geithner said yesterday, it seems pretty unlikely that all mutual funds are going to be designated as systemically important financial institutions under Dodd-Frank.
In a question and answer session at the Investment Company Institute's Annual General Membership Meeting Wednesday, Paul Schott Stevens, president and CEO of the ICI, asked the Treasury Secretary whether he is considering a broad or narrow definition of what a systemically important financial institution should be.
In response, Mr. Geithner said the debate shouldn't be about how broad or narrow the designation is. “It should be about whether an institution can have the same inherent risk that comes with borrowing short so you can invest long term in a size that matters.”
Specifically, Mr. Geithner wants to make sure that institutions that are acting as investment banks — through the use of leverage — are regulated as such.
What Mr. Geithner wants is very important to the mutual fund business. Under the Dodd-Frank legislation, Congress created the Financial Stability Oversight Council, a group of financial regulators to identify institutions that potentially could destabilize markets. The FSOC is expected to designate which institutions — both banks and, importantly non-banks — could pose substantial risk to the system by year-end.
Mr. Geithner is chair of that council.
The mutual fund industry has been fighting to keep itself out of the FSOC's sights, claiming that the funds don't inherently pose the same kinds of liquidity challenges to the system that other institutions do.
At yesterday's gathering, Mr. Geithner seemed to assuage those fears. He noted that establishing a broad designation could pose problems. For example, the FSOC wants to make sure it has a system in place which prevents a company from operating as a bank one day, and then flipping their charter to become a thrift simply to avoid regulation. “This is not something you can lock in and never change," he said, "because the market will adapt."