
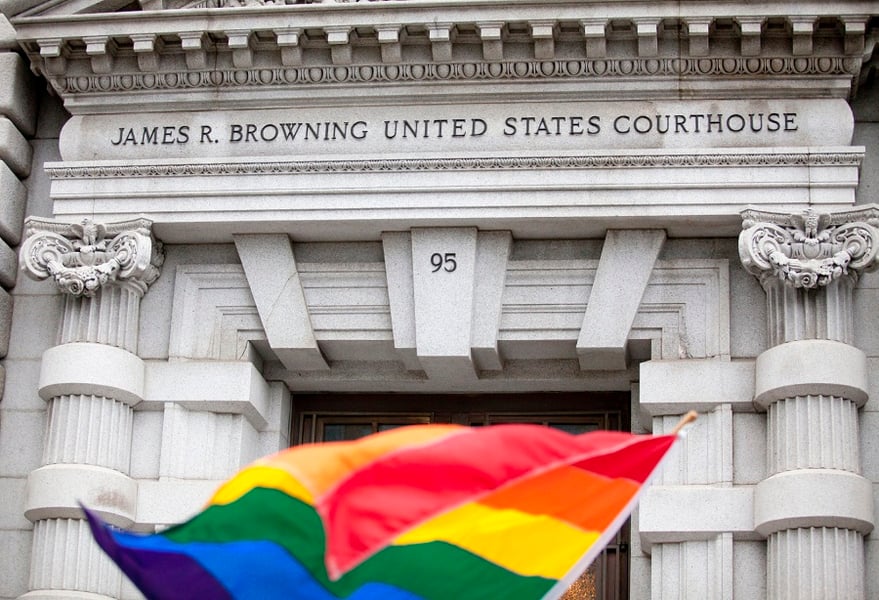
While it’s true that many advisers can counsel LGBTQ+ clients and their families on important matters such as estate planning, health care proxies and even second-parent adoption documents, advisers who identify as LGBTQ+ and who have life experiences compatible with the unique needs of the community can draw from that experience, positioning clients for the consistently shifting legal headwinds.
John Shedd wrote in 1928: “A ship in harbor is safe, but that is not what ships are built for.” Shedd’s sentiment is especially applicable to LGBTQ+ estate planning. Sure, an estate plan looks great when LGBTQ rights arem't being hotly debated, but it would be unwise to assume that the seas will always remain calm. That said, your estate plan needs to withstand the challenges of what appears to be an ever-changing political landscape.
We have experienced these scenarios first-hand and understand how deeply personal it can become when piecing together the appropriate tools available to secure our financial futures, against a backdrop of a system that was clearly not designed with our community in mind.
Offering the LGBTQ+ community sound financial advice means going far beyond external appearances of being "welcoming and accepting" and having a documented corporate diversity and inclusion policy. It requires combining real world experiences, competencies and empathy to create and execute a solid financial plan, based on the unique circumstances each client faces, while creating a specialty practice that speaks to the need for a very distinctive set of resources and understanding.
To further understand the unique capabilities LGBTQ+ advisers can offer, let’s take the decision to start a family. Both heterosexual and LGBTQ+ couples face a litany of financial planning considerations when having children, such as budgeting, health care, taxes and saving for college, to name a few. However, unlike historically traditional couples, it is imperative to consider state law as it pertains to health care and legal protections for the family. Not to mention the potentially significant medical and legal costs that can often eclipse the planning of traditional families.
As advisers, it is our fiduciary responsibility to bring these unique planning considerations to light. Consider the following: What happens if your spouse who gave birth to your child dies, do you automatically gain custody? Do you need second-parent adoption documentation?
What about the year you were married? If the marriage occurred prior to 2015 and the couple separates, how does their status impact the division of assets? How should you file your taxes, married filing jointly? Does your spouse’s health care cover you?
The United States is becoming more like Europe, with its different laws from country to country, but varying state to state in the U.S. With the Supreme Court’s decision to overturn the five-decade-old Roe v. Wade decision, hard-fought rights can disappear overnight. The ripple effect of these decisions can have greater consequences for a gay couple that has not taken the steps to protect their family and their wealth. You run the risk of not being able to make decisions about what happens to your children or money if something happens to you or your partner, should you not have the proper documents in place.
We’ve heard the cliché applied to other facets of life that require specialization, but it’s never been more applicable than for LGBTQ+ clients seeking an adviser.
The community requires more than appropriate investment recommendations and risk assessments. We believe they need advisers whose life experiences mirror their own. Someone who has their finger on the pulse of societal shifts and how politics and legislation might impact the LGBTQ+ community personally, professionally and financially.
Barbara Bilello is a partner and wealth adviser with RegentAtlantic Private Wealth. Lisa M. Neira is a wealth adviser with RegentAtlantic Private Wealth.

DeepVest, Asset-Map and Aidentified launch automation that spots household gaps, wealth events and portfolio triggers for advisor sign-off
Eddie Brown says RIA executives need AI built for strategy and execution, not just advisor productivity
Independent advisors in Colorado, Texas and Arkansas join larger wealth management platforms through acquisitions and partnerships
The enforcement division wanted a full bar - the Commission went lighter
Welch brothers’ 93 Financial Group gives the Osaic-owned RIA a fifth greater Boston office, days after a $1.6B triple acquisition
Advisors are broadening the conversation beyond savings to help clients prepare for the realities of longer lives
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.

