
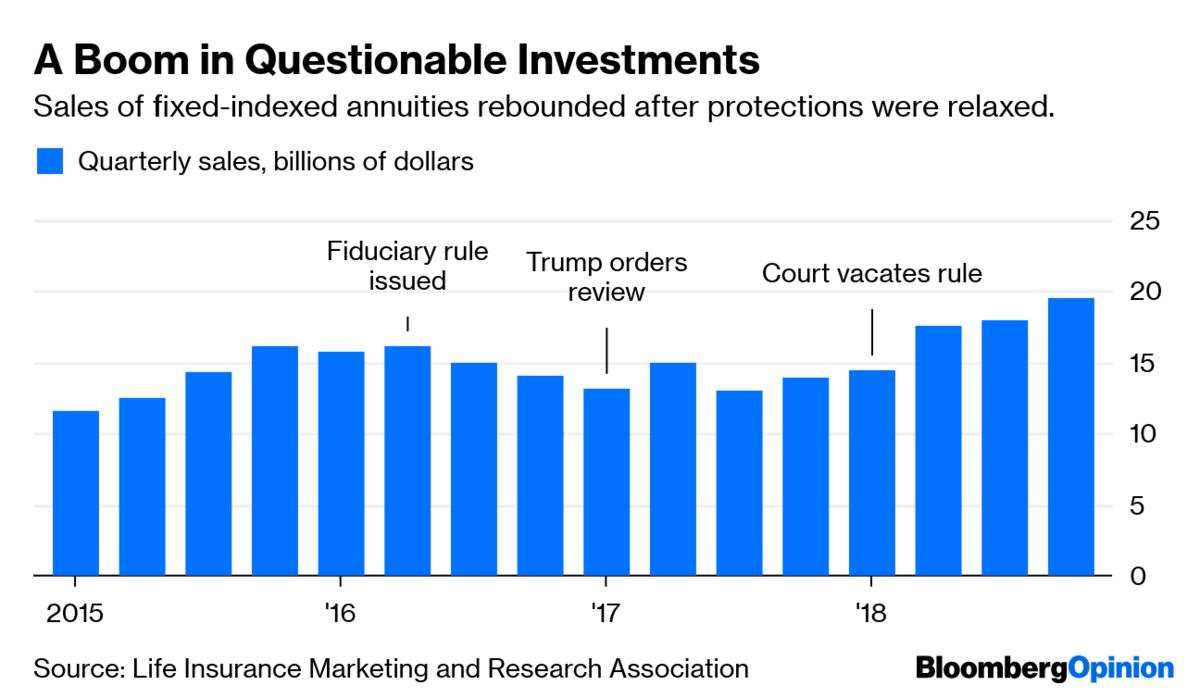
 In New York state, which has unilaterally adopted aspects of the fiduciary rule, far fewer insurers sell such products.
How much do savers stand to lose? Consider one product that a major insurance company marketed to me: a 10-year annuity linked to the S&P 500 Index. Based on this annuity's formula and the price at which it was offered, a client would have foregone on average an estimated $54,000 in profit per $100,000 invested over any 10-year period going back to 1989. That's compared with a simple combination of U.S. Treasury bills and S&P 500 index funds that offers the same downside protection as the annuity with less credit risk and more liquidity.
The marketing materials an agent sent me seemed to play on fear, showing a potentially faulty comparison of the annuity's returns to the loss a pure stock position would have suffered during the 2008-09 crash. And the materials did not highlight crucial information such as hefty withdrawal fees and the insurance company's right to reduce payouts.
Such products are just the tip of the iceberg. Every year insurers come out with an array of new annuities employing "black box" strategies that are all but impossible for outsiders to understand. One could be forgiven for suspecting that some such strategies have been tweaked to make it difficult for a lay person to accurately assess their return potential.
(More: 5th Circuit denies states' second attempt to defend DOL fiduciary rule
No current efforts to improve standards — including one by the National Association of Insurance Commissioners – come close to the protections that the fiduciary rule would have provided. A strong form of the rule should be revived and applied to all investment accounts, not just retirement accounts. To be clear, there are upstanding insurers and agents who sell indexed annuities only when appropriate. Proper regulation wouldn't crimp those sales, but it would prevent over-prescription of such products to people whom they can harm.
Ethan Schwartz has worked as an investment manager and financial services executive for 21 years. He was a special assistant to the deputy secretary of the Treasury in the Clinton administration.

Wells Fargo adds two bank-channel recruits, UBS lands a JPMorgan Chase veteran, and a multi-family office lifts Atlas past $1B

“The state comes down on you in years when you make 40% returns for clients,” said Bill Swayne, the advisor and son of Candace Swayne.

The Independent broker-dealer giant has had “active conversations” with the Claude maker, which is days away from its expected IPO

For Gen X clients entering life after work, answering the financial question isn't enough to solve the entire retirement equation.

Tools from Grantd, Income Lab and Healthspan Wealth aim to keep RIAs involved in clients’ biggest money decisions
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.

