
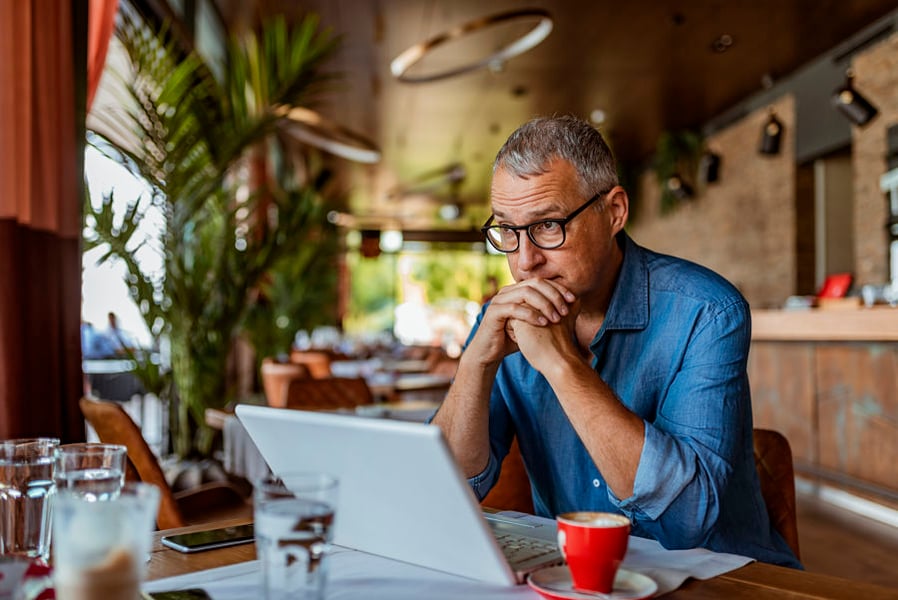
One of the benefits of a career as a financial advisor is that it isn't physically taxing. In fact, I would argue that the older you get, the more rewarding advising becomes. You build great relationships and receive outsized compensation.
While it may be fine for a financial advisor to work well beyond retirement age, clients are only well served if there is a thoughtful succession plan or a younger generation advisor, or G2, in place.
With all the news of M&A and consolidation in our space, it still seems that most aging independent advisors don’t sell their practice or retire. Instead, they simply reduce their workload and “retire in place.” They have a strong administrative person who answers the phones and communicates with clients while the advisor takes off weeks or months at a time.
I see two problems with coasting into retirement without at least a G2 in place: First, clients will not receive the best care and support while the advisor is working part-time. Second, they'll be orphaned when the advisor dies or becomes incapacitated.
From what I have witnessed, many aging advisors milk their client base for as long as they can. They know that their clients don't want to shop around for a new advisor, and they can get away with a mediocre level of advice and response times.
These advisors may believe they're acting in their clients’ best interests but stop and think about how much this profession has changed over the past several years. The fact is that far too many aging advisors are not keeping up with the advances.
Technology enables advisors to do much more than they used to. Financial planning software is robust and can provide some wonderful scenarios to help lead a client to the right decision. There’s great portfolio software that can help educate a client on risks and asset allocation. There are smart-tax trading tools that provide real alpha to a client. There’s direct indexing that can account for tax losses and gifting strategies. There are tax optimization tools that enable an advisor to do what-if scenarios for Roth conversations, planned stock sales, etc. The list is endless.
I am sure there are some half-retired advisors that are on top of the latest tools, but many advisors that I've talked to are far from comfortable using advanced technology. I know of one 70-year-old advisor who does not even use a computer.
Clients deserve better than this.
If you want to continue working well into your retirement years, but not on a full-time basis, do your clients a favor and have a highly competent G2 advisor on your team. This may reduce your income, but it's your duty to act in their best interests, not your own.
If you don't bring in a G2 advisor who can take over your clients when you can no longer assist them, it has been my experience that you and your clients would be better off merging with a larger firm.
Scott Hanson is co-founder of Allworth Financial, formerly Hanson McClain Advisors, a fee-based RIA with approximately $16 billion in AUM.
The Lenexa, Kansas broker-dealer and its 25 advisors managing $2.5 billion will gain expanded technology and product resources

DeepVest, Asset-Map and Aidentified launch automation that spots household gaps, wealth events and portfolio triggers for advisor sign-off.
Eddie Brown says RIA executives need AI built for strategy and execution, not just advisor productivity.
Independent advisors in Colorado, Texas and Arkansas join larger wealth management platforms through acquisitions and partnerships.
The enforcement division wanted a full bar - the Commission went lighter
Advisors are broadening the conversation beyond savings to help clients prepare for the realities of longer lives
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.

