
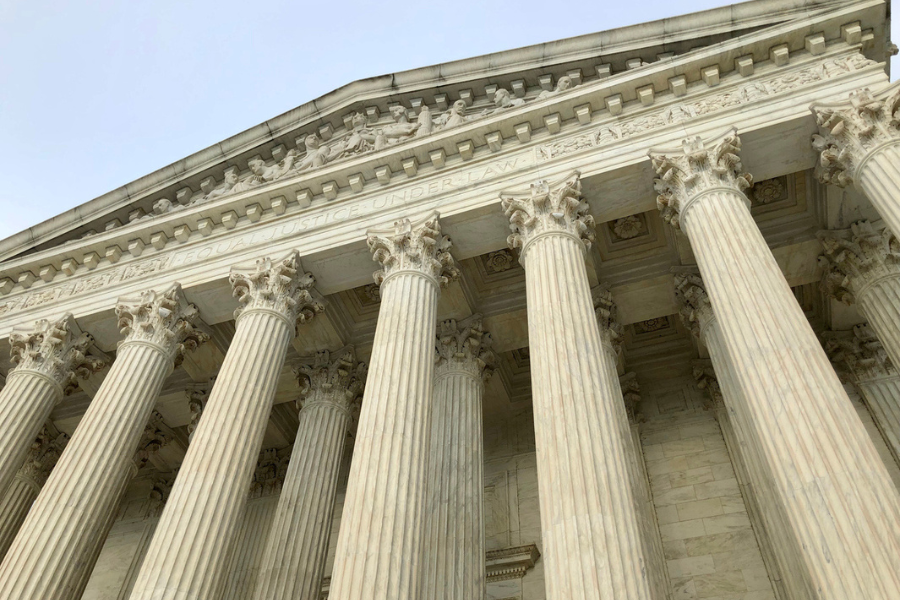
The way that the Consumer Financial Protection Bureau is funded has been ruled constitutional by the U.S. Supreme Court, overturning a previous decision by a lower court.
A lawsuit filed by associations representing the payday loan industry in 2018 which argued that receiving fixed rate funding directly from the Federal Reserve instead of via Congress was a violation of the U.S. Constitution’s separation of powers provisions. This was agreed by the Louisiana appeals court.
But the Supreme Court ruling Thursday means that the CFPB will continue to be funded as it has been since its creation as part of the 2010 Dodds-Frank Act and also avoiding a potential challenge to the funding of the Federal Reserve Board, FDIC, and other entities with similar funding mechanisms.
“Had the lower court’s ruling stood, I can imagine an argument for striking down the mechanism whereby the Federal Reserve gets its funding,” Aziz Huq, professor at the University of Chicago Law School told the FT. “If the CFPB is struck down, that has repercussions in one policy area. If the Federal Reserve is hobbled, that has not just American but global repercussions”.
The original lawsuit followed new rules introduced in 2017 to curb certain practices by high-interest lenders that the CFPB said were unfair. In a statement, the CFPB noted the long-term friction.
“For years, lawbreaking companies and Wall Street lobbyists have been scheming to defund essential consumer protection enforcement. The Supreme Court has rejected their radical theory that would have devastated the American financial markets. The Court repudiated the arguments of the payday loan lobby and made it clear that the CFPB is here to stay.”
The regulator has been trying to reach imprisoned advisor Jason Foley.
Magnificent 7 firm continues to ‘right size’ workforce in AI-related shift also seen in financial services.
Healthcare inflation running at 280% of CPI - and most HSA holders are sitting in cash.
New research identifies the practice habits driving 121% DC AUM growth among the industry's top performers.
Six-figure losses, social media lures and impostor schemes are draining older clients’ savings, report to Congress shows.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

