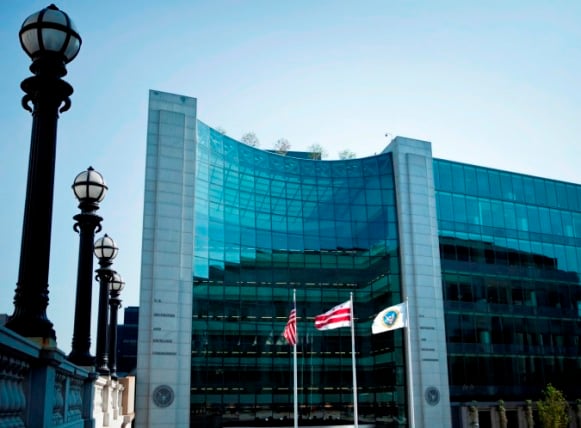
Bipartisan legislation scheduled for introduction on Monday would allow the Securities and Exchange Commission to levy fines on individuals of up to $1 million per securities violation and up to $10 million per violation for financial firms.
Under the bill, the SEC could impose the multi-million dollar fines or charge three times the amount of ill-gotten gains or investor losses, whichever is greater. In addition, the agency could triple the penalty for violators who had been convicted of fraud or received an SEC administrative sanction within the previous five years.
Under current law, SEC civil penalties are capped at $150,000 per offense for individuals and $725,000 per offense for firms.
The bill, written by Sen. Jack Reed, D-R.I., chairman of the Senate Banking Subcommittee on Securities, Insurance and Investment, and Sen. Charles Grassley, R-Iowa, ranking member of the Senate Judiciary Committee, would give the commission more latitude on sanctions. Its penalties for securities violations have been criticized as too weak.
In November, U.S. District Judge Jed Rakoff declined to approve a $285 million settlement between between the SEC and
Citigroup Inc. over a case where the bank allegedly misled investors on $1 billion worth of mortgage-linked securities. Mr. Rakoff asserted that the agreement did not serve the public interests. The case remains on appeal.
Mr. Reed said that his bill is designed to make securities law violations more than just a cost of doing business for financial institutions. “If they look at the bottom line and see they can break the law, get caught, pay a nominal fine and still profit, the cycle of misconduct will continue,” Mr. Reed said in a statement.
Mr. Grassley, who has been a consistent Capitol Hill critic of the SEC, said he wants the agency to use more muscle when cracking down on malfeasance.
“I especially like the increased penalties for repeat offenders in this bill,” Mr. Grassley said in a statement. “That should help change the dynamic of business as usual.”
The authors anticipated introducing the bill late on Monday, when the Senate goes back into session.
It's unclear how far the measure will progress in the current session of Congress, which concludes in December. The number of legislative days is dwindling quickly, with the elections approaching. Any bill that is not signed into law this year would have to be reintroduced in the next congressional session beginning in January.
The bill's authors hope to draw bipartisan support.
“Wall Street fraud threatens our economy and hinders recovery,” Chip Unruh, Mr. Reed's spokesman, wrote in an email. “In order for markets to function properly, principles of basic fairness must apply and illegal behavior must be punished. The SEC will never have the resources to match all the firms on Wall Street, but it must have the tools and authority to hold perpetrators accountable.”
The legislation gives the SEC the punishment latitude called for by agency Chairman Mary Schapiro in a Nov. 28, 2011, letter to Mr. Reid. In fact, the bill contains just about every statutory change to penalty limits that Ms. Schapiro outlined.
“The chairman welcomes efforts to expand our authority to seek monetary penalties for the most serious securities law violations,” Kevin Callahan, an SEC spokesman, said in a statement.
One expert, however, doubts that raising fines will be an effective deterrent to financial fraud.
“It's easy and popular for Congress to say, 'We're going to make these penalties harsher,' but that doesn't address the enforcement problem the SEC is having,” said Ellen Brotman, a partner at Montgomery, McCracken, Walker & Rhoads.
Although the SEC set a record for enforcement actions and fines in 2011, the agency has told Congress it needs more personnel and more financial expertise in enforcement.
“That's an institutional change Congress has to get behind,” Ms. Brotman said. “They have to be serious about giving agencies the money they need, the budget they need, to proactively investigate and prevent fraud before investors are harmed.”