
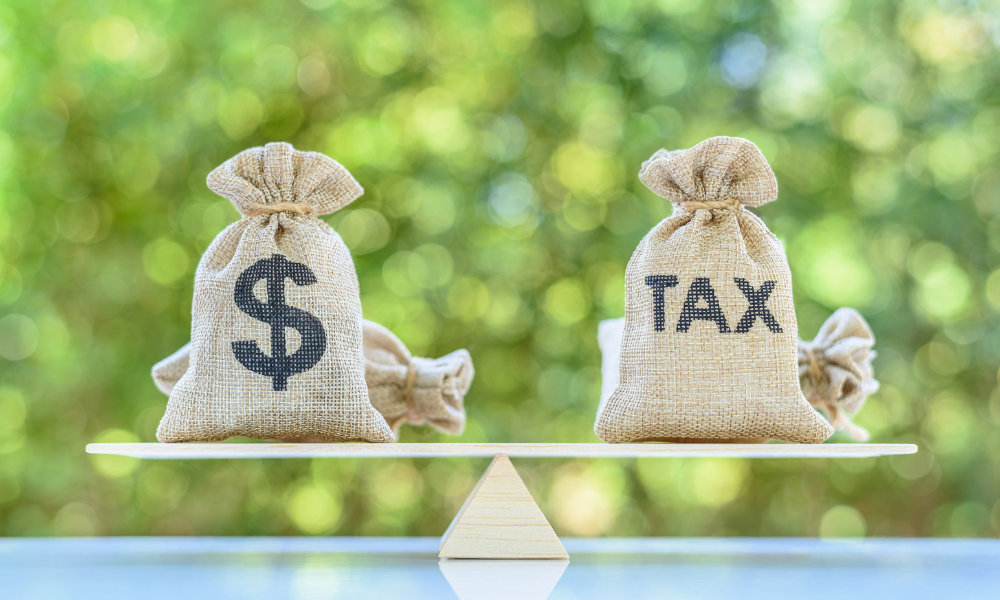
California's first-in-the-nation tax on billionaire wealth was rejected by voters on Monday, ending a bruising ballot campaign that pitted progressive labor unions against a coalition of tech executives, Democratic Party leaders, and an unprecedented wave of opposition spending.
Proposition 40 - the California Billionaire Tax Act - sought to impose a one-time 5% levy on the net assets of state residents worth more than $1 billion.
Backed by SEIU United Healthcare Workers West, the measure was designed to generate an estimated $100 billion over five years to offset deep cuts to Medicaid funding enacted under President Donald Trump's "One Big Beautiful Bill" last year. Ten percent of revenues would have gone toward education and food-assistance programs.
The Associated Press called the race late Monday, with the "no" side leading by roughly 5.5 points after last week's election, in which most California votes are cast by mail and tallied over days.
The defeat marks a significant blow to the progressive wing of the Democratic Party, even as Democrats secured decisive majorities in both chambers of Congress in a sweeping midterm rebuke of the Trump administration. It also hands incoming California Gov. Xavier Becerra a substantial budget problem, with federal healthcare funding cuts looming and no replacement revenue mechanism in place.
The "no" campaign outspent proponents by roughly 10 to one. Google co-founder Sergey Brin alone contributed more than $100 million to Building a Better California, a political action committee that raised more than $333 million in total to defeat the measure. Former Google Chief Executive Eric Schmidt contributed $45.6 million to the same group.
Opponents also placed two companion measures on the ballot - one introducing new audit and spending requirements, another seeking to ban wealth taxes outright in California. The first failed; the second held a narrow lead Monday but had not yet been formally called.
"Proposition 40 was a reckless experiment conducted on our state's economy with little regard for the harms it would cause," the antitax coalition said in a statement.
Advisors serving high-net-worth clients in California had been watching the race closely. The proposal had already prompted residency discussions with wealthy clients, with financial advisors flagging concerns about wealth migration to lower-tax states - a pattern already visible in Washington state, where RIAs reported client "disbelief" following that state's new 9.9% millionaire tax.
The measure exposed a sharp fault line within the Democratic Party. Gov. Gavin Newsom - widely regarded as a probable 2028 presidential candidate - actively opposed the initiative, warning it would undermine California's economic competitiveness and drive entrepreneurs from the state.
His coalition of opponents included Planned Parenthood Affiliates of California, the California Medical Association, the state's largest teachers union, and unions representing firefighters and construction workers.
Vermont Sen. Bernie Sanders held rallies across California in the campaign's final weeks urging passage, while supporters ran ads targeting Newsom in New Hampshire, New Mexico, and Virginia - states with early 2028 Democratic primary votes - framing his opposition as a liability.
Supporters say the defeat is not the end of the road. SEIU United Healthcare Workers West president Dave Regan vowed to return the measure to the ballot in 2028 if Sacramento does not resolve the healthcare funding shortfall in the interim.
"That is our plan," Regan said. "We will build on the coalition that brought us here, we welcome more stakeholders to the process, and we'll put forward a proposal informed by everything that we've learned in this campaign."
The "Yes on 40" campaign struck a defiant tone. "Buying an election is not the same as winning the debate," proponents said in a statement Monday. "The billionaires may have bought themselves a temporary victory at the ballot box, but they have not bought themselves an end to this debate, and this is only round one."
Incoming Senate Finance Committee Chairman Ron Wyden signaled that taxing the ultra-wealthy remains a priority for the broader party. "The committee will redouble its efforts to ensure billionaires pay their fair share and hold tax cheats accountable," Wyden said in a November 4, 2026, statement outlining the panel's priorities.
For financial advisors, the outcome removes an immediate planning pressure but the broader conversation around wealth tax policy is far from resolved. With 2028 on the horizon and federal deficit pressures mounting, advisors working with affluent clients in high-tax states should expect this debate to resurface.
The RIA aggregator adds a New York and Los Angeles firm serving film and TV talent as it deepens its business management bench
Meanwhile, Janney picks up a $280 million Merrill Lynch veteran in Scranton as independent and hybrid platforms keep drawing teams
The breakaway-focused minority investor has staked 15 RIAs since 2024 as private sponsors increasingly trade stakes

Osaic subsidiary continues to forge new routes to US high-net-worth and ultra-high-net-worth people.

New data shows veterans report stronger financial security, legacy confidence and career earnings momentum than non-veterans.
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.

