
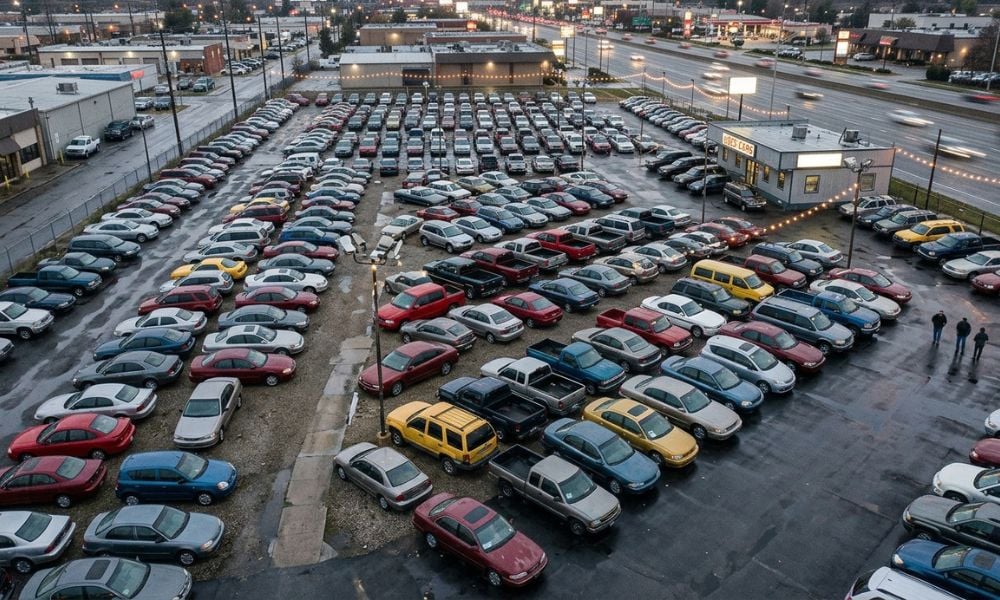
The SEC says three executives at a Texas subprime auto lender misled investors who lost hundreds of millions of dollars on car-loan bonds.
That is the core of a complaint the Securities and Exchange Commission filed on August 19, 2026, in Manhattan federal court against the founder and chief executive, the chief financial officer, and a senior finance director of Tricolor, a used-car seller and subprime lender that went bankrupt last year.
If you buy, structure, or recommend asset-backed securities, this one is worth a read. It shows how far the numbers behind a bond deal can drift from reality before a buyer notices.
The setup was ordinary enough. Tricolor bundled pools of subprime car loans into bonds - notes repaid by the cash those loans throw off - and sold them. The complaint alleges the company raised more than $1.9 billion this way, with financial institutions as buyers and three broker-dealers working as underwriters.
The collateral, the SEC alleges, was not what it seemed. The complaint says the executives leaned on “double-pledging,” its term for promising the same car loan to more than one bond deal or credit line at once. It also alleges the pools were stocked with “dead loans,” the filing’s phrase for loans borrowers had stopped paying, along with fictitious loans built on faked vehicle identification numbers.
Covering the gap allegedly meant doctoring the monthly reports lenders and investors relied on. One text quoted in the filing has the chief financial officer describing a batch of collateral as “garbage, zombie loans which were ineligible anywhere.” The complaint alleges the group even ran an off-the-books entity, “Company 23,” to hold dead loans and dress them up as current.
The SEC says the scheme left roughly $800 million missing from Tricolor’s collateral base. A forensic firm hired by the bankruptcy trustee concluded the company had overstated the collateral behind its loans by at least $675 million, according to the filing.
When lenders flagged odd numbers in mid-2025, the complaint alleges the chief executive floated cover stories - at one point a “system issue” - and agreed to delete an encrypted messaging chat he had proposed calling “911.” Tricolor filed for Chapter 7 bankruptcy on September 10, 2025, just after placing more than 1,000 workers on unpaid leave.
During this stretch, the complaint says, the chief executive drew a salary that reached $2 million in 2025, received a $15 million “special” bonus, and bought a Miami home for roughly $18 million. The SEC is seeking to claw that money back, with penalties, and asks the court to bar the chief executive and the chief financial officer from running any public company again.
The takeaway for the industry is plain. One repeat buyer told the SEC that any double-pledging was a “bright line” it would never have crossed - a reminder of how much underwriters and institutional investors take collateral data on faith.
The allegations have not been tested in court, and no judge has ruled.

Meanwhile, Cetera's streak of Commonwealth recruitment continues in Washington, and an LPL advisor hops over to Raymond James in Maine.

The Sussex County wealth firm, built around business-owner clients, extends the California-based aggregator's footprint in the East Coast.

The Kestra-owned RIA acquirer merges the planning firm into KDI Wealth Management, creating a majority woman-led advisor team

Eight in 10 pre-retirees say the US retirement system wasn't built for them and most still haven't planned how to make their money last.

Just over 10% of advisors' wealth clients come from defined contribution plans, as capacity, data and technology gaps block the bridge to wealth
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

