
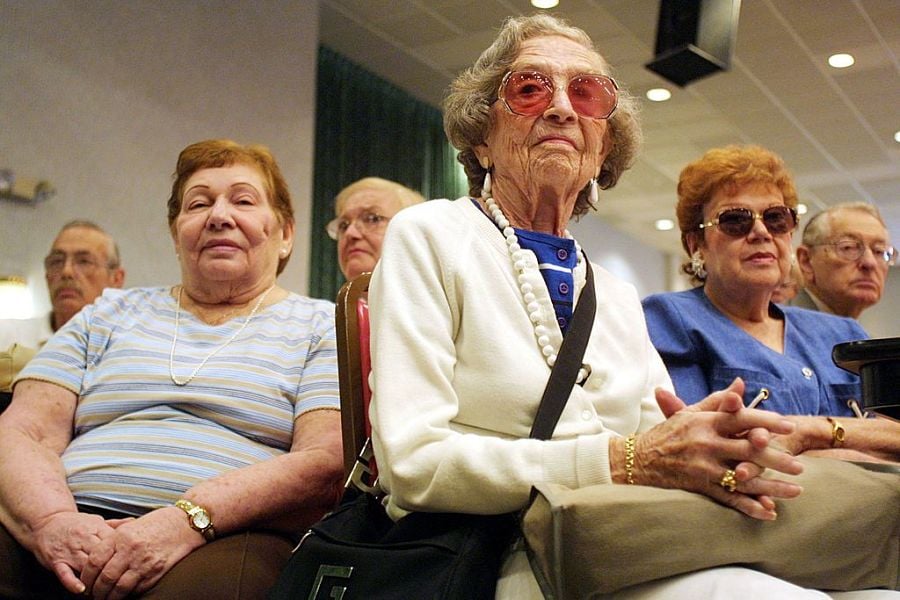
The COVID-19 pandemic has taught us all many lessons, including that good health is a precious commodity and life can change in an instant.
As the members of the massive baby boomer generation, now ages 56 to 74, move into retirement at the rate of 10,000 people a day, the pandemic highlights how a health care crisis and its related costs can crater a retirement plan. It’s a good reminder in advance of National Women’s Health Week next week, which is designed to raise awareness about steps women can take to improve their health.
More than half (56%) of middle-income boomers say their primary retirement concern is staying healthy enough to enjoy their retirement, according to a 2019 study from Bankers Life Center for a Secure Retirement.
And although nearly half (45%) of middle-income boomers, defined as households with annual income between $30,000 and $100,000 and under $1 million in investible assets, have experience as caregivers, almost 80% have not set any money aside specifically for their own retirement health care or long-term care needs, according to the study, “A Growing Urgency: Retirement Care Realities for Middle-Income Boomers.”
In fact, most boomers seem to be better prepared for death than life. More than 80% of the 1,500 boomers in the survey reported making at least one formal preparation for their death, but less than one-third have a plan for how they will receive care if they need it. And when it comes to caregiving, it is decidedly a woman’s issue.
More than three out of five (62%) of family caregivers are women compared to the 38% who are men. Two-thirds of middle-income boomers are providing care for a parent, while 17% are provided care for their spouse, partner or a parent-in-law.
When their husbands need long-term care, wives often are there to provide it. But, because women tend to outlive men by about five years on average, there may be nobody there to provide help for them when they need it.
Almost 70% of women age 75 or older are widowed, divorced or never married, compared to about 30% of older men who live alone, according to the AARP Public Policy Institute. More than 70% of nursing home residents are women. Their average age at admission was 80.
The National Institute on Aging cites several factors that can potentially contribute to a person’s risk of needing long-term care, including: advanced age; being female; being single; having unhealthy lifestyles, such as poor diet and lack of exercise; and having a family history of health issues that require long-term care.
Long-term care can be enormously expensive. The national average cost of year in an assisted living facility was more than $48,000 in 2019, and the price of a private room in a nursing home was more than twice as much—over $102,000—according to the Genworth Cost of Care Survey 2019.
How people pay for long-term care depends on their financial situation and the kinds of services they use. Although Medicare does not cover ongoing long-term care needs, more than half (56%) of the middle-income boomers in the Bankers Life survey mistakenly expect to use Medicare to pay for care if they need it. In reality, Medicare only covers some costs of short-term skilled care in a nursing home following a hospital stay.
Individuals who need long-term care often rely on a combination of payment sources including their personal savings; Medicaid, which has strict income and assets restrictions; long-term care insurance; life insurance with living benefits riders; or home equity through a reverse mortgage.
Taking steps to improve your health today is a good beginning. Developing a long-term care contingency plan is a smart way for a woman to create a secure retirement, knowing they may one day be on their own. Deciding how and where they want to receive care puts them in control of their future.
As Robinhood and Schwab roll out AI agents and assistants, a new survey finds advisors still edge out chatbots in terms of client trust.
See which platforms and providers earned 5-Star recognition this year
Meanwhile, a multigenerational Cambridge team has hopped to LPL in Michigan, and Cetera's run of Commonwealth recruitment continues in New Jersey.
TIAA survey finds 53% of Americans worry about running out of money, as AI and medical advances scramble retirement income planning.
Two wirehouse veterans choose advisor-owned model as independents target ultra-high-net-worth clients beyond portfolio management.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor
Northern Trust’s Ken Lassner shows advisors how to convert volatility into after-tax portfolio gains

