
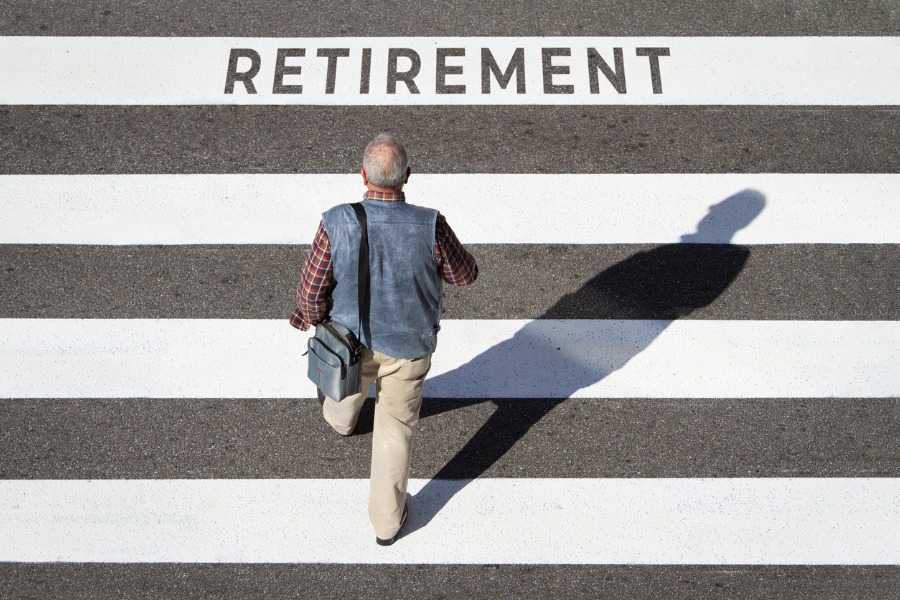
Americans say they need $5,094 a month to retire comfortably but most aren't close to generating it, according to the Schroders 2026 US Retirement Survey which polled 1,500 US investors between the ages of 30 and 79.
The figure is up from $5,032 in 2025, and highlights a retirement income target that keeps rising even as the strategies Americans plan to use - cash savings, 401(k) balances, and Social Security - remain strained by early-claiming decisions, a lack of income planning, and now a new source of anxiety: artificial intelligence.
Despite understanding the mechanics of delayed claiming, nearly half of non-retired Americans who took part in the poll, released September 2026, say they plan to file for Social Security before age 67, the full retirement age for anyone born in 1960 or later. Just 10 percent intend to wait until 70, the age at which monthly benefits are maximized, according to the Schroders survey.
Forty-five percent say they will need the money sooner for regular income, while 43 percent simply want access to funds as quickly as possible. Notably, 40 percent cite concern that Social Security itself may eventually run short or stop making payments altogether.
"While there is no single, right age for claiming Social Security, careful planning helps take the emotion out of your decision-making," said Deb Boyden, head of US defined contribution at Schroders. "Knowing your income, spending needs, and whether your investments match these needs will provide clarity that leads to better decisions on how to maximize Social Security."
As InvestmentNews has reported, advisors who focus on decumulation - not just accumulation and asset allocation are better positioned to guide clients through precisely these kinds of emotionally charged decisions.
Beyond claiming age, the survey reveals a deeper structural problem: most Americans reaching retirement have no plan for converting savings into income.
Among current retirees, 51 percent report having no specific income-generation strategy. Of those who do, the most common approaches are systematic withdrawals from retirement accounts (26 percent), certificates of deposit (20 percent), and dividend-producing stocks or mutual funds (20 percent).
Almost two-thirds of retirees say they wish they had done more retirement planning before leaving the workforce and 58 percent have no idea how long their savings will last.
The survey found that 56 percent of non-retired Americans describe the prospect of no longer receiving a regular paycheck as "concerning," while 20 percent describe it as "terrifying."
"Planning for retirement isn't just about how much you save — it's about knowing how you'll turn that savings into a reliable income stream," Boyden said. "Far too many people retire without a clear strategy for making their money last, and that uncertainty can be just as stressful as not having saved enough in the first place."
One finding stands apart from the familiar story of savings gaps and Social Security timing: 48 percent of non-retired Americans surveyed say they are concerned that AI will force them into retirement earlier than they planned.
That figure represents a significant new variable in retirement income planning; clients who might have expected another five to ten years of contributions could find their timelines compressed.
Among those with a workplace retirement plan, 74 percent say it is their single most important retirement asset. And 85 percent of those offered retirement income products within their plan say they are likely to keep assets in the plan after leaving the workforce - a figure that points to growing demand for in-plan income solutions.
The appetite for downside protection is equally striking. Ninety-one percent of workplace plan participants say they would be interested in a retirement investment product that actively manages the risk of loss while seeking to grow assets at a rate equal to the current cash rate plus 5 percent, according to the Schroders survey.
That level of demand suggests a significant opportunity for advisors who can help employer clients evaluate and communicate in-plan income options. Recent data highlights the lack of confidence many Americans have in managing their finances.
Confidence remains low across the board. Only 16 percent of non-retired Americans say they "definitely" expect to replace at least 75 percent of their last paycheck in retirement - the standard industry benchmark. Thirty-two percent say they "probably" will not reach that threshold, and 15 percent say they "definitely" will not. For advisors, the numbers point not to a lack of awareness but to a lack of structured guidance on how to bridge the gap.
The Schroders 2026 US Retirement Survey was conducted by 8 Acre Perspective among 1,500 US investors nationwide, ages 30 to 79, from March 20 to April 15, 2026.

A new JPMorganChase Institute report reveals how deeply stock market wealth now drives everyday American spending, especially for retirees.
A survey of 507 solo agers finds most lack confidence in their plans and that systems, not just individuals, need to change.
Two wealthtech providers are handing advisors the controls, letting firms design their own workflows and AI agents in plain language.
Edwin Lickiss earlier admitted that he defrauded at least 93 victims of over $9.5 million from 1998 through 2024.
New research shows Americans want control over their money but lack the confidence to take action – and advisors are the bridge.
Northern Trust’s Ken Lassner shows advisors how to convert volatility into after-tax portfolio gains
Dan Biagini of American Equity says the steady decline of pensions, longer lifespans and a reset in interest rates are rewriting how advisors build retirement income

