
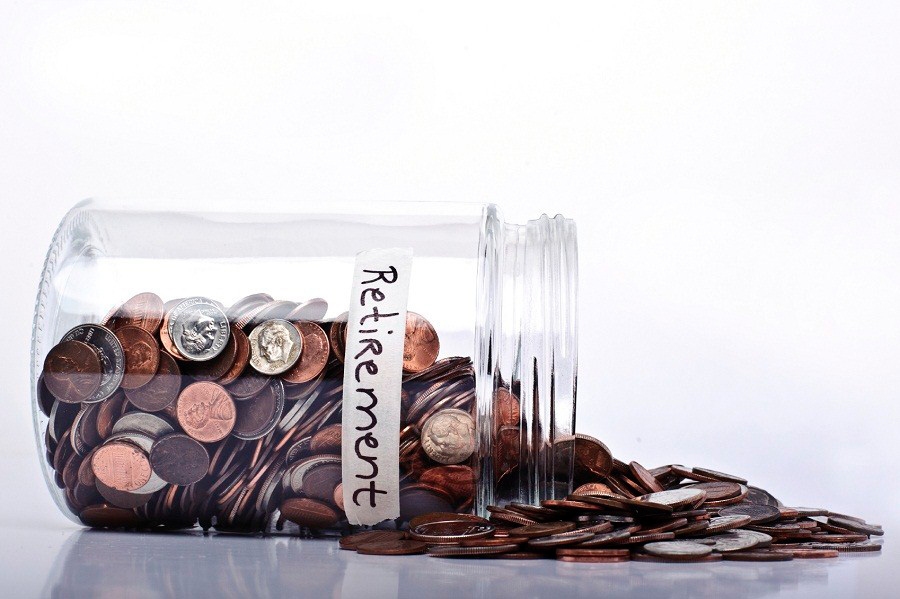
One in three Americans including half of all Gen Z workers may have retirement savings sitting in forgotten accounts from previous employers, according to new research by Empower.
The Greenwood Village, Colorado-based retirement services firm administers more than $2.1 trillion in assets for more than 20 million individuals and its study is drawn from a nationally representative survey of 2,005 adults conducted July 30–August 1, 2026.
The report puts a number on what Empower calls "retirement drift" – the gradual accumulation of abandoned 401(k) accounts as workers change employers across a career. More than half of respondents (53%) have switched employers three or more times, and 39% say their retirement savings are already scattered across accounts from different jobs.
The problem is sharpest among younger cohorts. Half of Gen Z (50%) and 45% of Millennials say they may have retirement savings from a previous employer that they have lost track of, compared with 34% of Americans overall, 30% of Gen X, and just 14% of Boomers.
The IRA rollover market has long been viewed as a major growth avenue for advisory practices, and the Empower data suggests demand for guidance is not being met.
Two-thirds of survey respondents (66%) wish someone had explained their retirement savings options when they changed jobs, and 54% weren't aware they had several options after leaving an employer.
Among those who do understand the options, the barriers are practical rather than philosophical: 76% say clear, step-by-step guidance would make them more likely to act, while 70% would be more likely to consolidate old accounts if the process took less time.
That appetite for simplicity aligns directly with the value proposition most financial advisors can offer. Talking with a financial professional was the most commonly cited catalyst that would prompt Americans to review or act on their retirement savings, selected by 22% of respondents.
"Deciding what to do with a 401(k) from a previous employer can take a back seat when you're starting a new job and managing other financial priorities," said Jane Bartosik, SVP, Wealth Solutions at Empower. "These accounts can accumulate, making it harder to see your complete retirement picture and know what steps to take next."
The survey documents how inaction compounds over time. Nearly half of Americans (47%) say they have delayed dealing with retirement savings, such as initiating a rollover, because the process felt overwhelming – a figure that rises to 58% among Gen Z and 57% among Millennials, compared with just 23% of Boomers.
More than half (54%) say managing retirement savings falls to the bottom of their financial to-do list, and the same proportion say retirement planning is more confusing than other areas of personal finance.
According to a 2025 Capitalize study produced in partnership with the Center for Retirement Research at Boston College, as of July 2025 there were approximately 31.9 million forgotten 401(k) accounts in the United States, holding an estimated $2.1 trillion in assets – nearly double the number of unclaimed accounts counted in 2015.
That research estimates that, in a worst-case scenario involving high fees and poor asset allocation, a forgotten account could cost a worker more than $500,000 in potential retirement wealth over a long career.
The Empower study adds a motivational dimension to those figures. Some 84% of respondents say keeping their retirement savings organized gives them greater peace of mind, and 83% feel more in control when those savings are consolidated in one place.
However, many remain uncertain about how to begin: 59% say they are unsure whether a Roth or traditional IRA is the better fit for their financial situation, and 53% had always assumed IRAs were only for people with more money than they had – a misconception that rises to 64% among Millennials.
Despite the growing presence of AI-powered financial tools, the survey reinforces the standing of human advisors for retirement decisions.
Seventy-eight percent of respondents trust a financial professional more than AI for important retirement decisions, while 73% view AI as a complement to professional advice rather than a replacement. That finding positions advisors well in an environment where technology adoption is accelerating but trust remains anchored in human relationships.
The Empower data also points to an unmet need for continuity. Eighty-one percent of Americans say they want retirement guidance that stays with them throughout their working lives, not just when they are employed by a particular firm.
The DOL's Retirement Savings Lost and Found database, launched in late December 2024 under the SECURE 2.0 Act, offers one resource for workers looking to locate forgotten accounts – though the tool currently focuses on workers approaching retirement age and is not yet comprehensive across all plan types and age groups.

New BCG research names financial services among the world's most AI-exposed industries and the US as a top-tier AI economy.
Rockefeller Capital Management's Mallory Findley on how avoiding conversations risks derailing even the best-laid estate plans.
Nevis joins Jump at RIA platform Focus as both vendors’ AI tools aim to handle account opening and notetaking.
Ballast Rock Private Wealth has also brough on a veteran advisor focused on multigenerational planning for business owners and families.
Edward Jones study finds caregivers to older adults spend $8,737 a year out of pocket in "generosity paradox" as savings, careers and health absorb the strain.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

