
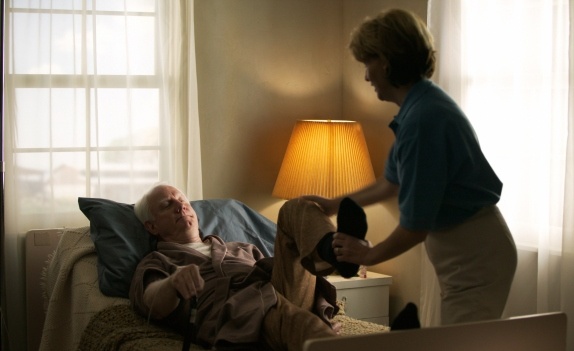
Many advisors and their assistants have had the following experience: A long-time client calls with a question or, when responding to a call, somehow seems “off” and not as focused as usual. Maybe it’s a bad day, but the next call results in the same unsettling feeling that something is amiss.
Something is. As Emile Hallez recently reported, cognitive decline is a fact of life among America’s aging population and financial advisors often find themselves on the front lines of an effort to protect clients’ lifetime savings and investments from the consequences of impaired mental capacity.
Advisors who once thought that managing investments to deliver a comfortable retirement was the main challenge of their work are now likely to discover that protecting nest eggs as clients become ill-equipped to deal with money matters poses an even greater challenge. As one expert noted, since half of people develop mild cognitive impairment or dementia by their mid-80s, having a great financial plan may mean nothing when hundreds of thousands of dollars, or even millions, can disappear from an account in weeks or months due to a client’s declining cognitive abilities.
To deal with the reality of widespread cognitive decline among their aging clients, advisors should be proactive in taking steps to protect clients and themselves. The first step is for advisors and staff to be aware of how significant and widespread the issue of cognitive decline has become, and to look for possible signs of it when dealing with clients.
Second, start having discussions when clients are in their late 50s and early 60s about the need to determine when they should start getting help with health care and financial decisions. Asking clients to sign an “incapacity letter” ahead of time, which directs advisors to speak with surrogates if red flags appear, is a wise idea suggested by one advisor in the story.
Encouraging clients to involve trusted grown children or others in their plans and having those trusted relatives or friends get to know the advisor for this purpose is another solid step. Honestly positioning this interaction as a way to conserve assets and protect a client in the event of cognitive decline is a far better way to encourage managing intergenerational wealth than hounding parents to introduce you to their children.
It’s also important to educate clients about financial fraud and the ways in which scam artists and, sadly, family members prey on older people, an educational effort in which many advisors and firms already are engaged. The problem is huge. Financial fraud costs older Americans an estimated $3 billion a year, and a 2020 study from the AARP Public Policy Institute found family members steal twice as much money as strangers.
Helping clients and their families prepare for and deal with cognitive decline is probably among the most delicate assignments an advisor will face. But as the advised population ages, it’s a responsibility more and more advisors must be prepared to assume.
Valerie Bevan joins LPL Financial after more than 30 years in financial services, citing platform flexibility and advisor independence.
A new independent benchmark finds a widening gap between AI leaders and laggards across 30 of the world's largest investment firms.

Jamie Price says LPL shifted its Commonwealth target from advisors to assets, letting 16 months of growth mask departures

80% of Baby Boomers prefer guaranteed income over growth investments, yet only 17% hold an annuity, leaving protection gaps for financial advisors to close

“Even with all the work done before hand, this is still a bit stressful,” one advisor said.
Advisors are broadening the conversation beyond savings to help clients prepare for the realities of longer lives
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.

