
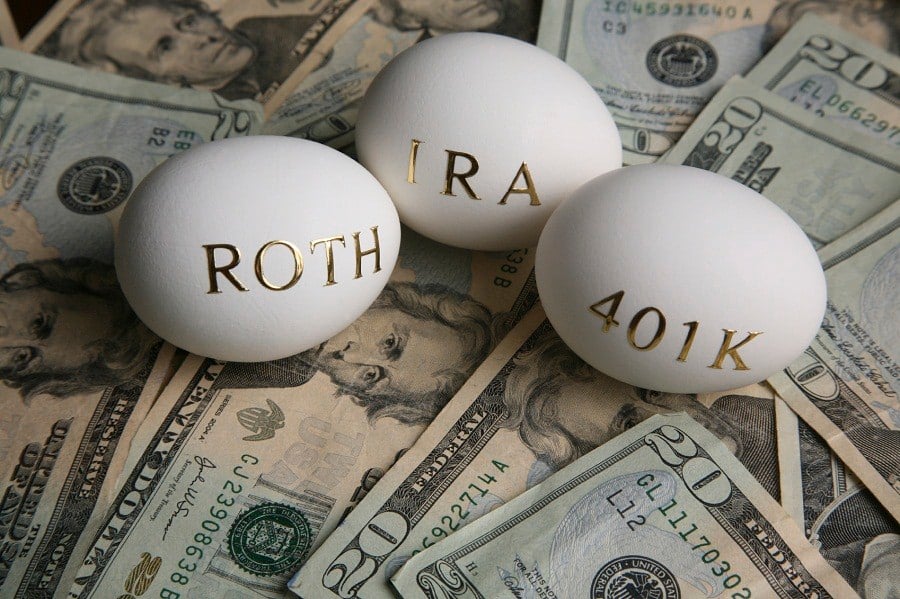
When retirees roll over assets from a 401(k) to an individual retirement account, 75% reduce their equity exposure, according to research from J.P. Morgan Asset Management and the Employee Benefit Research Institute.
The research, based on data EBRI collected and studied on 31,000 people as they entered retirement between 2013 and 2018, also found that required minimum distributions appear to be the dominant withdrawal “guidance.” The vast majority of retirees, the research found, did not take distributions before they reached the RMD age, and those older than the RMD age choose to take only the RMD amount.
“The RMD approach is inefficient,” said Katherine Roy, chief retirement strategist at J.P. Morgan Asset Management. “It does not generate income that supports retirees’ declining spending behavior and may leave a sizable account balance at age 100.”
Another key finding was that income and spending in retirement are highly correlated. As income increases with the start of Social Security and RMDs, spending increases, with households that have regular income from an annuity and/or a pension spending more even if they have similar levels of observable retirement wealth.
Raymond James lures a $125M Merrill Lynch advisor in Charlotte while a Stifel pair breaks away to go independent in Southern Oregon
Pave Finance, DPL Financial Partners and Gottfried & Somberg also add senior leaders as RIAs and wealthtech firms deepen their benches
What the feud between “twin” index funds teaches thematic investors
RIAs flag AI risk in Form ADV more often than they admit using AI

Fake advisors, fake platforms, fake crypto - all on a six-month timer
Advisors are broadening the conversation beyond savings to help clients prepare for the realities of longer lives
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.

