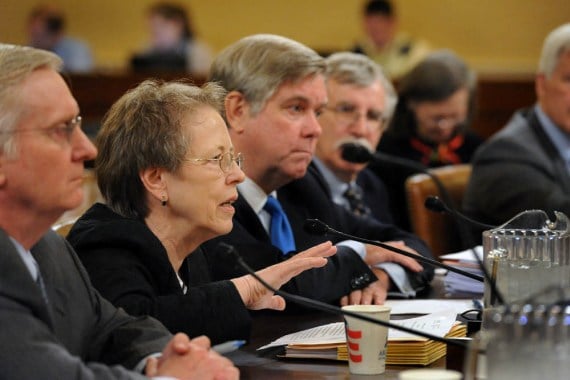
At House hearing, neither Dems nor Republicans seemed eager to tinker with main selling point of 401(k)s and IRAs
Tax breaks for retirement savings plans emerged unscathed from a House hearing Tuesday that focused on whether their favorable treatment should be curbed as part of comprehensive tax reform.
The session marked the first time that the tax-writing House Ways and Means Committee has tackled the potentially explosive issue.
Last month, the House approved a Republican budget along partisan lines that included major tax reform. The plan, offered by House Budget Committee Chairman Paul Ryan, R-Wis., would streamline the current six tax brackets to two and lower the top rate from the current 35% to 25%. It also would require the elimination of many so-called tax expenditures. The proposal didn't identify which ones, although retirement plan tax breaks are considered tax expenditures.
On Tuesday, however, Republicans and Democrats on the Ways and Means Committee expressed support for retirement savings incentives that would allow workers to put money into 401(k) and individual retirement accounts on a tax-free basis. The continuation of such special treatment would come at a price, though. Such breaks would cost the federal government $375.9 billion in revenue for defined-contribution plans and $86 billion for IRAs over the next five years.
That would make retirement savings plans one of the biggest tax expenditures, according to the congressional Joint Committee on Taxation. Ways and Means Chairman Dave Camp, R-Mich., however, said that Mr. Ryan's budget wouldn't force Congress to put every tax break on the chopping block. “You do not have to eliminate all expenditures to get to that [25% top rate] level — not at all,” Mr. Camp told reporters after the hearing.
He stressed that Tuesday's hearing was just the opening salvo in comprehensive tax reform. “I wasn't really looking for resolution today,” Mr. Camp said. “It was really framing the debate.”
His Democratic counterpart, Rep. Sander Levin, D-Mich., ranking member of the committee, maintained that the hearing demonstrated how difficult it would be for Republicans to accomplish the tax reform outlined in Mr. Ryan's plan. “My objection is that Republicans came out with a figure of 25% without talking about the consequences of how to get there,” Mr. Levin told reporters after the hearing. “It undermines the notion that you can get rid of [tax] preferences without getting rid of important policy.”
A panel of five retirement savings experts didn't have to work too hard to convince lawmakers that employer-sponsored defined-contribution plans, which hold about $4.5 trillion in assets, and IRA accounts, which total $4.7 trillion in assets, are essential for providing security in post-work life. “I didn't see anybody looking to eliminate them – either Republicans or Democrats,” William Sweetnam, a principal at Groom Law Group, said after he testified at the hearing.
Witnesses testified that the calculation of the tax expenditure for retirement savings is skewed because the incentives are tax deferrals and not permanent tax exclusions. Retirees would pay what they owed the government when they took distributions.
“Every single dollar exempt from tax now will be subject to tax in the future,” said Judy Miller, chief of actuarial issues and director of retirement policy at the American Society of Pension Professionals and Actuaries. She also sought to puncture the criticism that retirement tax incentives are used disproportionately by the wealthy.
Ms. Miller argued that nondiscrimination rules ensure that employer-sponsored plans do not favor highly paid employees.
“As a result, this tax incentive is more progressive than the current progressive tax code,” she said in prepared testimony.
Lowering tax rates and broadening the tax base has become a bipartisan mantra as Congress begins to think about tax reform. Scores of tax breaks will have to be jettisoned to achieve that end. And those tax expenditures all have advocates who will defend them as fiercely as the retirement savings acolytes.
“That's what makes tax reform so challenging,” Mr. Sweetnam said.