
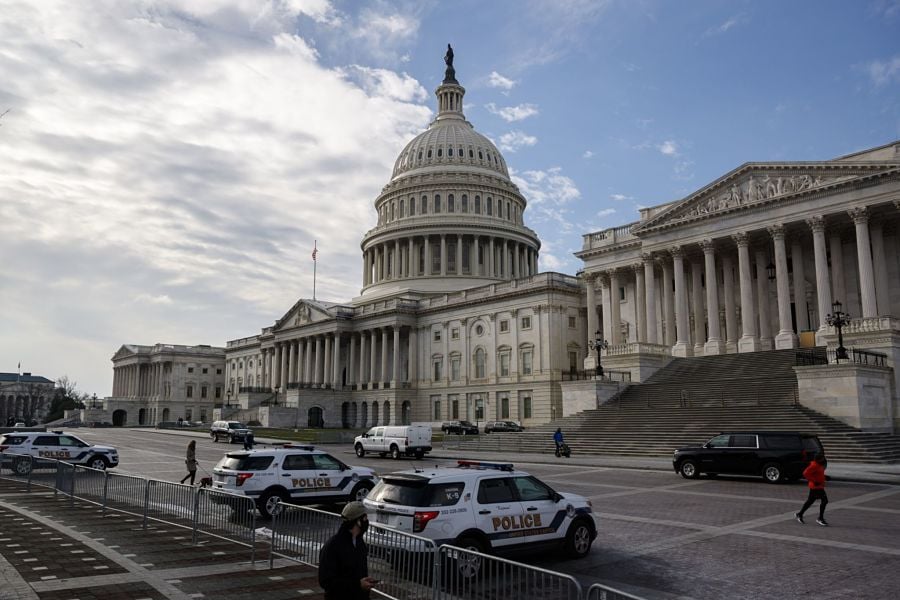
As Democrats in Washington try to reach an agreement on sweeping legislation that incorporates the Biden administration’s economic agenda, the package seems to be shrinking and could jettison some tax hikes on the wealthy.
Over the course of this week, published reports have indicated congressional Democrats are whittling the proposed $3.5 trillion Build Back Better Act down to about $2 trillion to cobble together enough support to advance the legislation.
Progressive and centrist Democrats have been haggling for weeks over the size of the package, which includes spending on a wide array of social and climate programs as well as tax increases to pay for them. The bill is being considered under a parliamentary procedure that sidesteps a Senate Republican filibuster, but it requires support from almost all Capitol Hill Democrats.
Slashing the measure by $1.5 trillion means major spending provisions will be taken out, which could have an equally big impact on the tax side, said Michael Townsend, managing director of legislative and regulatory affairs at Charles Schwab & Co. Inc.
“You don’t need as much revenue, and so some of these tax increases may be shrunk or, even more likely, fall away,” Townsend said during a session Wednesday at the virtual Schwab Impact conference. “And we just don’t know at this point which ones.”
He cited two tax increases included in the House version of the bill that have pretty good odds of being in a final package. One is a proposal to reduce the estate tax exemption. The other is a proposal to raise the top capital gains tax rate.
Financial advisers were relieved that the House bill didn't include a provision to tax unrealized capital gains on inherited assets, which would end the so-called step-up-in-basis.
What is in the bill is a provision to lower the estate tax exemption for an individual from $11 million to about $6 million — a move that was scheduled to happen at the end of 2025 but instead would occur at the end of this year if the bill becomes law.
“They went the easier route, politically speaking at least, which is just lower the exemption,” Townsend said. “My sense right now is that is something that has pretty strong support and is a top candidate for being included in a compromise bill.”
In the House version of the bill, the top capital gains rate would increase from 20% to 25% — plus a 3.8% Medicare surtax — for individuals making more than $400,000 and households making more than $450,000. If the provision survives, it would be retroactive to Sept. 13.
“Right now, I think the sense is that the retroactivity … of the capital gains and dividends provision could stay in the final package,” Townsend said.
Another provision in the House bill would raise taxes on the wealthy by targeting so-called mega individual retirement accounts. The legislation would require retirement savers who have accumulated more than $10 million across all their retirement accounts to take an annual required minimum distribution of 50% of their assets in excess of $10 million regardless of their age.
Like the other tax provision, it’s not clear the mega-IRA one will survive. But if it falls by the wayside, it could return in future bills.
“Now these provisions are sort of out there,” Townsend said. “I think that means it’s likely they come back, even if they’re not in this bill. The fact is that they raise some revenue, and that revenue is important to people who want to spend money in Congress.”
Negotiations over the Build Back Better bill are likely to continue at least through October.
“This is very much a moving target,” Townsend said. “And I think it’s going to be another few weeks before we really know how this is going to shake out.”
As Robinhood and Schwab roll out AI agents and assistants, a new survey finds advisors still edge out chatbots in terms of client trust.
See which platforms and providers earned 5-Star recognition this year
Meanwhile, a multigenerational Cambridge team has hopped to LPL in Michigan, and Cetera's run of Commonwealth recruitment continues in New Jersey.
TIAA survey finds 53% of Americans worry about running out of money, as AI and medical advances scramble retirement income planning.
Two wirehouse veterans choose advisor-owned model as independents target ultra-high-net-worth clients beyond portfolio management.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor
Northern Trust’s Ken Lassner shows advisors how to convert volatility into after-tax portfolio gains

