Wells Fargo sued by borrowers over reverse mortgage policies

Wells Fargo sued by borrowers over reverse mortgage policies
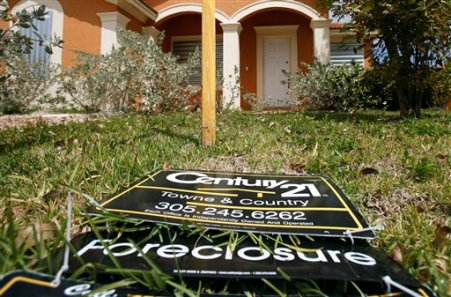
Wells Fargo & Co. is ignoring federal rules on reverse mortgages and forcing homes into foreclosure instead of giving heirs a chance to buy them, according to a lawsuit.
JUN 29, 2012
Wells Fargo & Co. is ignoring federal rules on reverse mortgages and forcing homes into foreclosure instead of giving heirs a chance to buy them, according to a lawsuit. Estates and surviving spouses have the right to purchase properties at 95 percent of appraised value after the death of a borrower who took out a federally-insured reverse mortgage, lawyers for a California man said in the complaint filed yesterday in federal court in San Francisco. Wells Fargo hasn't been notifying heirs of this right and has been starting foreclosures if demands aren't met for repayment of the full mortgage balance, according to the complaint filed by the son of a California homeowner. The plaintiff, Robert Chandler, also sued the Federal National Mortgage Association, or Fannie Mae. “Wells Fargo's actions are not just wrong, they are economically irrational,” Michael Ng, Chandler's attorney, said today in a statement. “Even though elderly borrowers paid for insurance that protects the bank against the downturn in the housing market, Wells Fargo insists on evicting family members from homes that will go unsold and unoccupied.” The lawsuit, brought as a class action by Chandler on behalf of himself and other heirs, seeks a court order stopping foreclosures and evictions in affected homes and damages for breach of contract. Wells ‘Reviewing' Complaint Wells Fargo is “reviewing” the complaint and “will reserve comment,” Vickee Adams, a spokeswoman for the San Francisco-based company, said today. Reverse mortgages are available only to home owners aged 62 or older. In some cases, when one spouse is younger than 62, only the older spouse's name will appear on the reverse-mortgage documents. Reverse-mortgage loans pay out a home's equity to the homeowner, often in installments, and are usually repaid when the borrower dies or moves out of the house. Borrowers are considered in arrears if they don't keep current on property taxes and insurance. --Bloomberg News--

Latest News

Advisor moves: Atlas tops $1B as Wells Fargo, UBS add bank veterans

Wells Fargo adds two bank-channel recruits, UBS lands a JPMorgan Chase veteran, and a multi-family office lifts Atlas past $1B

Advisor mom’s son used her password to log into clients’ accounts, sell deal with conflicts, according to Washington state

“The state comes down on you in years when you make 40% returns for clients,” said Bill Swayne, the advisor and son of Candace Swayne.

Osaic in talks with Anthropic as AI reshapes advisor workforce

The Independent broker-dealer giant has had “active conversations” with the Claude maker, which is days away from its expected IPO

The retirement milestone advisors aren't tracking

For Gen X clients entering life after work, answering the financial question isn't enough to solve the entire retirement equation.

Wealthtech firms target stock pay, pensions and heirs for advisors

Tools from Grantd, Income Lab and Healthspan Wealth aim to keep RIAs involved in clients’ biggest money decisions

SPONSORED Best Practices for Engaging Women Around Alternatives

Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.

SPONSORED Built on insurance experience to deliver on long-term promises

Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
