
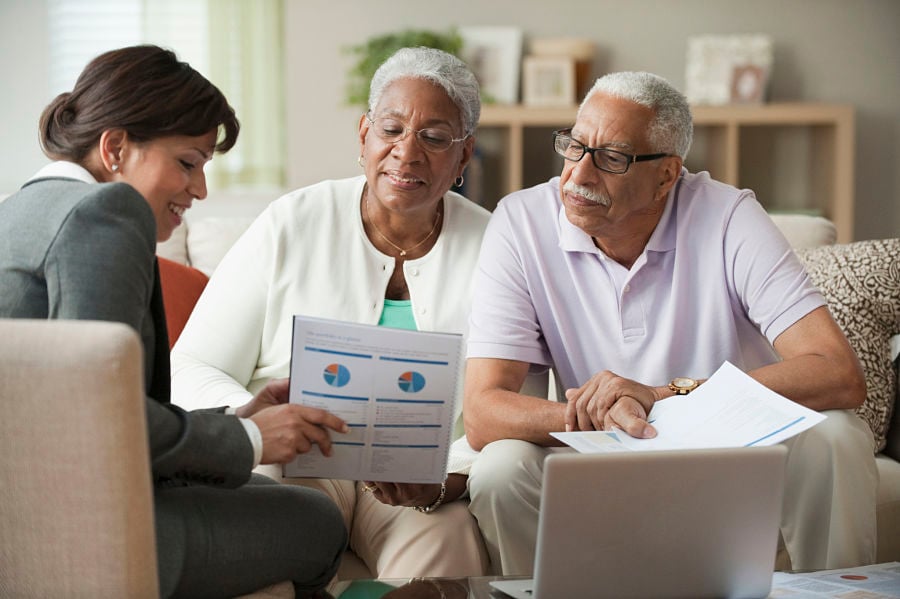
Longevity risk continues to be a hot topic for advisors, especially as their clients continue to suffer from a lack of "longevity literacy."
The TIAA Institute and the Global Financial Literacy Excellence Center at the George Washington University School of Business released data last week showing that American adults are overwhelming unaware of both their potential lifespans and the amount of money needed to cover them.
Respondents were asked to identify the likelihood among 65-year-olds of living to 90 and the likelihood of dying relatively early, in this case, by age 70. Surprisingly, only 12% got both answers correct. Asked how long they think a 65-year-old is likely to live, just 35% correctly said 84 for men and 87 for women.
The reason why such longevity research is so vital to know and understand is because it helps with retirement readiness.
For example, according to the survey, 50% of respondents have already determined how much they need to save for retirement, compared to just 32% of those with weak longevity literacy. Meanwhile, 72% said they are saving for retirement on a regular basis, compared to 58% of those with weak longevity literacy. Finally, 69% of respondents are confident about having enough money to live comfortably throughout their retirement, compared to 53% of those with weak literacy.
David Demming, founder of Demming Financial, said he is always trying to raise the level of his clients’ longevity literacy, no matter their age.
“We just finished a review with a couple aged 84 and 83, respectively. Our topic was longevity risk since he has a fixed pension, which is eroding because of inflation. We discussed the new ‘normal’ inflation rate going forward and the fact that an 80-plus-year-old today is measured against today’s life expectancy, not that of our parents' and grandparents’ generations,” Demming said.
Nicholas Bunio, a certified financial planner with Retirement Wealth Advisors, isn't surprised by the survey results. In his view, people tend to underestimate how long they will live by about five years. Furthermore, there's a psychological aspect, given that retirees have “saved all their life, have a pile of money, and they want to enjoy it.
“I don't blame them, but they still need a budget and most people hate budgets,” Bunio said. “But in the end, not enjoying all your money may not feel good, but running out of money at 75 while you live to 89 is terrible. You're going to feel that every single day compared to dying with money left over.”
In fact, a recent survey from Allianz Life showed that 61% of Americans said they fear running out of money more than death.
Dean Tsantes, a certified financial planner at VLP Financial Advisors, said he tends to be conservative when planning and pushes the age of death to at least 95 considering the advances in modern medicine.
“It’s our job to show them how to not run out of money and that is by planning conservatively,” Tsantes said. “Imagine if my planning was based off of this study and planned for them to live until 84, but they had another 10 or 15 years of needing portfolio withdrawals. That wouldn’t make me look very good.”
Another interesting way to consider how long people think they will live is to look at when they claim Social Security.
“I often talk to people that would be better off waiting until 70 but when they find out the break-even relative to collecting at full retirement age won’t happen until they are over 82, they start getting very concerned that they or their spouse will never make it that far. This type of thinking can often lead to suboptimal decisions,” said Jon Swanburg, president of TSA Wealth Management.
New UMA, direct indexing and asset location capabilities aim to cut manual work for advisors managing personalized portfolios
As notetakers push into account opening, a consultant warns RIAs risk ‘buying redundancy’ instead of capability
The senior recruiter position at LPL Financial can lead to future success and industry leadership.
Hackers are already probing two bugs in software that runs most of the web. European Government and other major sites have already been taken down for emergency patches.
Unclaimed auto accounts can’t take family money, so advisors face questions on 529s, divorce terms, employer funding and stock gifts.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

