
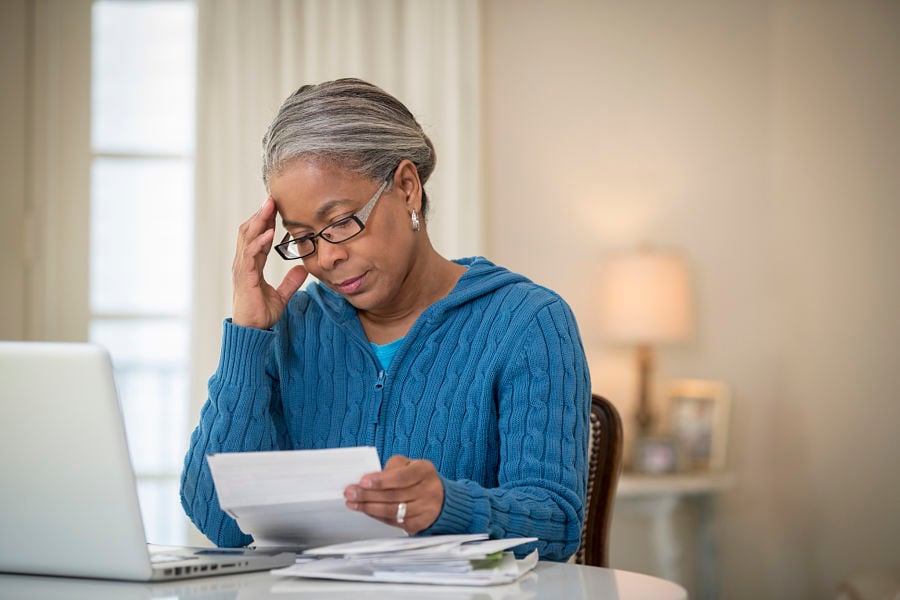
While retirees are concerned about exhausting their savings and the impact of inflation, anxiety over health care expenses weighs heaviest on their minds, according to a new survey by eHealth, an online health insurance marketplace.
The research it conducted with Retirable, a comprehensive retirement planning service, sheds fresh light on the challenges faced by Americans ages 60 to 70 as they navigate the collision of health care and financial planning in their retirement years.
According to the joint study, which drew insights from more than 520 individuals, 63 percent ranked health care costs as their top concern in retirement, which trumped running out of money (58 percent) and inflation (53 percent).
That dread leads many retirees to cut back on their current spending, with 55 percent indicating they live more frugally as they consider their health care expenses. Still, only a third of respondents said they had set aside funds specifically for health care costs they anticipated facing after retiring.
According to eHealth CEO Fran Soistman, the findings underscore the importance of having the right Medicare health plan in retirement.
“Affordable premiums are key, but it’s also important to look beyond premiums,” Soistman said.
For Retirable CEO Tyler End, the report’s insights should be a reminder of the need for long-term retirement planning for both retirees and those approaching retirement.
“Medicare beneficiaries understand the value of working with a licensed agent when choosing their coverage, but too few understand the value of working with a financial planner specializing in retirement," he said.
The report also uncovered a concerning outlook for financial sustainability in retirement, with only 42 percent of current retirees confident about the chances they’ll have enough money to last through their retirement years. Those yet to retire were even less confident, with just 29 percent believing they’ll have enough.
The burden of non-mortgage debt was also a significant issue: Among the 46 percent of participants saying they’re still carrying that debt, nearly 80 percent said they owe $5,000 or more.
The poll also revealed rampant worries over financial fraud and identity theft among three-quarters (73 percent) of respondents, including 39 percent who say they’ve already been victimized.
Mercer adds specialized equity compensation tech and Big Four tax talent as UHNW demand for integrated tax planning intensifies.

Two CFP and CFA credentialed advisors unite planning and markets expertise under a new Richmond practice.
When the largest RIAs recruit for AI, they name Copilot, ChatGPT and Claude in job posts far more often than advisor-specific fintechs, Caddi data shows
Bicknell said that Mariner's Humanity Labs partnership is key to growing his mega-RIA from 70,000 to 500,000 households by 2028
Final rule moves roughly two-thirds of SEC-registered RIAs under the Regulatory Flexibility Act’s small-business lens, up from about 3%
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

