
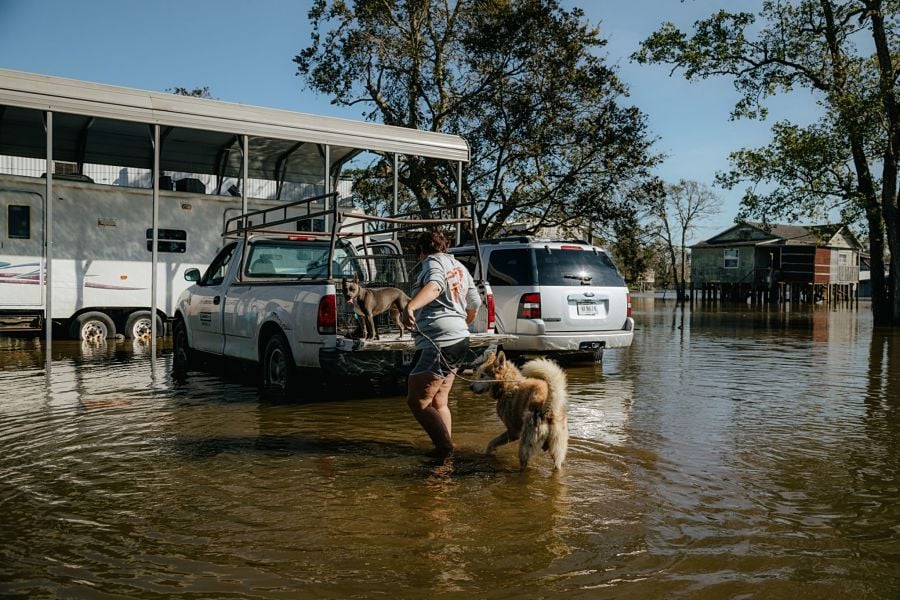
So many tropical cyclones have emerged in the Atlantic Ocean this year that we’ve run out of human names for them and are now well into the Greek alphabet. The 29th and 30th named storms are spinning over the ocean right now (hello, Eta and Theta).
On either side of the Atlantic, governments are starting to take these storms more seriously. The Federal Reserve and the U.K. Treasury have both released positions on climate risk disclosure, and their words are a bit of a jolt in the normally staid proceedings of central banks and finance ministries.
In its latest Financial Stability Report, the Fed specifically calls out climate change as a near-term risk to the financial system. Climate change, it concludes, “increases the likelihood of dislocations and disruptions in the economy” and “is likely to increase financial shocks and financial system vulnerabilities that could further amplify these shocks.”
The publication describes how both acute and chronic hazards could lead to rapid repricing of risk. Acute hazards like “storms, floods, droughts, or wildfires, can quickly alter, or reveal new information about, future economic conditions or the value of real or financial assets,” it says. Chronic hazards, like slowly rising sea levels, would seem at first to be easier to price—but “in the presence of rapid shifts in public perceptions of risk,” chronic hazards “have the potential to produce similar abrupt repricing events.”
The central bank concludes its section on climate by saying it expects that banks “have systems in place that appropriately identify, measure, control, and monitor all of their material risks, which for many banks are likely to extend to climate risks.”
On Nov. 9, the U.K.’s top treasury official, Chancellor of the Exchequer Rishi Sunak, took that one giant step further by, among other things, mandating that all major U.K. companies and financial institutions disclose their climate risk in line with the guidance set by the Taskforce on Climate-Related Financial Disclosures by 2025. (Michael R. Bloomberg, the founder and majority shareholder of Bloomberg, the parent company of Bloomberg News, is the chair of TCFD.)
The government’s road map toward mandatory climate-related disclosures lays out in detail what companies can expect, and by when. It also shows the scope of Treasury’s ambition and the speed with which it expects companies to comply.
The government measures the degree of disclosure as a percentage of a given business sector’s market capitalization, or for financial institutions, assets under management. By 2022, the U.K. expects 100% of “premium listed companies” such as BP and Royal Dutch Shell, to have TCFD-aligned climate risk disclosures. By 2022, it expects 94% disclosure from bank and building societies, and 89% disclosure from insurers.
Climate risk disclosure might seem like a somewhat distant and certainly very technical subset of financial market regulation. But as the Fed suggests, climate risk is both here and now, and it has present-day implications for business. There’s a real upside to better understanding climate risk.
Disclosure is coming, and in some markets, coming quite soon. Companies have many types of risks that need measuring and understanding, from policy risk to reputation. They also have many things to gain from managing those risks, from better product-market fit for a lower-carbon economy to greater resilience to supply chain disruption.
Her Majesty's Treasury is taking the product of measuring and understanding climate risk and making it a requirement for the U.K.'s most important businesses and financial institutions. Could the U.S. do the same? The incoming administration can take a whole-government approach, even if it may not have the Senate control to pass its climate measures into law. That approach could include following the U.K.'s lead, with the Securities and Exchange Commission requiring disclosure of climate risks. That, and the Fed's guidance, could lead to less risky, climate-positive business and investment strategies.

Heartwood Wealth Advisors deal marks the serial acquirer's 36th-ever transaction as third-quarter RIA M&A volume slips 19%

The AI lab disclosed more than $8 billion in 2025 losses on an operating basis as financial advisors weigh a supersized listing likely to land past the midterms.
Valuations and ethical fit are top of mind nowadays, but questions of liability are also crucial for RIA sellers worried about post-sale risks.

Goldman's president and COO is expected to replace David Solomon as CEO as soon as 2027, ending a near-decade at the firm's helm.

A state-by-state Medicaid report card, federal cuts starting in January and a home-equity cap due in 2028 are pushing a program most affluent families ignore into the planning conversation.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor
Northern Trust’s Ken Lassner shows advisors how to convert volatility into after-tax portfolio gains

