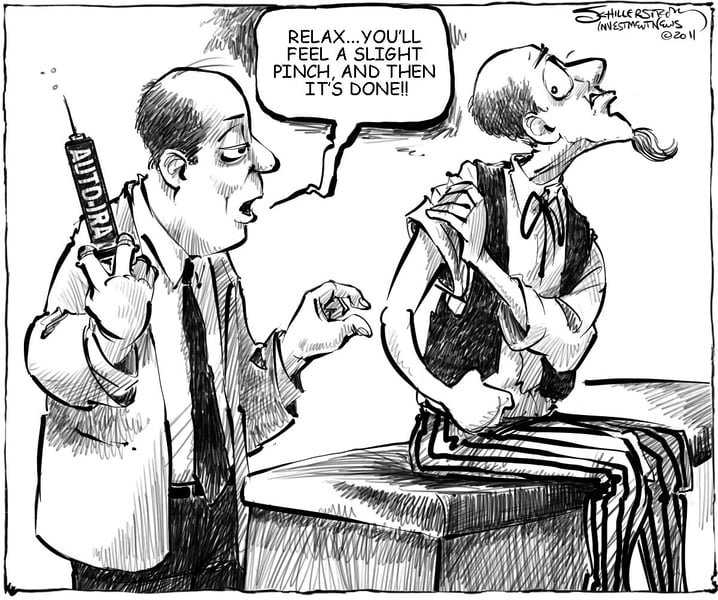
More than ever, employees of small companies face the prospect of a bleak retirement. As it stands, 75 million Americans — a figure that represents nearly 40% of employees in the private sector —
don't have access to any retirement plan at work. For those who work at companies with fewer than 100 employees, that figure jumps to 55%.
For that reason, any legislation that would result in the creation of automatic individual retirement accounts deserves serious consideration by lawmakers, financial services companies and financial advisers.
Despite having support from both parties, President Barack Obama has tried and failed three times to turn the auto IRA into a reality.
Another push for auto-IRA legislation is expected this year.
“Our hope is that it will continue to have bipartisan support,” J. Mark Iwry, a deputy assistant secretary for retirement and health policy at the Treasury Department, said during a presentation on retirement issues last month in Washington.
“Given all of the events of the past couple of years, things have often been partisan, and it hasn't been easy for Congress to agree,” he said. “We hope that this will move forward.”
So do we. Without such a plan, millions of Americans run the risk of being unable to maintain their standard of living during retirement unless they significantly bolster their savings or work well into their golden years.
Auto IRAs offer the most effective, secure and viable way of nudging employees at companies without retirement plans to save, thereby reducing their dependence on
Social Security. Like auto enrollment in defined-contribution plans, auto IRAs would make saving easier and far more likely to occur by taking advantage of people's proclivity for inertia and by tapping into the accretive force of systematic payroll deposits.
Any legislation creating auto IRAs should mandate that employers that don't sponsor retirement plans automatically enroll full-time workers in IRAs.
Starting out, a minimum of 3% of the employee's salary should go into the account, and there should be a mechanism to raise the contribution level automatically as the employee's pay increases. For example, an auto IRA could be set up so that the contribution level increases by an additional percentage point each time the employee receives a raise, capping off at some higher level — say, 8%.
Initially, the mandate should be applied to companies with 50 or more workers and phased down to those with 10 or more workers over a period of three years. The phase-in period would allow smaller companies to get used to the idea of auto IRAs and to take advantage of any economies of scale that may result from their widespread use.
The passage of the Pension Protection Act of 2006, which allowed employers to enroll workers into their retirement plans automatically, makes a compelling case for the adoption of auto IRAs.
About 57% of big companies now automatically enroll new employees in their retirement plans, up from 24% in 2006, according to Aon Hewitt. Additionally, automatic contribution escalation is now offered by 47% of plans, up from 17% in 2006.
Companies with auto enrollment report average participation rates above 85%, compared with 67% for those without it, Aon Hewitt reported.
The total annual amount being put into 401(k) plans has increased by 13% since 2006 to an estimated $284.5 billion this year, according to Cerulli Associates Inc.
Auto enrollment works because it is easy, and it works because it takes money out of employees' hands before it lands in their paychecks.
Those working at companies without retirement plans are on their own. The auto IRA could be a powerful ally to help them reach their retirement goals.