
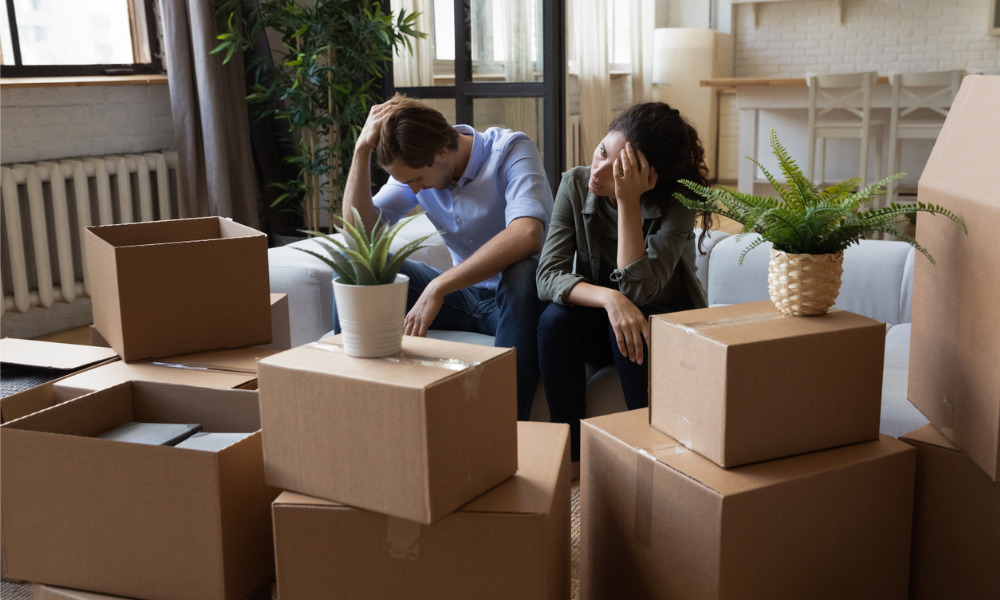
The cost of housing in the United States today is pressuring household budgets with many weakening their long-term financial security to keep a roof over their heads.
Overall, half of respondents to a recent survey by Redfin said they are at least sometimes struggling to meet their monthly rent or mortgage payments, with many making sacrifices as a result. These commonly include taking fewer vacations (35%), skipping meals (22%), or working extra hours or shifts in their job (21%).
Selling possessions and borrowing from friends and family are coping strategies used by one in five respondents and 18% have dipped into their retirement savings to pay for their housing, potentially damaging a growing desire to live a more fulfilling and passion-focused retirement as discovered in a recent poll from Fidelity Investments.
While still some way from the average retirement age, 14% of millennials are among those reducing their retirement pot to pay for their homes, weakening their retirement preparedness. While using up to $10,000 from retirement accounts for a first-time home purchase is usually tax-free for qualified buyers, for those tapping their savings for rent or monthly mortgage payments will face tax implications.
Baby boomers are most likely to be using retirement savings for housing costs (28%), followed by Gen Xers (16%). Many Gen Zers do not yet have retirement savings but 6.5% of those that do are dipping into accounts for housing costs.
The amount of retirement savings required has been a talking point recently with a survey suggesting the ‘magic’ number is $1.46 million - $1.65 million for millennials – but advisors refuted the findings and told InvestmentNews that having a dollar-figure goal can do more harm than good in retirement planning.
“Housing has become so financially burdensome in America that some families can no longer afford other essentials, including food and medical care, and have been forced to make major sacrifices, work overtime and ask others for money so they can cover their monthly costs,” said Chen Zhao, economics research lead at Redfin. “Fortunately, the country’s leaders are starting to pay attention, and homebuyers may get a reprieve in June if the Federal Reserve cuts interest rates, which would bring down the cost of getting a mortgage.”

DeepVest, Asset-Map and Aidentified launch automation that spots household gaps, wealth events and portfolio triggers for advisor sign-off
Eddie Brown says RIA executives need AI built for strategy and execution, not just advisor productivity
Independent advisors in Colorado, Texas and Arkansas join larger wealth management platforms through acquisitions and partnerships
The enforcement division wanted a full bar - the Commission went lighter
Welch brothers’ 93 Financial Group gives the Osaic-owned RIA a fifth greater Boston office, days after a $1.6B triple acquisition
Advisors are broadening the conversation beyond savings to help clients prepare for the realities of longer lives
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.

