Money accumulating in retirement accounts is increasingly being targeted by lawmakers to help people pay for other expenses, a trend that worries experts who say the funds should be left alone to address the looming challenge of retirement security.
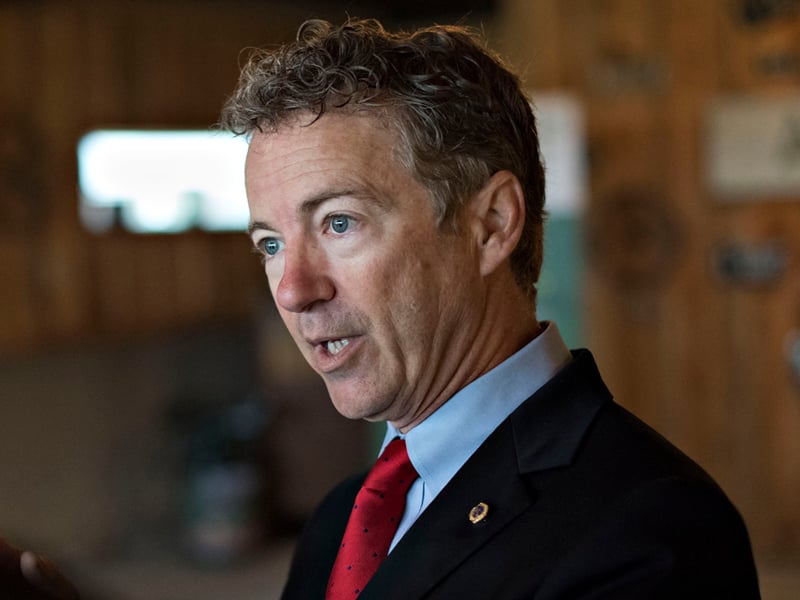
Sen. Rand Paul, R-Ky.,
introduced legislation earlier this week — the Higher Education Loan Payment and Enhanced Retirement (HELPER) Act — that would allow people to withdraw up to $5,250 annually from a 401(k) or individual retirement account without incurring taxes or penalties to pay back student loans or finance college. The funds also could be used to pay tuition for a spouse or dependent.
Another provision of the bill would let workers take employer contributions to their retirement plans as Roth contributions, or after-tax money, instead of taking the typical tax-deferred payments into the plans. Workers would then be able to withdraw the money after retirement tax-free.
A
fact sheet about the bill argues that withdrawing money from a retirement account to pay student loans would put more money in people's pockets than investing the same amount in U.S. bonds. In the example, the loan carries a 5% interest rate and the bond a 2% rate.
"We can empower the American people to reduce the burden of debt, realize the dreams they studied hard to achieve, and grow their retirement savings," Mr. Paul
said in a statement.
But using money from retirement accounts for anything other than financing post-work years draws skepticism.
"We do have a concern with ensuring Americans save for a secure retirement," said Will Hansen, chief government affairs officer at the American Retirement Association. "This bill could potentially increase the amount of leakage from retirement plans. Tapping into them for other reasons could have disastrous implications for individuals down the road."
A better way to address student debt is to refinance the loans at today's low interest rates, said Jamie Hopkins, director of retirement research at the Carson Group.
"I'm not in favor of using retirement money to cover short-term needs," Mr. Hopkins said. "It's the classic problem of robbing Peter to pay Paul."
Lately, retirement savings have become a piggy bank for other needs in the minds of legislators. Recently, Sen. Patrick Toomey, R-Pa., introduced a bill that would allow withdrawals to pay for long-term care insurance.
"It's where the money is today," Mr. Hopkins said of retirement plans. But "we've got to encourage automatic savings, more long-term investments, not taking money out to cover these other expenses."
[
Recommended video: Financial wellness, a holistic way to serve clients]
Burgeoning student debt also is capturing the imagination of lawmakers.
Mr. Paul's measure joins several others that have been introduced this year. It's not clear whether any will gain traction. One thing that could slow down Mr. Paul's legislation is the way he's proposing to pay down student loans.
"There would have to be a significant debate on whether the Paul bill increases retirement security or decreases retirement security," Mr. Hansen said.