
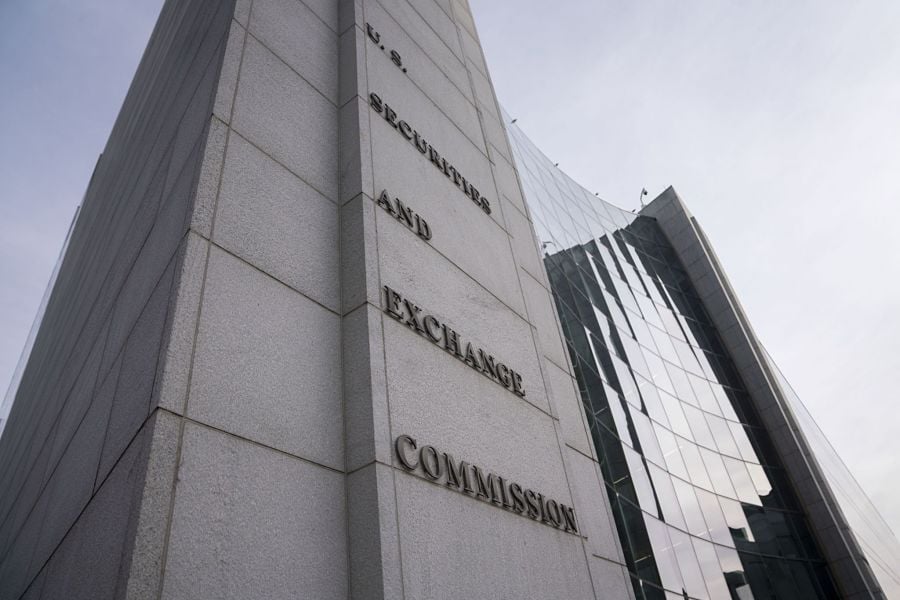
The Securities and Exchange Commission brought its third enforcement action against robo-advisers on Thursday, charging Emperor Investments, Inc. with making false and misleading marketing on its website and social media platforms about its performance and using paid bloggers to solicit U.S. investors without adequate disclosures.
Without admitting or denying the SEC’s findings, Emperor consented to a cease-and-desist order finding that it violated the antifraud provisions and will pay a $25,000 fine, according to the SEC.
“We should expect the SEC to pay more attention to robo-advisers, online investing platforms, and mobile investing applications going forward,” said Kurt Wolfe, an attorney at Quinn Emanuel Urquhart & Sullivan. “The misconduct alleged in this case is really just low hanging fruit. In the not too distant future, I think we’ll see the SEC take a closer look at how these firms deliver services.”
The SEC found that, from June 2018 until October 2019, Emperor stated that it had outperformed the market for the past 11 years when, in fact, the claim was based on modeled returns, and Emperor had been in operation for less than two years, during which time it underperformed the market. In its latest Form ADV filed September 26, 2019, Emperor reported assets under management of $621,000.
Emperor also allegedly paid bloggers, which were a significant source of Emperor’s new clients, for referrals without complying with cash solicitation disclosure and documentation requirements. The SEC alleges Emperor paid approximately $3,400 to these participating bloggers for referring new clients to Emperor and an additional $12,500 for blogger reviews.
“Emperor’s dissemination of false and misleading advertising and marketing materials and performance data, along with its failure to comply with requirements concerning the payment of bloggers for client referrals, was caused, in part, by its ineffective compliance program,” according to the SEC filing.
The Emperor Investments case pulls together threads that have seen in past SEC enforcement actions against robo-advisers including the 2018 charges against Wealthfront and Hedgeable: paying bloggers for referrals without disclosing the relationships, disseminating misleading marketing materials and performance data, and failing to implement adequate policies and procedures.
“The cases center on client communications, and really squeeze non-traditional advisory platforms into more traditional regulatory compliance buckets,” said Wolfe. “The staff isn’t yet testing the bounds of the securities laws or exploring innovative features of robo-advisory platforms.”
The case is an important reminder that advisers need to be careful when they include performance data in marketing materials, Wolfe said.
“It may be tempting to chart performance against competitors or a market benchmark, but for advisers with a relatively short track record — including many robo-advisers — it is critical to disclose the use of models or assumptions and make it abundantly clear if marketing materials do not reflect actual results,” he said.

Hendershott Wealth Management's Hilary Hendershott on turning a niche for women into an operating strategy, not a marketing pitch.

Iowa's Greenwood Wealth Partners exits D.M. Kelly as UBS and Ameriprise win Merrill Lynch recruits in California and Florida

Less than 1% of pool funds went to actual trading, CFTC says
Plus, SEIA builds a governed data foundation for its in-house AI and Snappy Kraken debuts a read-only marketing coworker for advisors.
He owes $364 million but pays $100 a month
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor
Northern Trust’s Ken Lassner shows advisors how to convert volatility into after-tax portfolio gains

