
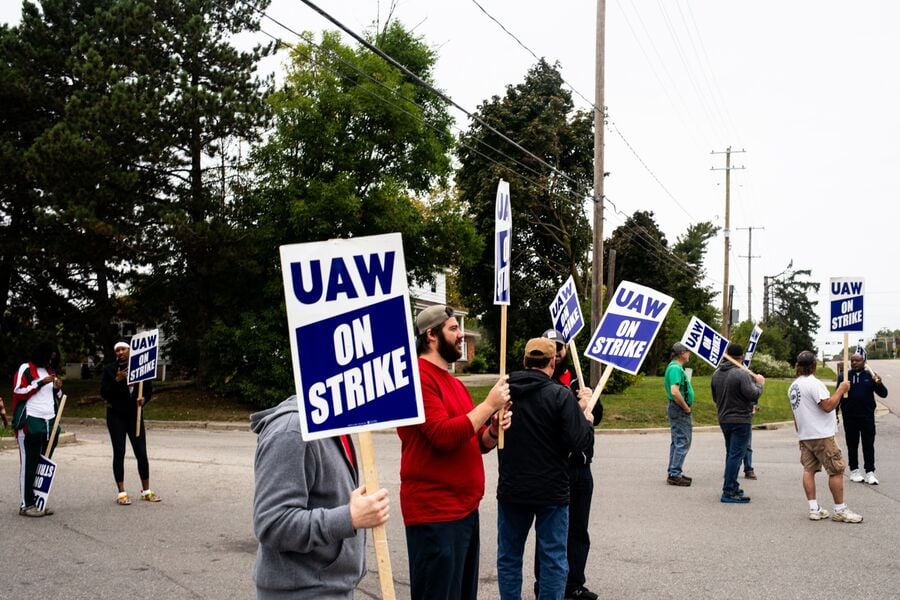
The United Auto Workers want something that most Americans don’t have: traditional pension plans.
It’s one of the union’s core demands that could help end the strikes at Ford, General Motors and Stellantis. But at a time when companies are trying to shed their financial liabilities for workers’ retirement security, some see it as a big ask.
UAW talks with those companies have reportedly negotiated wage increases broadly, but none of the big three U.S. automakers has budged on reinstating pension coverage to pre-2007 levels, according to coverage today by Reuters.
If UAW succeeded in getting pensions back, it would be a major victory, going entirely against a decades-long trend in U.S. retirement saving.
Not only do most private-sector companies no longer offer defined-benefit plans for new workers, but the majority are tempted to get existing pensions off the books. A recent survey by MetLife found that 89% of employers with pensions that have de-risking goals are planning to offload those liabilities to insurance companies in the form of group annuities. Over the past year, the rate of companies doing just that has accelerated at record pace as the funded status of their pensions has improved amid higher interest rates, making them eligible for pension-risk transfers.
“Overall, I seriously doubt that any modern firm would want to reinstitute DB plans, due to their high costs, including the high premiums that they would need to pay to the Pension Benefit Guaranty Corp (PBGC) for reinsurance. Moreover, DB plans skew their benefit payments toward long-term employees, penalizing anyone who leaves the firm early, needs to take time off for kids or other reasons, and who doesn’t work for the firm for a full career,” Olivia Mitchell, executive director of the Pension Research Council, said in an email. “This isn’t very appealing to many today, given the way the labor market has changed. Including deferred annuities in a 401(k) plan is, to my mind, a much more appealing way to provide secure retirement incomes for a modern workforce.”
In response to the UAW strikes that started last month, the automakers have noted that they provide 401(k) contributions for workers. As part of its negotiations with UAW, Ford has agreed to increase contributions by an unspecified amount, according to a report Monday by Detroit Free Press. GM told the publication that it contributes an equivalent of 6.4% of pay for hourly employees, while Stellantis indicated that it provides an automatic contribution and subsequent matching contributions.
It's hardly news that defined-contribution plans like 401(k)s are the norm, as the burden of saving and investing for retirement is now almost entirely on the shoulders of workers, rather than the companies that employ them. As of March 2022, 15% of private-sector workers had access to traditional pensions, compared with 86% of state and local government employees, according to data from the Bureau of Labor Statistics. Meanwhile, 66% of private-sector workers have defined-contribution plans offered by their employers, and about half of them participate.
Total money in defined-contribution plans reached $10.2 trillion as of the second quarter, up from about $6.5 trillion in 2015, according to figures from industry group the Investment Company Institute. Over that period, assets in private-sector defined-benefit plans increased from $2.9 trillion to $3.2 trillion.
Whether workers, including those at UAW, would be better off with pensions or 401(k) plans depends on various factors, including income level, savings ability and, as Mitchell noted, whether they stay at one company for most of their careers. But for many — particularly lower- and middle-income workers — pensions offer a sense of security that 401(k)s have only recently started to try to replicate. Not only do people not have to worry about outliving their investments with a pension, but the employer is responsible for ensuring the plan is solvent.
Annuities can address that uncertainty for those without pensions, but in most cases people must also research and purchase complex products and ensure during their working years that they directed enough income to a 401(k).
While employers simply don’t want to have to worry about being responsible for workers’ retirement security, there's some research showing that pension plans give them a better bang for the buck than 401(k)s. The data, from pension advocacy group the National Institute on Retirement Security, show cost savings ranging from 27% to 49% for employers that provide a pension rather than a 401(k), as a result of higher investment returns, more diversified portfolios and longevity risk pooling.
“Pensions have economies of scale and risk pooling that just can’t be replicated by individual savings accounts,” NIRS executive director Dan Doonan said in a statement at the time the report was published.
“At the same time, 401(k)s have made significant progress in recent years when it comes to reducing costs and making investing easier for individuals," Doonan said. "But the post-retirement period remains difficult to navigate for those in a 401(k) account. Retirees are transitioning from saving to spending down their retirement income at the right rate, so they don’t outlive their savings.”

What if one investment decision could create tax-saving opportunities across your entire portfolio? Chris Vizzi shares how the Stacking Strategy helps investors align tax planning, portfolio construction, and wealth preservation to maximize long-term outcomes while keeping more of what they earn.

Buyers spending on AI may treat less efficient sellers as overstaffed and price the cost of rightsizing into lower offers

Kenneth Leech pleaded guilty in June to one obstruction charge, and could face six to 12 months in prison.

Launch of Direct AI follows a model portfolio tie-up with Envestnet as advisors juggle AI adoption and private-market due diligence.

Meanwhile, Cetera's streak of Commonwealth recruitment continues in Washington, and an LPL advisor hops over to Raymond James in Maine.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

