
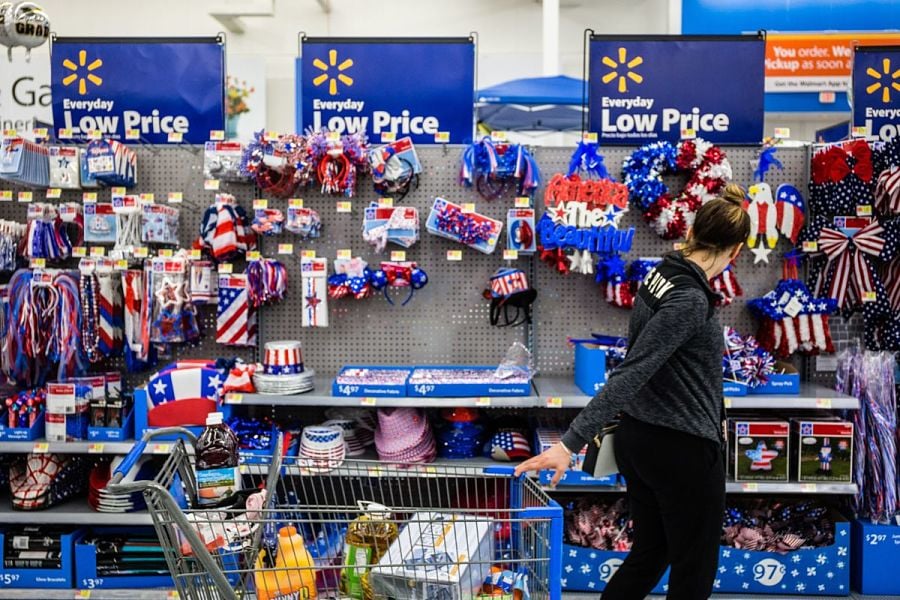
Walmart Inc. has announced a new fintech platform that officially offers digital financial advice, but the largest retailer on the planet doesn't have its sights on your clients' assets.
The retail giant released plans back in January to use its brick-and-mortar footprint to offer financial services to the company’s 220 million weekly customers, most likely through banking services like credit cards and checking accounts. At first, the announcement felt like just the latest corporate goliath to offer simple financial products: Apple Inc. launched its own branded credit card in 2019, and later that year, Alphabet Inc.'s Google said it would look to partner with Citigroup Inc. to offer checking accounts.
Next, a surprising tidbit appeared in an application at the U.S. Patent Office.
Walmart revealed in a trademark filing that it intended to launch a full-fledged financial advisory platform to help clients build a better relationship with money. Through a partnership with Ribbit Capital — the venture capital firm behind Robinhood — the digital offerings will include financial advice, consultancy services, financial portfolio analysis and research.
The idea of a massive corporation reaching millions of potential clients with a cheap investment product certainly keeps advisers up at night. Ron Carson has often been on record saying Amazon.com Inc. is one of the gravest threats facing advisers today. With their massive scale and brand loyalty, the FAANGs (Facebook, Amazon, Apple, Netflix, Google) easily have the potential to upend wealth management.
The question is, do they have incentive?
It’s becoming fairly obvious giant corporations just aren't really interested in your book of business. The barriers to enter wealth management, mostly regulatory, are so daunting that it seems unlikely any company will find it practical to dive in. Especially when navigating complex financial regulations hasn't historically been part of a company's DNA.
There’s simply lower-hanging fruit, like bank accounts and credit cards that are more suited to middle-class America, and almost every big corporation on the planet is happy doling them out.
The move is eerily similar to another retail giant of yesteryear, however. Sears was once the largest retailer in the world and had its hands in a number of disparate industries including financial services. The company purchased Dean Witter Reynolds Organization Inc., a stockbroker, and at one point or another, even reportedly sold houses through its catalog, which seems like a logistical nightmare today.
Unfortunately for Sears, financial advisers weren’t interested in going after its middle-market clientele, just as people are no longer interested in building their next home with their bare hands. The company announced the sale of Dean Witter to Morgan Stanley in 1997 and its other business lines, like the real estate company Coldwell Banker, met similar ends.
Ironically, after helping to usher in Sears’ demise, Walmart now seems to be following in its footsteps. Walmart began forays into other business lines — most notably health care, popping up clinics in stores in 2019. There's also an insurance company to help clients sign up for Medicare.
The big advantage for Walmart is that it can bank on the experiences of other firms, like Google, Apple and others, that have already flirted with the idea of entering wealth management. While hindsight is 20/20, Walmart is more likely to target lower-income Americans with simple but necessary financial products like checking accounts.
Your advice relationships are safe — for now.
Sam Altman says market debut would be ‘ill-advised’ but Anthropic chases a $2 trillion valuation despite calls for AI development pause.
DFO Management is in advanced talks to acquire the Tampa-based insurance brokerage at a premium to its current market value.

Daejon Love and Taylor Chan's $1.3 million romance fraud scheme exposes how AI search engines can be manipulated by fabricated online identities

“It was a third party scam,” said the attorney representing the claimants.

Meanwhile, &Partners draws another Commonwealth practice, and Wealthcare welcomes a $550 million planning practice in the Northeast.
Northern Trust’s Ken Lassner shows advisors how to convert volatility into after-tax portfolio gains
Dan Biagini of American Equity says the steady decline of pensions, longer lifespans and a reset in interest rates are rewriting how advisors build retirement income

