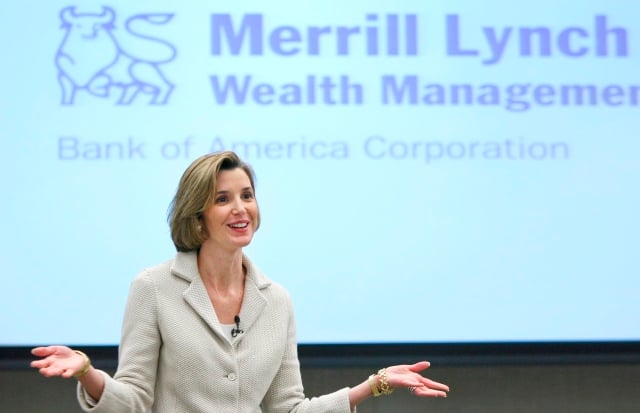
Rumors of waves of advisers leaving the wirehouses for the independent-broker dealers are greatly exaggerated. Or at least, that's the view of Sallie Krawcheck, the head of
Bank of America's global wealth and investment division.
During a speech at the Investment Company Institute General Membership meeting on Thursday, the BofA exec and former
Citigroup CFO discussed the state of wealth management. In the process, she touched upon the perception that wirehouse reps are joining indie B-Ds in droves. “Last year we didn't lose thousands. And we didn't lose hundreds,” she said. “We lost 36 and we hired 25 from the independents.”
Ms. Krawcheck, who last week named John Thiel to head the Merrill Lynch brokerage, also dispelled the notion that large numbers of clients are leaving the firm. She noted that client attrition is at a record low —in the single digits.
The BofA wealth management boss also addressed the fiduciary standard, a hot topic on Capitol Hill and among advisers these days. Ms. Krawcheck said that while lear differences do exist between registered investment advisers and brokers, separate standards of care are confusing for investors. “We have a historic opportunity to go further,” with defining a fiduciary standard for all advisers, she said.
Ms. Krawcheck went on to talk about certain terms in the industry that give investors the idea that they may not be serving their best interest. She called on the fund industry to ban the word “retail distribution,” when talking about wealth management services.
The term retail distribution gives the sense that the financial advisers live to “serve you,” she said, “not serve the client.”
Instead, she proposed using the term “private client solutions." She added: “So you can all change your business cards.”
Ms. Krawcheck declined to provide her views on other proposed regulations such as the reform of 12(b)-1 fees, but she did ask that firms are given enough time to comply with any changes in the rules. “Anything that provides our market with greater confidence and clarity is good for clients,” she said “As we make these changes we just need some time. We can do a lot of stuff in years and much less in months.”