
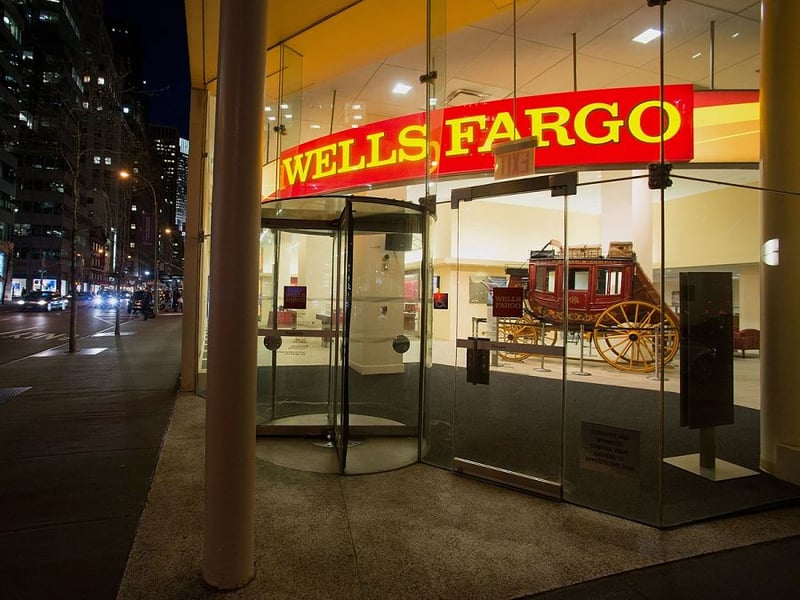
Wells Fargo & Co. said the Office of the Comptroller of the Currency terminated a 2016 consent order tied to a fake accounts scandal that plunged the bank into years of regulatory and management turmoil.
The order required Wells Fargo to revamp how it offers and sells products and services to consumers and take other steps to protect its customers and employees. The OCC said in its termination that the bank’s compliance with laws and regulations means the order no longer needs to be in place.
“I have repeatedly said that implementing a risk and control framework appropriate for a bank of our size and complexity is our top priority, and closing consent orders is an important sign of our progress,” Chief Executive Charlie Scharf said in a statement Thursday. “This is the sixth consent order that our regulators have terminated since 2019.”
Shares of the company climbed 5.4% to $51.14 at midday in New York.
The consent order was imposed in response to revelations that the San Francisco-based bank was creating accounts for customers without their permission. A series of scandals followed that also resulted in a cap on growth from the Federal Reserve. Wells Fargo executives expect that restriction to stay in place into next year.
The consent-order termination “moves Wells Fargo a little closer to getting the Federal Reserve’s asset cap lifted, but we don’t think it’s quite there yet since a few other consent orders are still outstanding and scrutiny lingers over the bank’s financial controls,” said Elliott Stein, a senior litigation analyst with Bloomberg Intelligence.
Investigators found that the company set overly aggressive sales targets that led employees to open millions of fake accounts for customers to meet goals, often by creating false records or misappropriating their identities, generating millions of dollars in fees and interest and damaging some clients’ credit ratings, according to the Justice Department.
In September, the bank settled a $1 billion shareholder lawsuit over the unauthorized accounts that brought the total amount the company has agreed to pay to resolve related claims to almost $5 billion.
The scandals also claimed two CEOs. Scharf succeeded Tim Sloan, who took over Wells Fargo weeks after the scandal erupted at the firm. John Stumpf, his predecessor, who had run the bank since 2007, stepped down amid intense scrutiny from Washington and beyond.
Also, CAPTRUST adds a $300 million planning team from Sanctuary in its home market of Raleigh, and Sequoia Financial Group buys a Boulder family office.

New nonvoting shares would let the Meta CEO cover eyed Proposition 40 tax without losing control, in exchange for an eight-year residency pledge
New research exposes a wide gap in how affluent parents and their adult children understand and prepare for the transfer of family wealth.
A new AIC report finds a 13.2% median annualized return over 10 years, outpacing public equities, real estate, and fixed income.

Most Americans entering retirement lack a realistic picture of what health care will actually cost them and advisors may be their last line of defense.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

