
Financial advisory firms that still treat artificial intelligence as a chatbot waiting for a prompt are missing the technology's biggest payoff, according to executives at three wealth management technology providers. They say the next phase belongs to agentic AI running in the background of the firm.
Agentic AI refers to systems that carry out multistep tasks on their own instead of simply answering questions. At an advisory firm, that could mean software that flags data inconsistencies, generates reports and pushes action items forward without anyone typing a request. Operations staff supervise the work, and advisors handle the client.
The shift is arriving as adoption accelerates. In a May 2026 survey of 201 U.S. advisors by Morning Consult and Edward Jones, 82% said they already use AI in their practice. Large firms are moving too. In June 2026, Rockefeller Capital Management teamed up with Anthropic to build an AI-enabled wealth management platform. Regulators are paying attention as well. The Financial Industry Regulatory Authority's 2026 Annual Regulatory Oversight Report, released in December 2025, addressed AI agents for the first time and urged firms to define human oversight procedures.
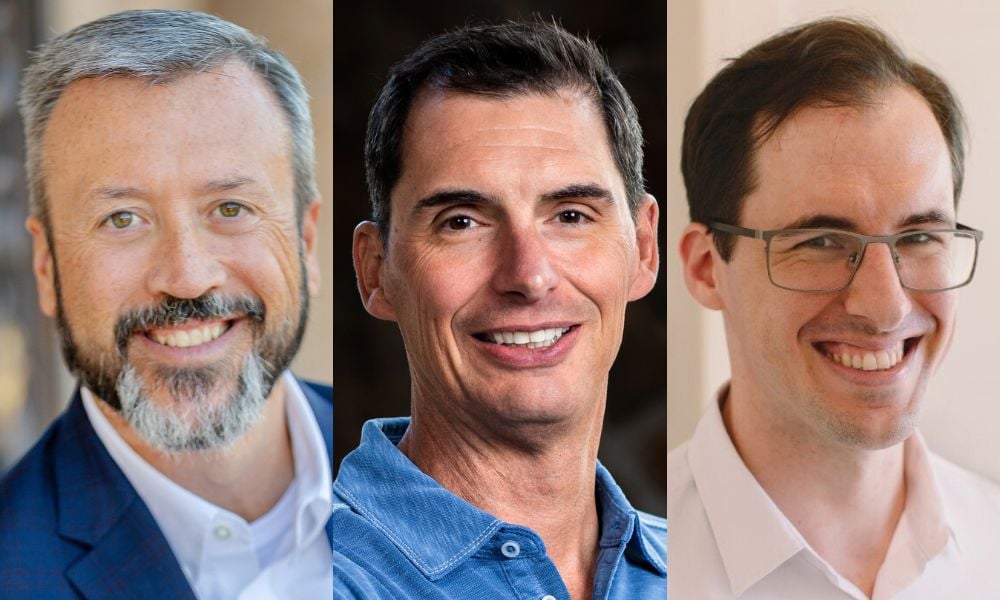
Joe McQuaid, chief operating officer at Concurrent, said firms should begin with work that is repeatable, rules-based and already mapped to a defined process. He named meeting follow-ups, portfolio surveillance, account-opening paperwork and compliance pre-review as strong candidates.
"The shift isn't about buying a smarter chatbot. It's about building the operating layer, connected data, governed access to firm systems, and a library of skills and workflows that run without someone having to type a prompt," McQuaid said. "The firms that win will move from reactive prompting to automated workflows that surface the right action to the right person before they go looking for it."
Conor Curtis, head of product at Practifi, likewise points to recurring workflows where a missed step creates a service gap, such as onboarding, annual reviews and post-meeting follow-up. Before automating anything, he said, a firm must define what triggers the process, who owns it, what completion looks like and which actions need approval. He sees the CRM as the natural foundation for that access, and probably the home for the AI itself.
"Firms should expand autonomy as they demonstrate reliable execution, rather than treating it as an all-or-nothing decision," Curtis said.
Gene Farrell, chief executive of Vanilla, draws a sharper line between two words that are often used interchangeably. Proactive AI is where firms should head, he said. Autonomous AI, meaning an agent that makes and acts on decisions with no human involved, is a different conversation for fiduciaries, and he doesn't expect clients ever to accept an AI agent as their fiduciary.
"Accountability has to sit with someone who has judgment and a relationship with the client," Farrell said.
In estate planning, he said, that means agents that review an advisor's book and flag issues worth a conversation, such as a rental property titled outside a trust or a change in state estate tax law. The advisor then decides what reaches the client. Farrell also warned against tool sprawl and urged firms to map their core workflows before buying technology. "One firm told me recently that their advisors use something like 34 different tools," he said.
All three executives separate AI that makes one advisor faster from AI that changes how the whole firm runs. That distinction is showing up across a wave of AI-powered tools reshaping the wealth management tech stack.
Farrell noted that two advisors at the same firm can get very different results from the same tool, depending on how well they prompt. The firm, meanwhile, has limited visibility into how client data is being used.
"There's a saying from my Amazon days that there's no compression algorithm for experience. I believe firm-level AI is the closest thing to one," he said.
McQuaid said firm-level AI needs four things:
"One advisor's prompt is a personal win, but that same prompt turned into a vetted, governed, firm-wide skill becomes institutional capability that compounds," he said.
For Curtis, the test is whether a meeting summary turns into assigned, tracked tasks, backed by shared permissions and an audit trail.
"The measure of success shifts from minutes saved by one advisor to whether the firm delivers timely, consistent service across its client base. This distinction matters since service levels, not efficiency, is where firms compete," he said.
The executives agree that data gathering, reconciliation, document review, monitoring and first drafts belong in the back office. Advice and difficult conversations stay with people.
"Advice, empathy, and difficult conversations belong to the advisor, and AI's job is to make those moments better informed, not to replace them," McQuaid said. "When this is done right, clients don't experience 'AI.' They experience an advisor who is more prepared, more responsive, and more present."
Farrell pointed to the Edward Jones research as support for that split. In separate studies showing AI use reshaping advisor satisfaction, 59% of advisors said they want AI to automate administrative work such as meeting preparation. Another 68% said long-term client trust still requires a human touch. Farrell added that calculations should run on deterministic engines so the numbers are right.
"AI still makes mistakes, and it's very difficult to hold an agent accountable when it gets something wrong," he said.
Curtis said oversight should match the stakes of each action. "Firms should set approval requirements according to the consequences of an action, giving routine internal tasks more latitude and requiring review for sensitive client communications or consequential changes," he said.
Advisors must navigate misinformation and generational expectations as technology reshapes client relationships.
The regulator has been trying to reach imprisoned advisor Jason Foley.
Magnificent 7 firm continues to ‘right size’ workforce in AI-related shift also seen in financial services.
Healthcare inflation running at 280% of CPI - and most HSA holders are sitting in cash.
New research identifies the practice habits driving 121% DC AUM growth among the industry's top performers.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

