
January is often referred to as “Divorce Month,” as many couples untie the knot after the holidays and New Year’s reflection.
If that’s the case, then February should be “Call Your Advisor Month” for those folks who finally sign divorce documents and split up. That’s because dividing assets and navigating child-related expenses creates vast financial implications they may not have foreseen when they officially called it quits.
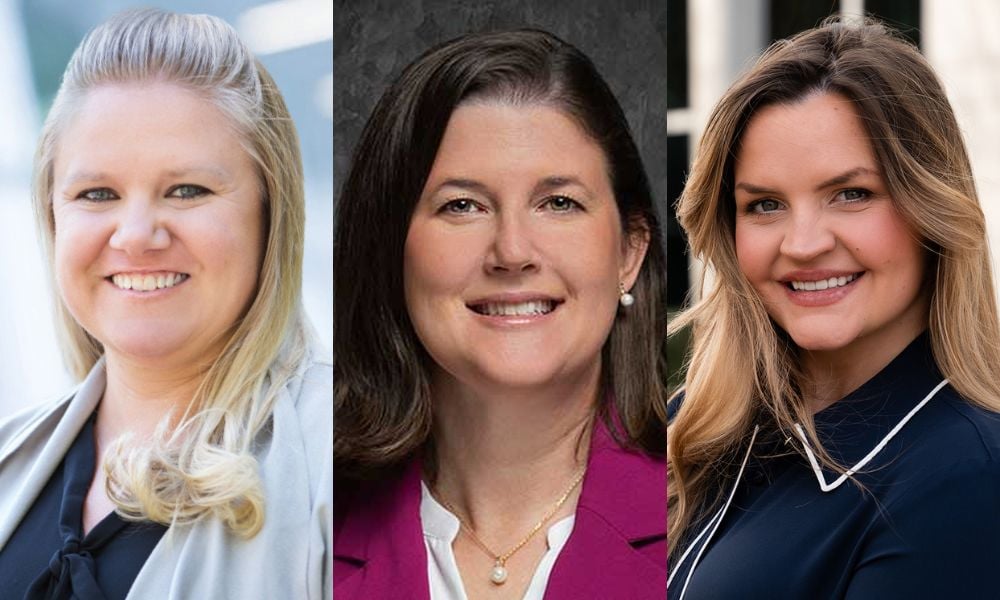
Megan Miller, senior wealth advisor and managing director at MAI Capital Management, says the biggest mistake she sees people make is anchoring to a certain asset. In her experience, many people create a mental list of non-negotiables before they have all of the information.
“By making the assumption that at all costs, you will keep the house or maintain your pension, for example, it creates a disadvantaged position in the negotiation from the very start,” Miller said.
To avoid such problems, Miller runs full financial projections for clients both during and after the divorce is finalized to ensure that they are aware of their sustainable path forward based on the proposed settlement. This includes tax assumptions, income needs and future implications of each asset and liability.
Along similar lines, Jackie Schlup Daniels, principal at Mercer Advisors, says the biggest mistake she sees is when a client does not have a budget or plan for moving forward financially, especially if they receive temporary awards such as child or spousal support.
“Before settlement, we review the tax implications of the options presented and, depending on the stage of life and needs of the client, make sure that those implications are considered as part of their broader plan for the future. The earlier we can talk about tax strategies with the client and attorney, the better prepared we can be for post-divorce planning,” Daniels said.
Crossan Ryals, wealth manager and co-founder of Ryals Group Wealth Management, meanwhile, points out that many women take a backseat role in financial decisions and suddenly find themselves without a plan. This is why she finds both parties being well informed on finances paramount.
“I focus on providing clear, straightforward information about how different assets are taxed and how they fit into a long-term plan. When appropriate, we explore a QDRO, or Qualified Domestic Relations Orders, to transfer retirement assets properly and avoid penalties. We also review rollover options, future tax exposure, and, when applicable, bring in a CPA to provide further expertise,” Ryals said.
THE ALL-IMPORTANT FIRST 90 DAYS
The best thing a newly-divorced person to do in the first 90 days post-separation, according to MAI’s Miller, is to gather all the financial information they can find. That also means making copies of statements of all applicable assets, marital and separate, and keeping a log of where those assets and debts are held. The other critically important thing is to start saving money.
Stressed Miller: “Even amicable divorces are expensive and require available cash.”
Some other key steps that need to be taken quickly include updating beneficiaries on life insurance and 401k plans, updating the estate plan, and removing the spouse from joint items such as the car or deed on the home.
Speaking of the familial home, Ryals says one of her first priorities is creating a realistic budget and cash-flow plan as it concerns the client’s domestic finances. This helps them understand what their new financial life looks like and how their money needs to work for them going forward.
“We look at housing decisions, whether a move is necessary, how much liquidity they need, and how settlement assets should be positioned. This includes determining whether funds can be rolled over to avoid taxes or whether some money will be needed immediately for living expenses,” Ryals said.
MORE THAN FINANCIAL SUPPORT
The post-separation period is not just a time for advisors to offer financial guidance to newly-divorced clients, it’s also when they can provide emotional support during a high-stress life event.
Miller points out that financial advisors are in a unique position of full access to financial pictures, which is often one of the biggest sources of stress for a client who is going through a divorce. But while holding space for their emotional reaction is important, she highlights the fact that she is not a trained therapist and some boundaries must not be breached.
“Being able to walk a client through the monetary implications of a divorce is often a very empowering step forward which assists with emotional empowerment as well,” Miller said.
Mercer’s Daniels echoes the sentiment, saying advisors can provide a sense of calm and a feeling of confidence when it comes to helping clients through a divorce.
“An experienced advisor has helped many people through a divorce and can help provide an understanding and objective perspective, while this is a new and very difficult experience for the client. Providing sound guidance and emotional understanding through the process allows the client to feel more confident about the decisions they are making and their life going forward,” Daniels said.
Finally, Ryals stresses the need for an advisor to build trust with a client before the fact so they can be present in the moment when emotions run high.
“Coming prepared with clear options and a structured plan to that initial meeting post-divorce helps the client to feel seen and heard. By managing the financial details, I allow them to focus on healing while knowing there is someone in their corner with their future in mind,” Ryals said.
The 70% time savings I expected from AI hasn't fully arrived, but the quality of our advice and our private markets platform have changed.
The J.C. Flowers-backed investor’s latest RIA deal adds five next-gen leaders to the Massachusetts firm’s ownership ranks
Meanwhile, UBS and Raymond James talk recruiting.
Elderly clients lost about 70% after a South Carolina advisor held inverse ETFs for 798 days on average, the regulator says
The new chat feature is expected to launch in 2027.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

