
Fidelity Investments is handing its smallest registered investment advisor clients a decision many have put off for years: get bigger, join someone bigger or leave.
In notices sent to advisory firms last week, Fidelity told RIAs holding less than $100 million in client assets on its platform that they have until June 30, 2027, to clear that threshold or start moving those assets to another custodian. The $100 million custody minimum already applied to new RIAs; this is the first time Fidelity has extended it to existing relationships.
Few large alternatives exist. Fidelity ranks second among RIA custodians behind Charles Schwab, and Cerulli Associates has estimated that four firms – Schwab, Fidelity, BNY Pershing and LPL Financial – control nearly 85% of the U.S. custody market.
The number carries regulatory weight. Under the Investment Advisers Act of 1940, $100 million in regulatory assets under management is generally the point at which an advisor moves from state registration to registration with the Securities and Exchange Commission. The Investment Adviser Association and compliance firm Comply counted more than 20,500 advisors registered with states or otherwise exempt from SEC registration as of June 2026.
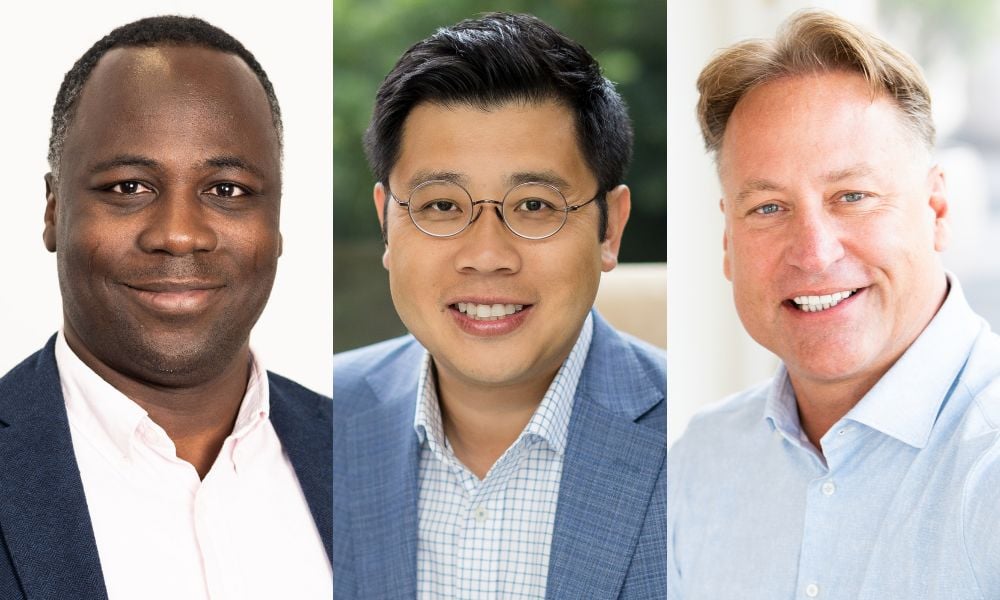
Tony Ling, managing partner at Rise Growth Partners, an Austin, Texas-based firm that takes minority stakes in RIAs, said the economics of serving small firms have been under strain across the industry for years. Custodians make money on scale, he said, and a $40 million RIA can cost nearly as much to service as a $400 million one.
"I don't read this as a verdict on whether smaller RIAs can provide strong service to clients; plenty of them do. But it does signal that sub-scale firms can no longer assume the infrastructure around them will remain inexpensive or easy to access. That puts a greater premium on being agile and forward-thinking," Ling said.
Allen Darby, CEO of Alaris Acquisitions, a Charlotte, North Carolina-based M&A advisory firm for wealth managers, read the move more bluntly. He sees it as a sign that smaller wealth businesses are not considered worth the time and resources.
"We think there will be a market for smaller firms to exist; it's just they won't be able to deliver the same degree of service, expertise or experience to their clients that larger firms provide. They will essentially be resting on their relationships as the central reason clients should retain them, which in our opinion is an incredibly bad business decision," Darby said.
Ola Abdul, founder and CEO of London-based wealth platform Fundment, rejected the idea that small firms are inherently uneconomical to serve. In his view, the minimum says more about a custodian's cost base and risk appetite than about the advisor's business.
"Custody assets themselves are not what consumes capital; leverage, settlement exposures and operational complexity do. Modern technology has transformed what it costs to serve a $40 million firm. The minimum is a choice, not a law of economics," Abdul said.
Affected owners have three broad paths, and none is free. Moving to one of the RIA custodians beyond the Big 3 is the most direct fix, but Ling warned it may only treat the immediate symptom. Repapering every client account takes time, can test client goodwill and offers no guarantee the problem will not return. Growing independently preserves control, but only if owners can add assets fast enough without straining a lean team.
"Joining a larger platform solves the scale issue, but the tradeoff is usually some combination of ownership, brand and decision-making. The key is taking the time to find the right platform and a leadership team that shares your values and approach before you sign," Ling said.
Abdul cautioned against letting a custody change drive strategy.
"Don't sell your independence to solve a paperwork problem. Changing custodians is a one-off project with real costs, mainly client communication and staff time, but done well it takes weeks or months, not years. Racing to $100 million just to keep a custodian is the wrong reason to grow. And joining a larger platform swaps a temporary transition headache for a permanent loss of control, assuming the platform even wants you, which for many sub-$100 million firms it won't," Abdul said.
Fidelity's timing lands in an already crowded deal market. RIA dealmaking is racing toward a record pace, with Echelon Partners projecting about 500 transactions in 2026. Fidelity's own data shows buyers favoring scale. Its midyear review found that acquired RIA assets nearly doubled to $343 billion in the first half, even as deal count fell 9% to 120 transactions. The median acquired firm managed $630 million.
Ling expects the minimum to fuel consolidation because it forces a decision many owners have deferred. He said firms can still stay independent if they accept the tradeoffs.
"Staying independent at a smaller scale could mean reduced service from certain providers, higher costs or more operational friction. It will also require firms to lean more heavily on technology and AI to create efficiencies. That comes with an upfront investment, in both dollars and leadership attention, that some owners will be willing to make and others won't. There could also be a positive outcome for clients. For sole proprietors in particular, this may accelerate the need to put a thoughtful long-term succession plan in place," Ling said.
Darby said joining a larger firm need not mean surrendering independence, since many large firms are themselves independent RIAs. Cheaper technology will put once-exclusive capabilities within reach of smaller practices, he said. But many owners of comfortable lifestyle businesses have little incentive to invest in systems built to outlast them. He expects technology to speed consolidation unevenly, with a substantial number of owners content to stay small and serve existing clients until they retire.
Abdul expects a bump in deals from owners already weighing a sale. He does not expect a retreat from independence, since most small-firm founders chose it deliberately.
"Small firms aren't the problem; expensive infrastructure is. Firms that find a custodian built to serve them profitably, rather than merely tolerate them, will adapt and thrive," Abdul said.

New F2 Strategy research finds more firms growing without M&A, yet one-third still lack a defined growth process.
Shadow AI, weak oversight, and no formal policy highlight why advisory firms are more exposed to cyber risk than they realize.

Meanwhile, DPL Financial Partners adds two annuity executives and Prime Capital Financial hires a Mid-Atlantic retirement plan consultant.

Andrew Komarow pleaded guilty Thursday in federal court in Hartford to defrauding three financial services companies of close to $3.3 million.

Elsewhere, Cetera picks up a $210 million Connecticut team from MML, while Wells Fargo FiNet adds a San Diego family practice from LPL.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

