
Although downsizing may save money in the long term, it isn’t a cheap exercise. Reports have emerged that leading American financial institutions have shelled out upwards of a billion dollars on termination pay in the first two quarters of this year. This pain is a repercussion of Wall Street's overaggressive expansion strategy during the Covid-19 pandemic.
On Wednesday, Goldman Sachs, severely impacted by a slump in trading and investment banking, was the latest banking behemoth to announce a financial hit due to recent staff retrenchments. The bank disclosed it had incurred $260 million in severance-related expenses during the year's first half. Goldman has dismissed around 3,400 personnel, which is approximately 7% of its total workforce, this year.
A day earlier, Morgan Stanley, which has already terminated about 3,000 of its employees this year, revealed that it had paid over $300 million for staff layoffs, including nearly $80 million to wealth management employees. Meanwhile, Citigroup declared last week that it had spent an additional $450 million on severance pay. The bank announced in the previous month that it was nearing the completion of 5,000 job reductions.
Options Group's Michael Karp, a prominent Wall Street recruitment specialist, told The Financial Times that more workforce adjustment is likely in investment banking. He predicted, "For the remainder of the year, many of the larger firms will likely follow a dismiss-two-recruit-one approach."
Several Wall Street companies now admit they expanded their workforce excessively during the pandemic to keep up with a surge in trading and deal-making activities, even as remote working affected efficiency.
The drastic shift from boom to bust in recent years has been remarkably swift, even by investment banking's cyclical standards. More 11,000 layoffs have been collectively announced by Wall Street's largest employers this year.
There is a split among executives on whether more layoffs and resulting severance payments will be needed as the year advances.
Morgan Stanley's CFO, Sharon Yeshaya, told analysts this week that the bank anticipates benefiting from a backlog of deals and plans to "augment our reach to optimally exploit the opportunity."
Conversely, Goldman's CEO, David Solomon, said the bank would initiate another round of performance-based layoffs, a practice that was paused during the pandemic but reinstated last year. However, Solomon noted there were "no concrete plans for workforce reduction presently."
Citi has hinted at potential future layoffs. Citi CEO Jane Fraser told analysts last week, "As we advance through the latter half of the year, we will concentrate on further reducing our expenditure through a more streamlined organizational model."
Wells Fargo informed investors that it expects its workforce, which has already shrunk by 5,000 this year and 40,000 since mid-2020, to continue to decline. This bank was among the few that did not grow during the pandemic, partly due to an imposed regulatory asset limit following multiple legal and compliance violations.
Based in San Francisco, Wells Fargo, whose business leans more towards consumer banking than deals and trading, has hiked its expense forecast for this year by $800mn. Most of this hike is attributed to layoffs, though the bank did not reveal the exact costs already incurred.
On Tuesday, Bank of America stated that it had eliminated 4,000 roles, about 2% of its total workforce, in the second quarter. BofA has primarily relied on natural attrition, thereby avoiding massive severance payments.
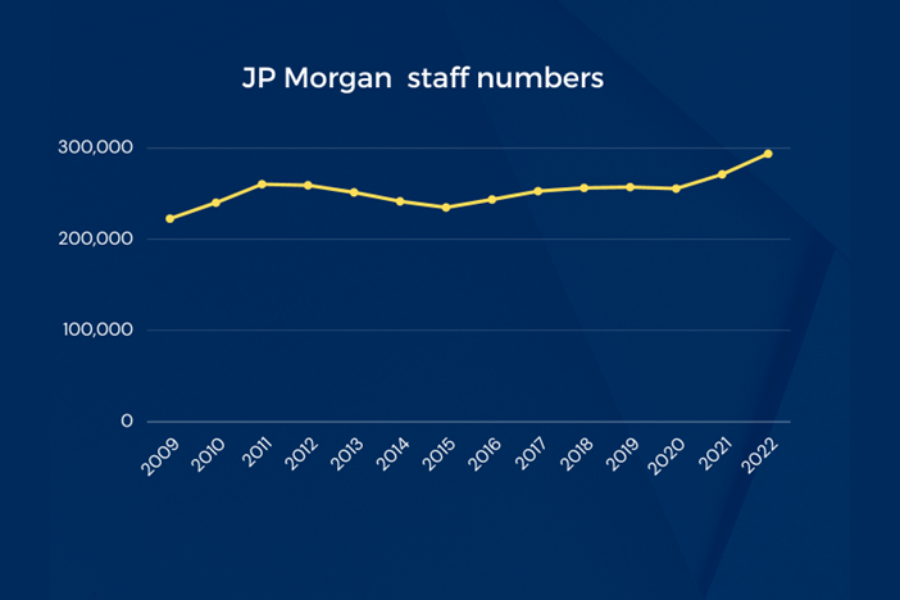
Standing out from the crowd, JPMorgan Chase, the country's largest bank in terms of assets with extensive retail, investment banking, and trading operations, increased its workforce by 8% to 300,000 in the second quarter. This doesn't include the employees from First Republic, the California-based lender it acquired in May, whose employees officially joined JPMorgan in July.
First-half job cuts;
Bank of America 4,000
Citigroup 5,000
Goldman Sachs 3,400
Morgan Stanley 3,000
Wells Fargo 5,000

The financial advice industry has been facing inquiries into its cash sweep programs for years now.

Investor money allegedly went to strip clubs, exotic cars, and landscaping

Procyon adds $415 million in assets under management in New Jersey while Savant picks up a $213 million Southern California planning firm

With a growing number of real estate-rich Baby Boomers aging into retirement, some advisors may be failing to consider all the options available for those clients' assets.

Cornerstone Advisors study reveals compliance bottlenecks stall campaigns weeks after customer opportunities close.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor
Northern Trust’s Ken Lassner shows advisors how to convert volatility into after-tax portfolio gains

