
Only 16% of Americans say they feel very knowledgeable about what healthcare will cost them in retirement, according to a D.A. Davidson survey released in March 2026 – a blind spot that advisors say leaves clients exposed to one of the largest and least predictable line items in a retirement plan.
The survey, conducted online by Big Village from February 13 to 15, 2026, among 1,006 US adults, found that 78% of respondents are worried about how rising medical costs will affect their retirement. Yet only 48% have built those costs into their planning, and just 23% have ever raised the topic with a financial advisor. Six in 10 said they had already watched someone close to them struggle to pay for care in retirement.
The price tag keeps climbing. Fidelity Investments' latest Retiree Health Care Cost Estimate puts the average lifetime bill for a 65-year-old retiring in 2026 at $185,500, a 7.5% increase from the prior year – and that figure excludes long-term care.
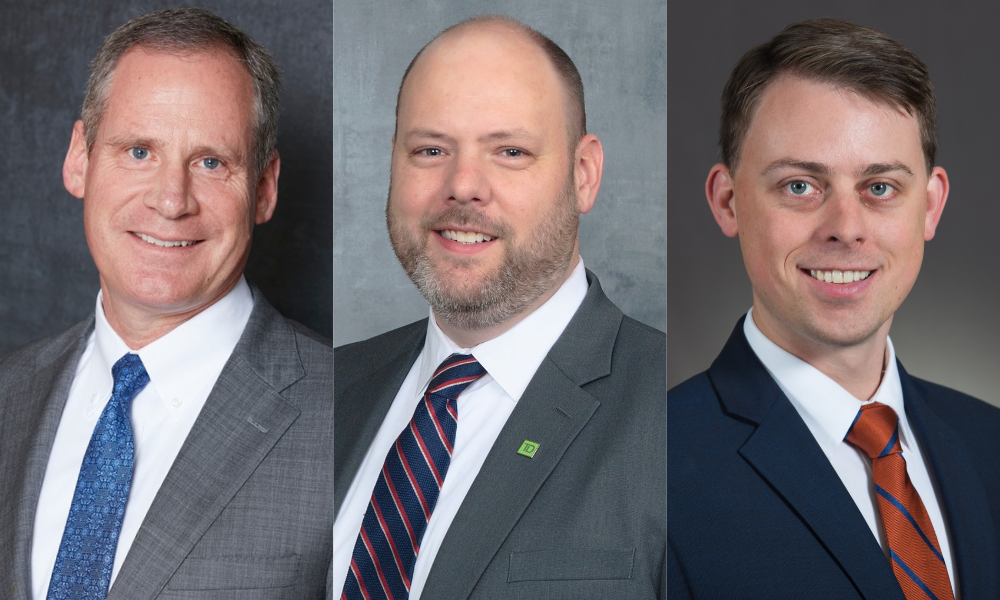
Andrew Crowell, a financial advisor and vice chairman of wealth management at D.A. Davidson, said clients who are young and healthy find it easy to push the issue aside because they rarely picture a worst-case scenario.
“I see it all the time. But waiting too long to plan for future healthcare expenses can severely impact a retirement strategy. One of the best tools we have against far-off costs like these is the power of compound interest over time,” Crowell said.
He argued that small, steady contributions matter more than many savers assume. “Many folks think that if they aren’t contributing large sums of money every month, it isn’t making a difference. But in fact, even $25 a month invested strategically can compound and start guarding against healthcare inflation,” he said.
Ashley Weeks, a wealth strategist at TD Wealth, said clients often show little urgency when the subject comes up.
“I think two major reasons for this are more immediate financial concerns, and the incorrect assumption that Medicare will affordably cover all health needs. Failing to preemptively plan for retirement health costs can derail an otherwise thorough financial plan,” Weeks said.
For Peter Hoglund, senior vice president and financial advisor at Wealth Enhancement, the reluctance is emotional as much as financial. Clients face real uncertainty over how much care will cost, when they will need it and how long it will last, which makes the topic both confusing and frightening. Personal experience can cut both ways.
“Families that have seen the nightmare health scenario play-out first hand, usually with a parent or loved one experiencing a healthcare event, are able to prepare for this with more clarity, but it can also become an outsized fear and cause under-preparedness in the rest of the financial plan,” Hoglund said.
Crowell said medical inflation typically runs at least double the broader inflation rate, so today’s spending on co-pays, prescriptions and hospital stays understates what retirees will eventually pay. He added that many Americans lean too heavily on Medicare and assume it covers far more than it does.
“HSAs and other supplemental savings can help address this gap, and talking to a financial advisor about what may or may not be covered by Medicare can make a difference,” Crowell said.
Weeks pointed to a cost that higher-income clients routinely miss: the income-related monthly adjustment amount, or IRMAA, a surcharge added to Medicare premiums once income crosses set thresholds. According to the Centers for Medicare & Medicaid Services, the standard Part B premium rose to $202.90 a month in 2026, up $17.90 from 2025, while individuals with modified adjusted gross income of $500,000 or more pay $689.90 a month.
Weeks said planning software has improved cost estimates by factoring in a client’s health status, life expectancy and location to project out-of-pocket spending before and after Medicare eligibility begins.
All three advisors singled out the health savings account. An HSA lets workers enrolled in a high-deductible health plan contribute pre-tax dollars, invest them tax-free and withdraw them tax-free for qualified medical expenses – the so-called triple tax advantage. For 2026, the IRS caps contributions at $4,400 for self-only coverage and $8,750 for family coverage, with an extra $1,000 allowed for savers 55 and older.
“Medical costs tend to climb faster than overall consumer prices, and as we age, we typically need more care each year,” Weeks said. He urged eligible workers to contribute as much as possible and invest the balance rather than hold it in cash. “An HSA is a triple tax advantaged account that can compound over decades and assist with medical expenses in a tax-efficient way.”
Many savers leave that potential untapped. Fidelity has found that 40% of HSA holders have not invested their balances, and only 13% of D.A. Davidson’s respondents named HSAs as a planned source of retirement healthcare funding. Workplace priorities may also be shifting, with a recent Morgan Stanley survey finding that 401(k) plans now rival healthcare as workers' most valued benefit.
Hoglund cautioned that HSAs have limits of their own. Annual contribution caps are modest relative to the potential size of late-life healthcare bills, and savers have few other accounts designed specifically for medical costs.
Hoglund recommends starting with a comprehensive financial plan and then modeling a major health event to see where it breaks.
“Building in the potential for a healthcare event that adds significant expense and understanding what the net result of this can provide clarity and takes away the uncertainty of the unknown surrounding potential healthcare cost,” he said.
From there, he said, clients can decide whether to buy long-term care insurance, direct more savings to HSAs during their working years or plan to self-fund. Plans should also stay flexible enough to handle costs that outpace inflation – or that turn out lower than expected.
“Look at funding options for this – if you are young enough, a LTC insurance policy may be a good tool to mitigate both the inflationary costs of healthcare costs and allow more of your savings to go to fund other retirement goals. If you are not able to purchase a policy, target savings and dedicating funds towards these costs, and protect them from being used for other purposes,” Hoglund said.
Timing matters on insurance, too. “Look into your future insurance options. If you wait too long to sign up for your own health insurance plan, it will likely cost much more than signing up when you are still young and healthy,” Crowell said.
With just 23% of Americans having discussed the issue with an advisor, the opening for planners is clear. Separate TIAA Institute research shows retirees who work with an advisor report far fewer regrets, even though just one in four Americans use one.
“Being prepared for rising healthcare costs is important, but being informed is the first, most crucial step,” Crowell said in D.A. Davidson’s March 2026 release.
Tax bill inertia, drastic near-term jumps in tax liabilities, and generationally consequential policy uncertainty will spook clients – that is, unless their advisor brings those lurking risks to light.

A six-advisor Vinings practice joins LPL's broker-dealer and RIA platforms, citing independence and succession planning support.

A new Transamerica Institute report finds most American workers feel outpaced by costs and advisors are reaching only a fraction of them.
Asset managers have a new playbook for AI - and catching mistakes is just the start.
North Korea's TraderTraitor group blamed for the record-breaking theft, raising urgent custody and suitability questions for advisors.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

