
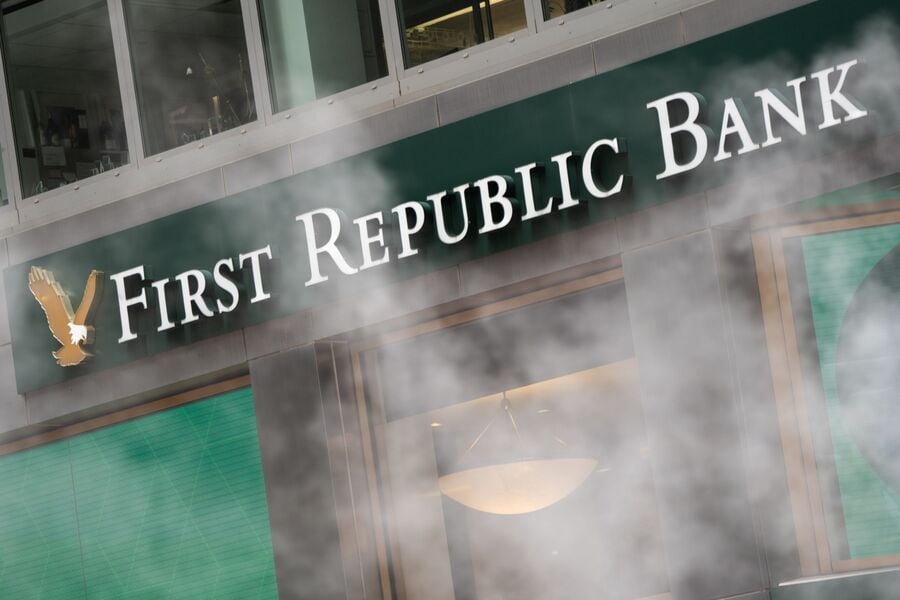
JPMorgan Chase & Co. notified about 1,000 First Republic Bank employees that they aren’t being given jobs — even temporarily — following its takeover of the failed lender.
On Thursday, the biggest U.S. bank offered full-time or transitional roles to almost 85% of the nearly 7,000 employees still working at First Republic when it collapsed, while the rest were told they wouldn’t get offers, according to a person with knowledge of the matter. The temporary jobs will be for three, six, nine or 12 months, depending on the position, the person said, asking not to be identified discussing private information.
“Since our acquisition of First Republic on May 1, we’ve been transparent with their employees and kept our promise to update them on their employment status within 30 days,” a spokesperson for New York-based JPMorgan said in a statement. “We recognize that they have been under stress and uncertainty since March and hope that today will bring clarity and closure.”
Former First Republic employees who weren’t offered jobs at JPMorgan “will receive pay and benefits covering 60 days and will be offered a package that includes an additional lump-sum payment and continuing benefits coverage,” the spokesperson said.
First Republic said in late April it would cut as much as 25% of its workforce, one of a series of actions intended to bolster the troubled bank and reassure investors. Those measures ultimately weren’t enough, and the San Francisco-based company was seized days later. Most of the employees who didn’t get an offer Thursday from JPMorgan had been identified as part of First Republic’s planned cuts, but had yet to be notified when the bank failed, the person said.
JPMorgan, which had 296,877 employees at the end of March, beat out rivals in a government-led auction for First Republic. As part of its winning bid, JPMorgan acquired about $173 billion of First Republic’s loans, $30 billion of securities and $92 billion in deposits — and then had to decide what to do about First Republic's employees, dozens of whom were reeling in more than $10 million a year, Bloomberg News reported earlier Thursday.
The Pennsylvania-based recordkeeper is 'playing Switzerland' as data on 16 million savers will help plan advisors reach 401(k) participants at rollovers and retirement
A BCG report finds private credit and hedge funds driving CIB growth while AI reshapes bank operating economics through 2030.
Janney opens a Houston office with four advisors from Raymond James as Rockefeller deepens its Naples, Florida wealth management footprint.
Bernstein Private Wealth experts says childless adults hold significant wealth yet rarely have a plan.
Shorter waits for failed SIE and Series 7 candidates take effect Jan. 19, speeding the path to registration.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

