
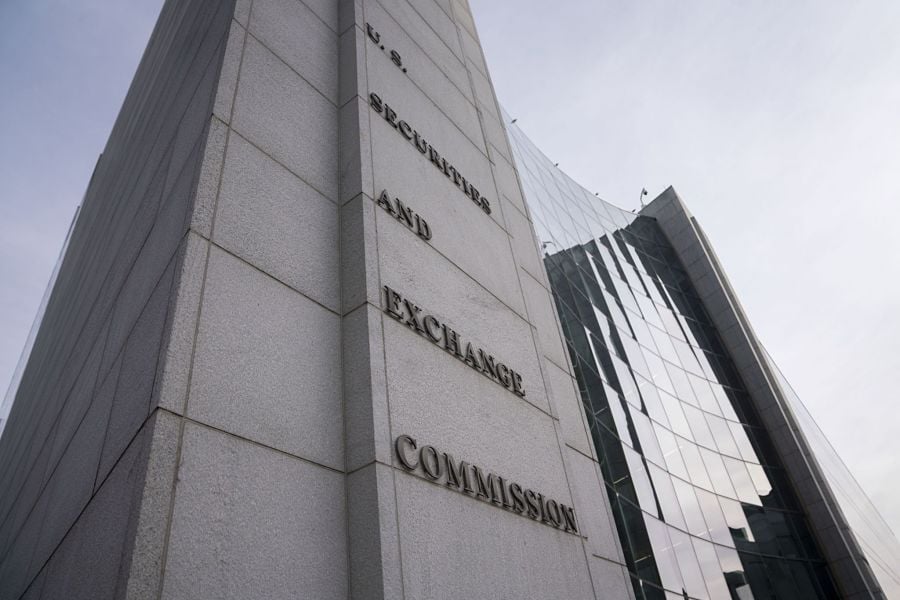
The Securities and Exchange Commission ordered SCF Investment Advisors of Fresno, California, to pay $767,192 to settle charges that it selected high-fee share classes of mutual fund and money market funds for clients without disclosing that less expensive classes of the same funds were available.
In an order released Thursday, the agency said that since January 2014, the firm has recommended mutual funds that charged 12b-1 fees that were collected by its affiliated broker, SCF Securities. Since March 2017, the firm has recommended cash sweep money market funds from its clearing broker that paid revenue sharing to the affiliated broker.
SCF failed to disclose conflicts of interest regarding how the firm benefitted from the receipt of the 12b-1 fees and revenue sharing. After updating its form ADV to provide some disclosure about the conflicts, SCF did not notify existing clients or update the disclosure as a material change until March 28, 2019, according to the order.
Under the terms of the settlement, SCF agreed to pay $544,446 in disgorgement, $22,746 in prejudgment interest and a $200,000 fine.
The fine was assessed because the firm did not self-report as part of the SEC’s recently concluded Share Class Selection Disclosure Initiative. Firms turning themselves in as part of that program avoided civil penalties but did pay money back to investors.
“An adviser must inform clients of its conflicts of interest when recommending investments, including when it or its affiliates are receiving financial benefits for those investment recommendations,” C. Dabney O’Riordan, co-chief of the SEC Enforcement Division’s asset management unit, said in a statement. “For years SCF failed to disclose its financial conflicts even though it was advising clients to purchase more expensive share classes of mutual funds and money market funds that would hurt client long-term returns.”
SCF Investment Advisors did not admit or deny the SEC’s findings.
“The company is very happy to get [the case] behind them,” said the firm’s attorney, Gary Kessler, a shareholder at Kessler Collins. “The SEC had a different opinion as to whether the disclosure was full and adequate. It’s more of an unintentional failure [to disclose].”
The SEC’s action represents a breakthrough when it comes to enforcement of revenue-sharing agreements.
“This is the first case that goes into detail with respect to revenue sharing related to cash sweep money market funds,” said James Lundy, a partner at Faegre Drinker Biddle & Reath.
The SEC wrapped up its share class initiative in April by settling with Merrill Lynch and two other firms. But it is continuing to probe disclosure problems related to 12b-1 fees and other forms of revenue from funds.
Financial industry trade associations have criticized the SEC's share-class crackdown as regulation by enforcement.
Advisory firms should carefully consider whether to recommend mutual funds with 12b-1 fees, Lundy said.
“The [SEC] Enforcement Division has effectively outlawed them,” Lundy said. “Firms need to assess where they’re receiving revenue, the conflicts associated with that revenue, and make sure their disclosures are as detailed as possible.”
Ballast Rock Private Wealth has also brough on a veteran advisor focused on multigenerational planning for business owners and families
Edward Jones study finds caregivers to older adults spend $8,737 a year out of pocket in "generosity paradox" as savings, careers and health absorb the strain
The dispute apparently dates back to deals done ago during the time two advisors worked at Deutsche Bank Securities, or Alex. Brown.
The Pennsylvania-based recordkeeper is 'playing Switzerland' as data on 16 million savers will help plan advisors reach 401(k) participants at rollovers and retirement
A BCG report finds private credit and hedge funds driving CIB growth while AI reshapes bank operating economics through 2030.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

