
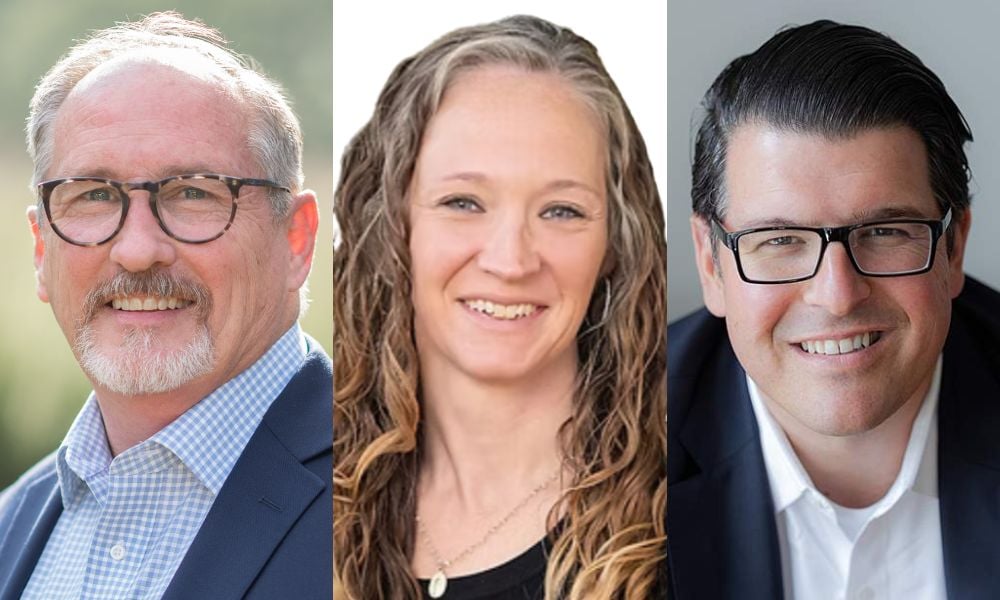
Veteran advisors say the habits drilled into them in uniform – discipline over prediction, mission focus and a code of honor – carry straight into financial planning. They also warn that the advice industry is underserving one corner of the military market in particular: part-time Reservists and National Guard members.
Ahead of Veterans Day, InvestmentNews spoke with four advisors who have served, including in the US Army Reserve and the Marine Corps, about what that background brings to their practices and how they win the trust of veteran clients. The client base is sizable. The US Census Bureau counted 15.7 million veterans in 2024, or 5.9% of the civilian population age 18 and over, according to its 2024 American Community Survey estimates.
Paul Sarama, wealth manager and managing director of The Baker Sarama Wealth Management Group at Steward Partners, spent six years on active duty in the Marine Corps, eventually serving as a sergeant. The lesson he carried out of the service is that preparation matters more than prophecy.
“We didn't succeed because we could predict what was going to happen. We succeeded because we prepared, adapted, and stayed focused when things got chaotic. I think the financial industry sometimes overvalues forecasting and undervalues discipline. Nobody consistently predicts markets. The advisors who create the best outcomes are usually the ones who help clients stay calm, stick to a plan, and avoid making emotional decisions when headlines get scary,” Sarama said.
“My job isn't to be right about every market move. My job is to help clients make better decisions, especially when uncertainty is highest. In my experience, that's where long-term wealth is won or lost,” he added.
William Rabbitt, financial advisor and owner of WP Financial, a Private Advisor Group affiliate, describes the same instinct as mission focus. Rabbitt, who earlier this year joined other military members turned financial advisors in describing the skills they carried over from service, says his firm’s process mirrors military decision-making.
“We know at WP Financial that the client comes first, last, and always. Our focus is our client and what is best for them. We let them know their options, and we make a recommendation based on what we think is the best option given the facts. This focus is something we learn as leaders in the military. Gather the facts, consider the options, and make a decision,” Rabbitt said.
Jessica Chominski, financial advisor and director of institutional marketing at Aquinas Wealth Advisors, serves in the US Army Reserve’s Medical Service Corps. Chominski spent about 18 months of intermediate-level military education studying not only tactics and planning, but also the history of war, its effect on culture and how the profession of arms has evolved. That wider lens, Chominski argues, parallels a fiduciary’s duty to plan around the whole person rather than a single goal.
“Managing wealth in the broader context of a full life of a person, family, or institution with eyes fixed on the person, seeing money as just a tool, can help achieve a broader sense of personal satisfaction,” Chominski said.
For Chominski, the most overlooked group is the part-time force. The Defense Department’s 2024 Demographics Profile of the Military Community counted more than 760,000 Selected Reserve members, who train throughout the year while holding civilian jobs.
“I think the most significant gap lies with advisors working with Servicemembers who are in a part-time status as either Reservists or National Guard. Everything for us is different: budgeting, life insurance, retirement, and saving. Throw in a mobilization or deployment and having to suspend a civilian job for an extended period of time, and there are even more challenges,” Chominski said.
Reservists and Guard members who live away from active-duty installations often lack the military-specific financial experts that active-component service members can reach more easily, Chominski added.
John W. Donnelly, managing partner of Essex Wealth Advisory LLC, a Private Advisor Group affiliate, sees a planning gap across the veteran market more broadly. Donnelly and his partner, Jorge Vergara, are both Marine Corps veterans.
“Most Veteran clients fall into the ‘mass affluent’ category. Historically, they’ve made most of their financial product decisions in an ‘ad hoc’ fashion. Most never had a holistic, encompassing financial plan developed for them. Most advisors historically were happy to serve them in this product-specific approach,” Donnelly said.
That echoes advice from other veteran advisors who have urged peers to learn how military benefits and pensions work before taking on military families as clients.
Shared service opens doors, the advisors say, but it does not close the deal. Sarama believes veterans can spot inauthenticity quickly and that pretending to understand military life is the fastest way to lose credibility.
“As a former Marine, I have some shared experiences with veteran clients, but I don't assume that automatically creates trust. It helps open the door. What builds trust is demonstrating competence over time,” Sarama said.
“One thing veterans have taught me is that they generally care less about investment performance than many people assume. Of course returns matter, but what they really want is clarity,” he said.
Chominski starts with language. “Both the finance world and the military rely heavily on jargon and that can be a barrier to veterans seeking financial advice, especially as it may expose a level of vulnerability that can trigger a negative response that leads to a lack of participation in financial decision making,” Chominski said. “Sometimes just swapping a few jargon-laced war stories or commiserating about how bad the coffee is can break the ice!”
Rabbitt argues the formula is the same for any client. “You build trust by listening to and understanding a client’s situation. Then having the competence and confidence to tell the client where they are regarding their ability to meet their objectives,” he said. “We do the work and we will get paid but don’t worry about getting paid, worry about the client.”
For Donnelly and Vergara, the guiding principle is honor, a theme advisors with military roots also raised in last year’s Veterans Day coverage.
“We both agree that the absolute number one military characteristic that has shaped our financial planning practice is honor,” Donnelly said. Yet he cautions against leaning on shared history alone.
“That’s an advantage a Veteran advisor has. It’s important to ‘read the room’ however and not count on it too much. Many Vets are bottom line oriented so having a structure is as important to the story telling,” Donnelly said.

New data shows veterans report stronger financial security, legacy confidence and career earnings momentum than non-veterans.

Osaic subsidiary continues to forge new routes to US high-net-worth and ultra-high-net-worth people.
Capco's Matt Berkowitz tells InvestmentNews that aggregating client data is no longer enough.
The capital most families plan to pass on will likely arrive too late to change anything.
Arch claims 40% operating cost savings for Mercer as Nitrogen unlocks its agentic AI and tech suite to 10,000 Osaic advisors.
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.

