
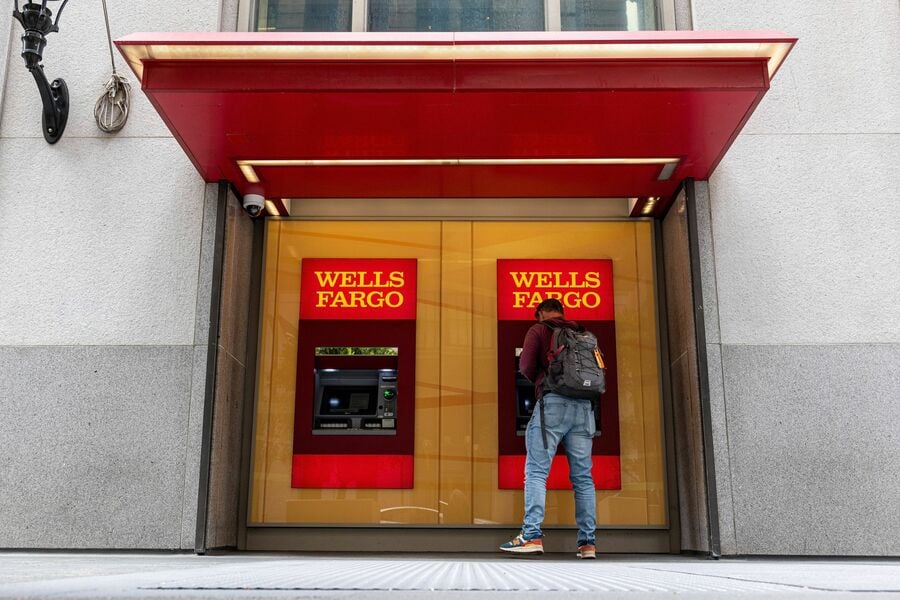
Wells Fargo & Co. announced a $210 million effort to expand racial equity in residential lending after a Bloomberg News investigation found the bank approved Black homeowners seeking to refinance mortgages in the pandemic at a far lower rate than white ones.
The firm, the biggest mortgage lender among U.S. banks, is committing $150 million beyond its usual lending programs to help Black borrowers refinance mortgages, according to a statement Wednesday. It will also provide $60 million in grants to support homeowners of color in eight markets that have significant ownership gaps between white and minority families.
“These efforts are an important next step and will help close the homeownership gap between white and minority families created by decades of systemic inequities,” Kristy Fercho, Wells Fargo’s head of home lending, said in the statement.
Bloomberg reported last month that in 2020, Wells Fargo approved just 47% of Black homeowners who completed applications to refinance mortgages compared with 72% of white applicants. Its approval rate for Black applicants increased to 58% in 2021 but continued to lag behind white homeowners at 79%. In both years, Wells Fargo’s approval rate for Black refi applicants trailed other major banks and nonbank lenders.
The firm has said in the past that its underwriting standards are consistently applied, and “additional, legitimate, credit-related factors” were responsible for the differences. Still, it has faced scrutiny from lawmakers in recent weeks, including a group of Democratic senators calling for a regulatory investigation into Wells Fargo’s treatment of Black homeowners seeking to refinance during the pandemic.

New F2 Strategy research finds more firms growing without M&A, yet one-third still lack a defined growth process.
Shadow AI, weak oversight, and no formal policy highlight why advisory firms are more exposed to cyber risk than they realize.

Meanwhile, DPL Financial Partners adds two annuity executives and Prime Capital Financial hires a Mid-Atlantic retirement plan consultant.

Andrew Komarow pleaded guilty Thursday in federal court in Hartford to defrauding three financial services companies of close to $3.3 million.

Elsewhere, Cetera picks up a $210 million Connecticut team from MML, while Wells Fargo FiNet adds a San Diego family practice from LPL.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

