
Most investment advisors look warily at the SEC. But some smaller advisors are envious of an advantage that larger firms registered with the agency have when it comes to advertising.
The Securities and Exchange Commission’s marketing rule allows investment advisors for the first time to use client testimonials, endorsements and reviews on third-party platforms to tout their firms.
The regulation went into force last November. So far, most advisors have been reluctant to post client testimonials because of the uncertainty about how the SEC will enforce the marketing rule.
But there are some advisors who can’t use testimonials even if they want to — those who aren't registered with the SEC. The agency’s regulations apply to advisors with more than $100 million in assets under management. Advisors with less than $100 million in AUM register at the state level.
The problem for smaller brokers is that their state may not have adopted the SEC marketing rule or a similar regulation, preventing them from using testimonials and client reviews.
“We see a lot of angst from advisors that are frustrated that the federal [SEC] firms get to do this but they can’t do it in their state,” said Michael Kitces, co-founder and executive chairman of the XY Planning Network, a platform for fee-for-service financial planners.
Almost all XYPN advisors are state-registered. Their clients tend to be technologically and social media savvy, Kitces said, which makes them a target audience for online testimonials and reviews.
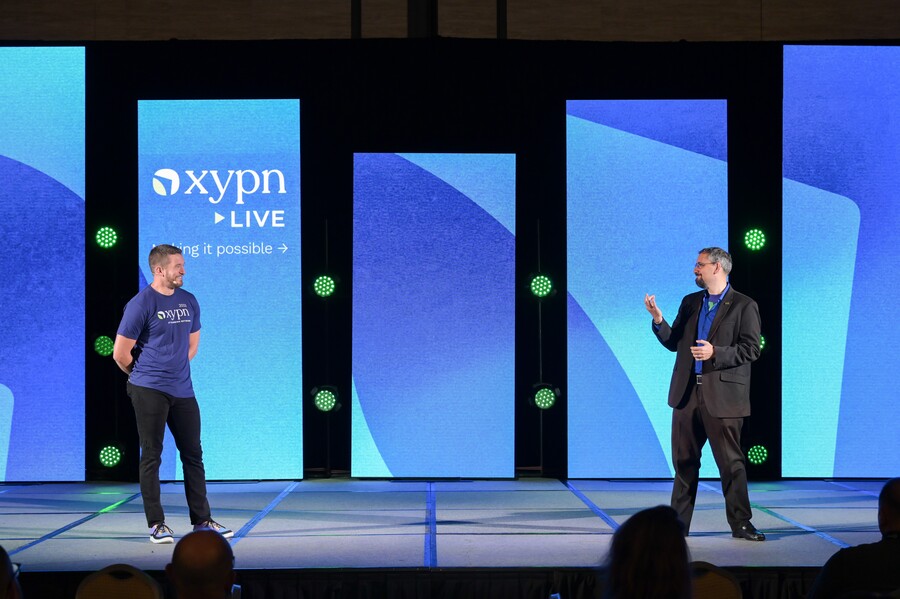
“It’s frustrating for a lot of [XYPN] members not to be able to show up on the websites or Google reviews and places like that,” Kitces said in an interview earlier this week from an XYPN conference in Atlanta. “That’s the area where we’d like to see states take action.”
The platform offers education, training, technology, back-office and client support and other services for about 1,800 independent financial planners. Advisors on the platform are compensated for their planning services –— through subscription, retainer, hourly and other fees — rather than charging clients a fee based on their assets under management.
Another way XYPN helps its members is with compliance.
“You really are your own chief compliance officer,” Kitces said of the small firms on the XYPN platform.
It’s a challenge magnified at the state level because states examine their advisors about every three to five years, compared with a seven or eight-year cycle for SEC-registered firms, he said. “States actually have a much higher audit rate than the SEC.”
Some states have been particularly aggressive about scrutinizing subscription fees. Colorado, for instance, is among those that have been taking a hard look at whether advisors who are using new kinds of non-AUM fees are performing promised services for clients.
Kitces doesn’t resist the regulation of subscription fees. But he grimaces when a regulator questions a fee-for-service charge but gives a pass to an AUM fee that is supposed to cover planning when the advisor assessing the AUM payment doesn’t do any planning.
“Until we see regulators treat the business models equally, we’re going to push back on the regulators,” Kitces said. “Not that we don’t think financial planning should be regulated. But if financial planning should be regulated, it should be the same regardless of the fee model.”
Some state advisors have to cope with varying regulations from state to state, if they operate in multiple jurisdictions.
“The ultimate problem of state nonuniformity is when you have to run two businesses within your business, depending on which state you’re in,” Kitces said.
While state regulation may be a challenge for XYPN advisors, business appears to be booming.
“XYPN members saw a five-year client household growth rate of 28.6%, compared to the 5.1% client growth rate in Schwab’s 2023 RIA Benchmarking Study,” XYPN said in a statement released Tuesday at its Atlanta conference.
That trend illustrates that there are a lot of people in their 30s to 50s who are willing and able to pay for financial planning but may not have sizable enough assets to generate an attractive AUM charge, said XYPN CEO Alan Moore.
“It really is about the market size, which is gigantic compared to what the AUM-centered business model has really been able to serve,” Moore said.
Kitces added: “That’s sheer consumer demand.”
The platform expects to have more than 2,000 advisors on board next year.

Docupace also rebuilt its wealth operations platform around a single client record, while Focus Financial picks Nevis to bring AI to its advisors.

Consolidators handled 53% of deals through September as smaller sellers stalled amid market volatility, DeVoe & Company finds.
Shook Research has a new name and brand, Veritant, and will continue its coveted rankings of financial advisors.
The Supernova-powered lending line follows a Flourish Cash rollout as the insurer pushes private-bank-style tools to its 6,000-plus advisors

New Escalent research finds younger, more diverse DC plan participants are open to rollovers - but increasingly prefer outside firms.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

