
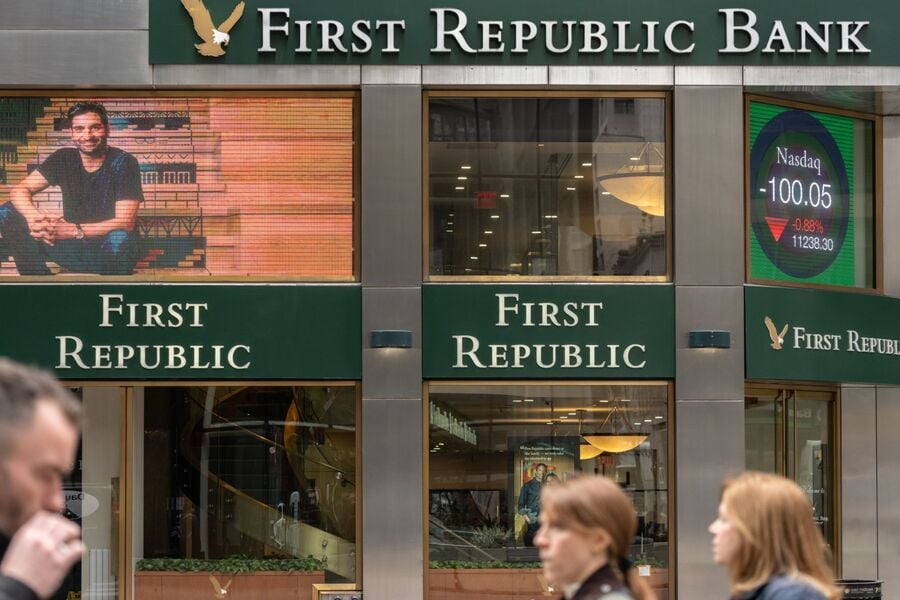
The Federal Deposit Insurance Corp. has asked banks including JPMorgan Chase & Co. and PNC Financial Services Group Inc. to submit final bids for First Republic Bank by Sunday after gauging initial interest earlier in the week, according to people with knowledge of the matter.
The regulator reached out to banks late Thursday seeking indications of interest, including a proposed price and an estimated cost to the agency’s deposit insurance fund. Based on those submissions Friday, the regulator invited at least two firms to the next step in the bidding process, the people said, asking not to be named discussing the confidential talks.
A spokesperson for JPMorgan declined to comment. Spokespeople for PNC and the FDIC didn’t immediately respond to requests for comment sent outside of normal business hours.
The bidding process kick-started by regulators — after weeks of fruitless talks among banks and their advisers — could pave the way for a tidier sale of First Republic than the drawn-out auctions that followed the failures of Silicon Valley Bank and Signature Bank last month. Authorities are stepping in after a particularly precipitous drop in the company’s stock over the past week, which is now down 97% this year.
Unclear to some involved in the process is whether regulators might use a bid for a so-called open-market solution that avoids formally declaring First Republic a failure and seizing it.
The stock’s drop — leaving the company with a $650 million market value — has made such a takeover at least somewhat more feasible.
But finances aren’t the only hurdle to doing a deal.
JPMorgan is among a small number of giant banks that have already amassed more than 10% of nationwide deposits, making the firm ineligible under U.S. regulations to acquire another deposit-taking institution. Authorities would have to make an exception to allow the country’s largest bank to get even bigger.
As of Friday evening, the FDIC had yet to reach a decision on putting First Republic into receivership, people with direct knowledge of the matter said. Representatives for California’s banking regulator, which would take the lead in declaring whether the San Francisco-based lender has failed, didn’t respond to requests for comment.
Weighing on First Republic’s balance sheet is a mountain of low-interest loans, including an unusually large portfolio of jumbo mortgages to wealthy clients. Such debts have lost value amid interest-rate hikes, leaving the firm facing losses if forced to sell them.
During last month’s regional banking crisis, wealthy customers and businesses yanked their cash from banks with such flaws in their balance sheets. In response, the Federal Reserve opened up an emergency lending facility to give banks a way to borrow against some of their holdings to meet any demands for cash.
A group of 11 banks that deposited $30 billion into First Republic last month — giving it time to find a private-sector solution — have proved reluctant to band together on making a joint investment. A few proposals that surfaced in recent days called for a consortium of stronger banks to buy assets from First Republic for more than their market value. But no agreement materialized.
Instead, some stronger firms have been waiting for the government to offer aid or put the bank in receivership, a resolution they view as cleaner — and potentially ending with a sale of the bank or its pieces at attractive prices.
But receivership is an outcome the FDIC would prefer to avoid in part because of the prospect it will inflict a multibillion-dollar hit to its own deposit insurance fund. The agency is already planning to impose a special assessment on the industry to cover the cost of SVB and Signature Bank’s failures last month.

Merrill recruits from UBS, Morgan Stanley and Edward Jones as an Oklahoma credit union moves its $430M wealth program to Ameriprise

Bay Area and South Carolina advisory teams, including a breakaway group from Raymond James, mark the latest wins for two fast-growing wealth management platforms
Mercer taps two psychologists to help ultra-wealthy families with succession as half of family offices lack a complete plan

Higher financing costs, slower exits, and growing pressure on asset owners have created opportunities for value investors.
Valerie Bevan joins LPL Financial after more than 30 years in financial services, citing platform flexibility and advisor independence.
Advisors are broadening the conversation beyond savings to help clients prepare for the realities of longer lives
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.

