
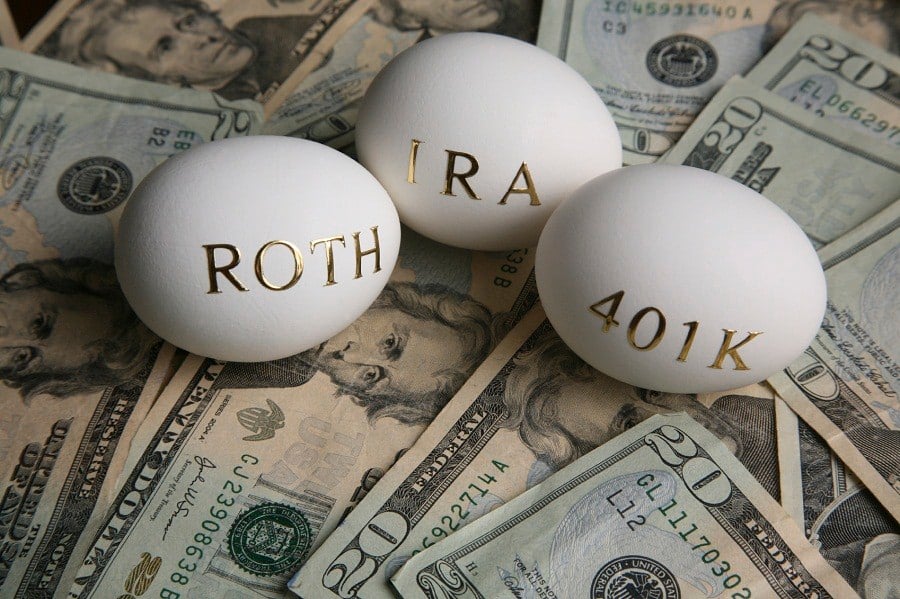
American workers pushed their retirement savings to new heights in the first quarter of 2026, even as equity markets churned through one of their more volatile stretches in recent memory.
According to Fidelity Investments' newly released Q1 2026 retirement analysis – drawn from more than 54 million IRA, 401(k), and 403(b) retirement accounts – savings rates for both 401(k) and 403(b) participants reached record levels, while IRA contributions surged 29% year-over-year.
"Retirement savers started the year strong with record-high savings rates and contributions, reflecting the long-term approach they're taking with retirement preparedness," Sharon Brovelli, president of Workplace Investing at Fidelity Investments, said in a statement.
"While it can be tempting to make changes to retirement savings during market volatility, it is positive to see participants stay the course with their contributions – an approach that will ultimately strengthen outcomes as retirement nears."
According to Fidelity, the total savings rate for 401(k) participants – encompassing both employee and employer contributions – reached 14.4% in Q1 2026, edging closer to Fidelity's recommended combined savings rate of 15%. For 403(b) participants, the total savings rate hit 12%.
The average employee contribution rate reached 9.6%, a record high in Fidelity's tracking, while the average employer contribution rate stood at 4.8%.
On the employer side, the average quarterly employer contribution amount hit a record $2,080 in Q1, topping the previous peak of $2,020 set a year earlier. Nearly one in five participants (18%) increased their savings rate during the quarter, largely driven by automatic contribution escalation features built into plan designs. Just 5.7% made any change to their asset allocation, down from 6% a year prior.
Average account balances dipped modestly quarter-over-quarter, reflecting broader market conditions. The average 401(k) balance stood at $141,000 as of March 31, 2026, down 4% from the previous quarter but up 11% from Q1 2025, per Fidelity's data. The average 403(b) balance came in at $130,000, off 3% from Q4 2025 but up 13% year-over-year.
Fidelity counted 645,000 401(k) millionaires at the end of Q1 2026, according to Michael Shamrell, vice president of Workplace Thought Leadership at Fidelity Investments. That compares to 665,000 at year-end 2025, a pullback consistent with the market retreat seen in the first quarter.
IRA activity was a standout in Fidelity's first-quarter figures. The firm reported a record-high number of IRA account holders making contributions – up 28% year-over-year – with total IRA contributions rising 29% from the same period in 2025. The average IRA balance was $131,380 as of March 31, down 4% from the fourth quarter but up 7% from Q1 2025.
Much of the momentum was driven by Roth accounts. Roth IRAs accounted for 67% of IRA contributions in Q1, while Roth conversion transactions climbed 41% year-over-year, according to Fidelity.
"We're encouraged to see investors creating thoughtful, long-term strategies to build their wealth," said Bob Mascialino, president of Wealth at Fidelity Investments. "Choices like increasing contributions to Roth accounts reflect a focus on flexibility, tax efficiency, and confidence in planning for the future – principles that are essential to navigating financial complexity and building lasting financial security."
Across age groups, Gen Z led IRA growth in Q1 with total contributions increasing 65% year-over-year, followed by Millennials at 31%.
Rita Assaf, vice president of Retirement Offerings at Fidelity Investments, attributed the Gen Z surge to a combination of factors: greater accessibility to financial services platforms, and heightened financial awareness shaped in part by social media, so-called finfluencers, and workplace financial wellness programs.
"Gen Z is more financially aware than other generations because they are seeing some of the struggles their parents went through and they are taking more action," Assaf said.
Fidelity's Q1 2026 analysis also spotlights findings from its 2026 Stock Plan Participant Research, a separate study of more than 25,000 employees globally conducted between September and October 2025 by third-party pollster ConsumerMetrics on behalf of Fidelity.
The data reframe how advisors might think about employee stock compensation – not just as a component of total pay, but as an entry point into broader investing behavior and long-term wealth building.
Forty-three percent of participants said they became first-time investors through their company's stock plan. Of those new investors, 34% went on to invest beyond the plan itself, according to the Fidelity research. For advisors who work with corporate employees or executives, this suggests that equity compensation programs are quietly emerging as a way to engage and serve that investor class.
The research also found that 73% of participants plan to use stock plan proceeds as part of their long-term financial strategy, and 61% expect equity assets to help fund retirement. Beyond long-term planning, 47% reported having sold shares to cover immediate financial needs, demonstrating their potential as both a wealth-building vehicle and a financial safety net.
Retention and talent acquisition dynamics are shifting alongside this growing reliance. According to the Fidelity data, 56% of employees said equity compensation makes them more likely to remain with their employer, and 65% cited it as an important factor in evaluating a job offer.
But while 78% of participants said they understand the mechanics of their plan – such as how to accept a grant – just 48% reported confidence in actually making informed decisions about their equity holdings.
Fidelity's research identified education and engagement as the critical levers: employees who actively use equity education resources reported materially higher levels of confidence and satisfaction compared with peers who did not.
The Pennsylvania-based recordkeeper is 'playing Switzerland' as data on 16 million savers will help plan advisors reach 401(k) participants at rollovers and retirement
A BCG report finds private credit and hedge funds driving CIB growth while AI reshapes bank operating economics through 2030.
Janney opens a Houston office with four advisors from Raymond James as Rockefeller deepens its Naples, Florida wealth management footprint.
Bernstein Private Wealth experts says childless adults hold significant wealth yet rarely have a plan.
Shorter waits for failed SIE and Series 7 candidates take effect Jan. 19, speeding the path to registration.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

