
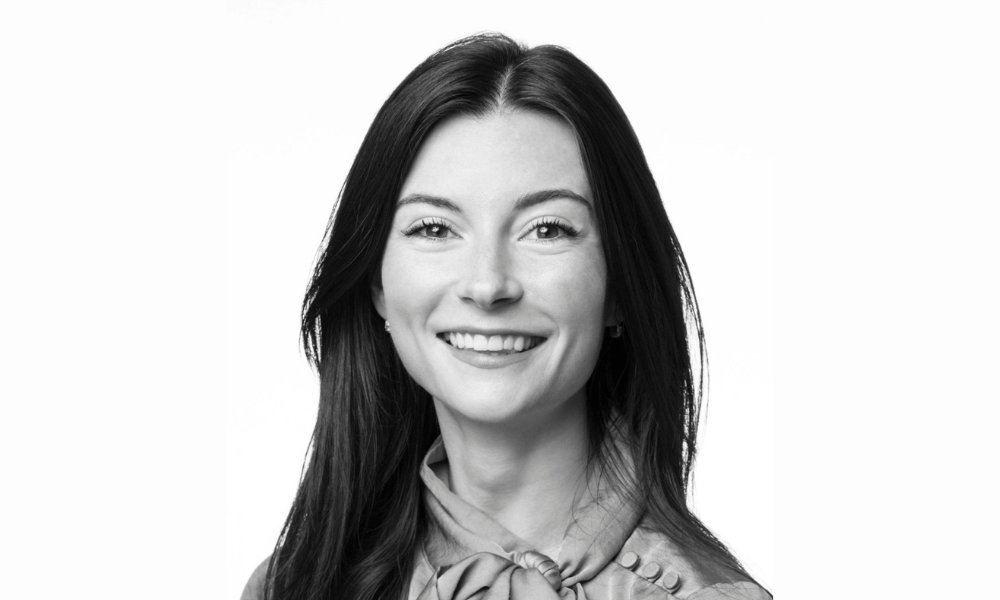
Families that devote years to perfecting trusts and tax strategies while neglecting to prepare the people who will inherit the wealth are setting themselves up for failure, according to Mallory Findley, Head of Family Dynamics and Financial Education at Rockefeller Capital Management in New York.
With an estimated $124 trillion set to transfer to heirs and philanthropy over the next 25 years, according to Cerulli Associates' research on high-net-worth markets the stakes have never been higher and Findley believes the industry is still getting the priorities wrong.
"Families are more likely to focus on the legal and financial aspects of wealth transfer because they are more tangible and measurable," she said. "They can see a trust document, a tax return, estate plan, or investment portfolio return data in writing. Family dynamics are different. They involve the intangibles: more nuanced relationships, communication, expectations, and are often emotionally charged."
The consequences of that avoidance, she warns, are predictable. Wealth tends to amplify existing communication patterns and tensions. The longer a family waits to address dynamics as a core component of the transfer plan, the more difficult the process becomes, even when all the legal documents are in order.
Findley's approach starts a step earlier than most advisors would think to intervene and long before heirs know what they stand to inherit.
"Parents should focus conversations about wealth with their children around purpose, values, and preparation, rather than on dollar amounts," Findley said. She advises families to begin by discussing how the wealth was created, the values behind the financial decisions that shaped it, and the responsibilities that accompany it.
A practical tool she often recommends is developing a family mission statement; a document that reflects shared values across generations, articulates the family's aspirations, and captures how they hope to contribute to society.
"By grounding family discussions about wealth in values and purpose first, families can foster a sense of responsibility and purpose in their children to help them become strong stewards of wealth," she said.
That approach is gaining traction across the industry. Research published by InvestmentNews on multigenerational planning trends found that roughly two-thirds of advisors now say clients are including their children or parents in wealth transfer discussions - a meaningful shift from the one-sided planning conversations that were once the norm.
Findley draws a clear distinction between the financial literacy of understanding a portfolio or a trust structure and the broader preparation she believes heirs actually need.
"Preparing an heir for wealth is really about preparing them for future decisions they will need to make with wealth," she said. "Financial literacy is important, but so is self-awareness, communication skills, emotional intelligence, resilience, and the ability to collaborate with family members and advisors."
Her process involves helping heirs first understand their own strengths, motivations, and decision-making tendencies and then understand those of other family members. When siblings enter the picture, those differences can be a source of friction.
But Findley says that governance structures are not designed to eliminate differences; they are designed to create a framework that allows families to work through them productively.
"Many conflicts arise when family members misinterpret one another's intentions," she said. "By helping family members better understand each other's personalities, strengths, communication styles, and perspectives, we help them feel empathy for each other and reduce unnecessary friction."
Governance tools such as family constitutions, statements of wishes, and family councils, then give that groundwork a formal structure for decision-making and accountability.
Findley's perspective points to a fundamental redefinition of what comprehensive wealth management looks like for multigenerational families - a shift that InvestmentNews has documented as advisors move toward a whole-family model of client service.
"Today's advisors no longer solely manage investment portfolios," Findley said. "To effectively serve multigenerational families, they need to understand not only the family's balance sheet, but also the people behind it."
She is direct about what that requires. Advisors who take the time to understand the full family’s dynamics, goals, values, and relationships, are better positioned to anticipate challenges, facilitate difficult conversations, and support thoughtful transitions across generations. Those who don't risk losing those relationships the moment a transfer occurs.
The data supports the urgency. Research from Cerulli Associates has found that more than 70 percent of heirs change advisors after inheriting, making early engagement with the next generation one of the most consequential retention strategies in the industry.
"The biggest mistake is waiting too long to prepare younger generations," Findley said. "Too often, families devote years to preparing their assets and not enough time to preparing the next generation."
Trust structures, she notes, work best when they are paired with tools that communicate the grantor's intent; statements of wishes, family mission statements, or letters of intent. While these documents are typically not legally binding, they give trustees the context needed to make decisions that support beneficiaries' evolving needs while staying aligned with the original vision.
"Wealth transfer is not simply about passing down assets," Findley said. "It's about passing down purpose, relationships, and the capacity to steward both."

New BCG research names financial services among the world's most AI-exposed industries and the US as a top-tier AI economy.

New Empower research reveals a "retirement drift" problem that hands financial advisors a direct opening to add client value.
Nevis joins Jump at RIA platform Focus as both vendors’ AI tools aim to handle account opening and notetaking.
Ballast Rock Private Wealth has also brough on a veteran advisor focused on multigenerational planning for business owners and families.
Edward Jones study finds caregivers to older adults spend $8,737 a year out of pocket in "generosity paradox" as savings, careers and health absorb the strain.
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

