
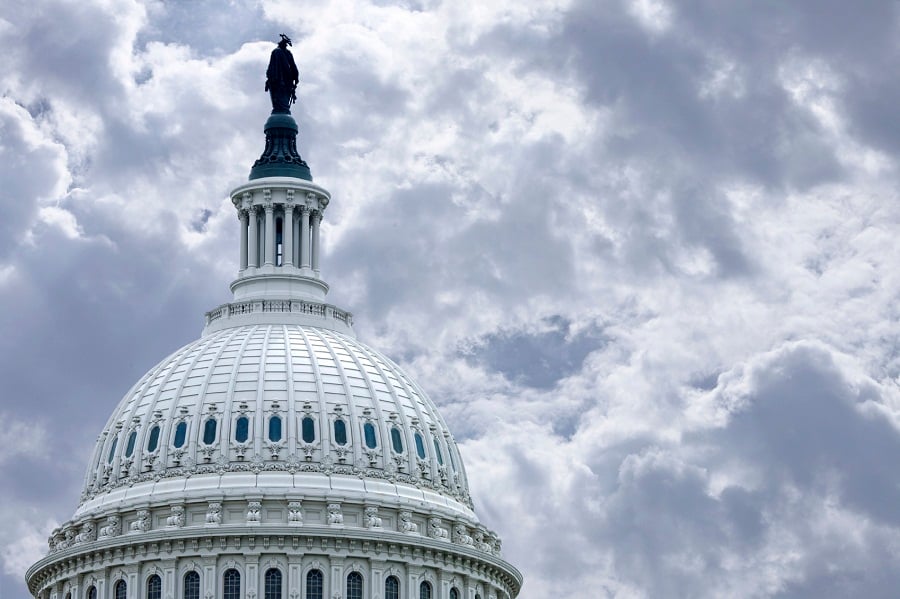
Ever since President Joe Biden won the White House and Democrats gained control of Congress about a year ago, financial advisers have braced for an array of potential tax increases that could affect their wealthy clients.
Now Congress is attempting to advance a version of the Build Back Better Act, the hefty spending-and-tax package that incorporates the Biden administration’s economic agenda, whose primary revenue proposal affecting individual rates would impose an income tax surcharge on earnings over $10 million.
Most of the possible tax hikes that had been discussed in one form or another over the last few months have fallen by the wayside. They include ending the step-up-in-basis on inherited assets and taxing unrealized capital gains upon death, raising the capital gains tax rate to the top individual rate for high earners, imposing required minimum distributions on mega individual retirement accounts, curbing Roth conversions for the wealthy and ending “back-door” Roth conversions for all income levels.
The tax whirlwind has calmed down to a breeze that's probably not going to affect directly most of an adviser’s clients. It looks as if sitting tight, rather than making immediate portfolio and tax planning changes, was the right approach.
“Don’t jump to conclusions,” Tim Steffen, director of tax planning and private wealth management at Robert W. Baird & Co. Inc., told the audience Monday at the InvestmentNews Retirement Income Summit in Naples, Florida. “All these people who rushed to implement all these strategies over the last couple weeks are probably kicking themselves right now. Don’t do anything you can’t undo.”
Regardless of what is happening — or suddenly not happening — in Washington, the focus should always be on the client, advisers said.
“It all boils down to what was your plan, goals and objectives,” said David Kover, managing partner at Vertical Financial Group. “We want to be proactive, but we don’t want to be reactive.”
When the House Ways and Means Committee targeted Roth conversions in its contribution to the Build Back Better bill, it sent up a red flag for advisers. But the decision on doing a Roth conversion should be made based on individual portfolios rather than a pending threat from Washington.
“Try to figure out for each client what works for them,” said Thomas Balcom, founder of 1650 Wealth Management. “Every client is unique.”
Julie Hall, an adviser at Vision Capital Partners, looks first to a client’s financial situation rather than to Washington before recommending Roth conversions.
“We analyze, analyze and analyze,” Hall said. “What are their goals and what’s their endgame?”
For the upcoming tax year, she's concentrating on the current tax code. For instance, the multiple tax advantages of health savings accounts remain in place and haven't been part of the tax policy flurry of the last few months.
“Focus on what we can control,” Hall said. “Make decisions on what we know today.”
There’s always the possibility that the tax proposals floated this year to pay for the spending in the Build Back Better bill could reappear. But it may be difficult to get the proposals that are no longer on the table, such as ending step-up-in-basis, back into the discussion.
“If it was ever going to happen, it was going to in this bill because there’s been so much attention paid to it, and it still couldn’t be passed,” Steffen said. “It’s a great talking point, but logistically, I don’t know if it will ever happen.”
The tax reform atmosphere could change again after the midterm elections a year from now, when Democrats will be defending their razor-thin majorities in the House and Senate.
“Our job as advisers is to adjust to whatever laws are passed,” Balcom said.
One constant about tax policy is it’s not immutable.
“There is no such thing as permanent tax law,” Steffen said. “Things change all the time.”

Higher financing costs, slower exits, and growing pressure on asset owners have created opportunities for value investors.
Valerie Bevan joins LPL Financial after more than 30 years in financial services, citing platform flexibility and advisor independence.
A new independent benchmark finds a widening gap between AI leaders and laggards across 30 of the world's largest investment firms.

Jamie Price says LPL shifted its Commonwealth target from advisors to assets, letting 16 months of growth mask departures

80% of Baby Boomers prefer guaranteed income over growth investments, yet only 17% hold an annuity, leaving protection gaps for financial advisors to close
Advisors are broadening the conversation beyond savings to help clients prepare for the realities of longer lives
Growing wealth, evolving priorities, and untapped opportunities are reshaping how women approach long-term investing.

