
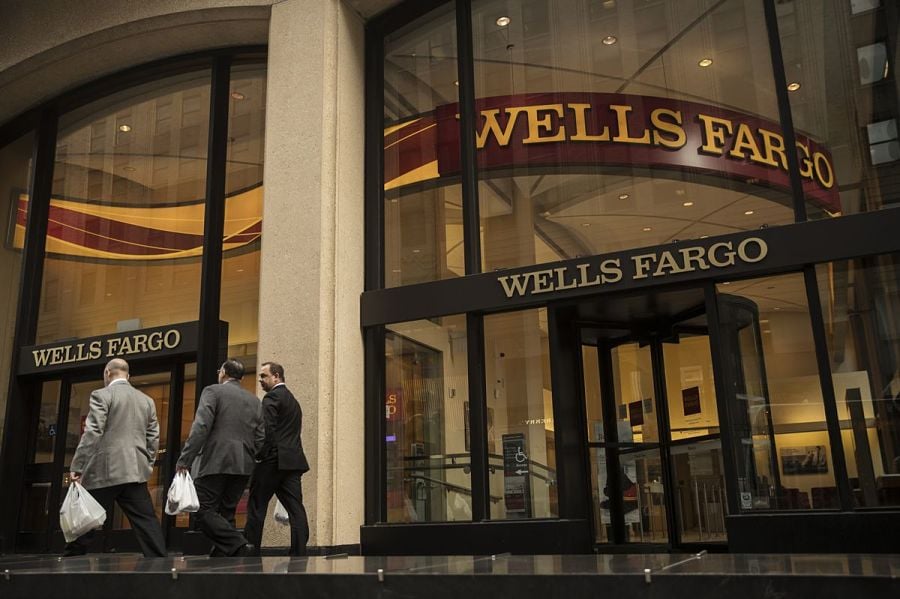
Wells Fargo & Co. profit slumped 56% in the third quarter as Chief Executive Charlie Scharf took charges to address old scandals and begin his job-cutting push.
The bank posted a surprise increase in third-quarter expenses as it set aside almost $1 billion for customer remediation and $718 million in restructuring charges. That countered loan-loss provisions that came in at less than half of what analysts had expected.
In his first year heading Wells Fargo, Scharf has been working to move the firm past a series of scandals. He’s tasked with making harmed customers whole, repairing relations in Washington and improving the firm’s earnings. He’s repeatedly lamented the company's high costs, pledging to ultimately shave $10 billion off annual expenses.
“Our top priority continues to be the implementation of our risk, control and regulatory work, but we are also taking targeted actions to improve the experience for our customers, clients, communities and employees,” Scharf said in a statement Wednesday. “The trajectory of the economic recovery remains unclear as the negative impact of Covid continues and further fiscal stimulus is uncertain.”
Wells Fargo set aside $769 million in loan-loss provisions in the three months ended Sept. 30, less than the $1.65 billion analysts had forecast. CFO John Shrewsberry said last month that the firm wasn’t anticipating losses to be worse, but cautioned that “it’s hard to know whether they’re going to be better or just further out in the future.” Nonaccrual loans rose 5.5% from the second quarter, largely driven by consumer mortgages.
Wells Fargo shares declined 54% this year through Tuesday, more than the 31% drop in the KBW Bank Index. The stock fell 1.7% at 7:57 a.m. in early New York trading.
Rivals JPMorgan Chase & Co. and Citigroup Inc., which reported their third-quarter results Tuesday, set aside just $2.87 billion for loan losses in the period, also less than half what analysts expected, partly because they’d already been aggressive in beefing up their reserves in the first half of the year.
Wells Fargo’s non-interest expenses climbed by $30 million from a year earlier to $15.2 billion. The bank is working to dramatically reduce costs and has started workforce reductions that could ultimately number in the tens of thousands. Wells Fargo had 274,900 employees as of Sept. 30, down from 276,000 at midyear.
Also in Wells Fargo’s third-quarter results:
Halbert Hargrove senior wealth advisor weighs in on the products' guaranteed income upside, the operational drag and his wish list for carriers.
With 8.6% of advisors set to switch firms in 2026, Cerulli says advisor recruitment hinges on technology, branding and HNW support.
“I’m seeing more disputes like this between advisors and other advisors at the same practice,” said one industry executive.
Longer retirements and steady inflation could drain retiree portfolios before heirs inherit, with 4% net returns running dry by year 34.
A single fintech partner triggered a $68.8M credit hit.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor
Northern Trust’s Ken Lassner shows advisors how to convert volatility into after-tax portfolio gains

