
Name, image and likeness (NIL) income — payments college athletes earn for endorsements, appearances and social media deals — is landing in the hands of teenagers years before they would have faced a professional contract, and financial advisors say the industry has had to move just as fast to keep up.
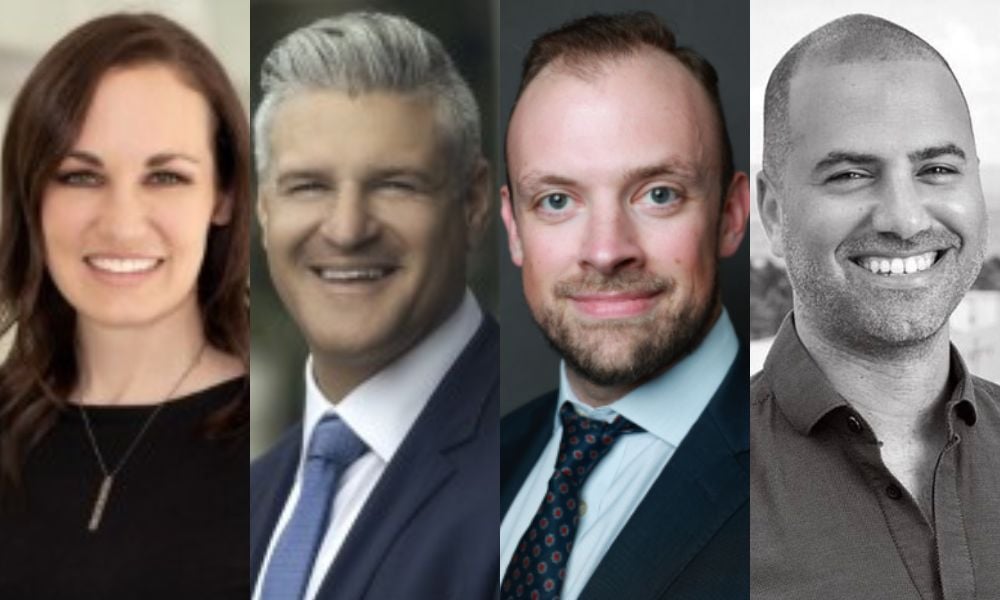
"The entry point into an athlete's life has moved five years earlier," said Matt LaPorta, executive in residence at Dynasty Financial Partners, who spent parts of five seasons in Major League Baseball before moving into wealth management. "An advisor used to get the call when a kid signed his first pro contract at 22. Now the call comes from a high school junior's mother with a six-figure collective deal on the table and no idea what she's looking at."
That shift changes who advisors are actually working with. "The athlete is 17. The decision-maker is the parent," LaPorta said. "Families are curious and they're looking sooner, which means there's a real window for advisors who show up early and educate instead of sell."
Brittany Hartnett, principal partner and chief growth officer at OpenArc Corporate Advisory, said the volume of decisions can overwhelm families with no prior exposure to this kind of income. She pointed to a recent client, a college freshman football player earning approximately $800,000 in NIL income, who had to evaluate his agent agreement, form an LLC, plan for taxes, make investment decisions and manage requests for money from relatives — all at once.
"We spend as much time helping athletes build healthy financial habits as we do managing their assets," Hartnett said. "We played a central role in coordinating his team of professionals, including his agent, attorney, accountant and financial advisor, helping ensure each aspect of his financial life worked together cohesively."
Chris Brophy, a private wealth advisor at Americana Partners, said the compressed timeline cuts both ways. "You now have 18- and 19-year-olds earning real money before they have had any reason to understand taxes, investing, entities or cash flow," he said. "That creates a huge opportunity if the right people get around them early, but it can also create bad habits very quickly."
Hartnett's advice for athletes building wealth beyond their playing careers starts early. "Time is one of the most powerful assets an athlete has, especially when peak earnings are concentrated in a relatively short period," she said, adding that athletes should also build a team of advisors who "will tell you what you need to hear, not what you want to hear."
LaPorta's version is a spending cap tied to age, not paycheck, paired with a core portfolio left alone. "Put the core in the market and forget it exists," he said. "No venture deals, no alts, no restaurants — not until the portfolio independently covers your lifestyle. If you get there, you've earned the right to take risk."
Brophy keeps the message simple: spend less than you make, stay liquid, diversify and understand what you own. "You already did the hard part," he tells clients. "You do not need to add stress when it comes to money."
The growing debate over athlete financial oversight centers on a structural question: who is actually in charge. Michael Rose of Rose Capital Advisors said the athlete should hold control, with clearly defined roles around them. "Problems arise when trust becomes a substitute for professional competence, or when too much authority is concentrated with any one person without appropriate checks and balances," he said.
LaPorta agreed the athlete typically controls the wealth — and called that part of the problem. "The structure breaks at exactly the point where the person with the least experience has the most authority," he said. "Honestly, a lot of us would be better off with the money in a trust, where a trustee controls allocation and distributions — at least until a certain age."
Brophy said the risk isn't the number of people around an athlete's finances but the lack of clarity among them. "I do not think the athlete needs to become a financial expert, but they absolutely should understand who is doing what with their money and why," he said. "A good structure should protect the athlete, not make their financial life more confusing."
As NIL dollars grow and tax exposure on 1099 income becomes a bigger planning issue, advisors say the firms that get in early — and stay coordinated with the rest of an athlete's team — are the ones best positioned to help this generation turn a short earning window into lasting wealth.

Meanwhile, DPL Financial Partners adds two annuity executives and Prime Capital Financial hires a Mid-Atlantic retirement plan consultant

Andrew Komarow pleaded guilty Thursday in federal court in Hartford to defrauding three financial services companies of close to $3.3 million.

Elsewhere, Cetera picks up a $210 million Connecticut team from MML, while Wells Fargo FiNet adds a San Diego family practice from LPL

“We needed to become a more agile and efficient organization,” said American Express CEO Stephen Squeri.
Examiners will scrutinize fee conflicts, complex products and super intelligence threats as broker-dealers face fresh Reg BI and AML reviews
Knighthead Life entered the market with a competitive MYGA. A strong launch earned advisor confidence and paved the way for FIAs.
As AI makes financial information more accessible than ever, Lana Hock explains why human judgment, trust, and empathy remain the qualities clients value most in a financial advisor

